

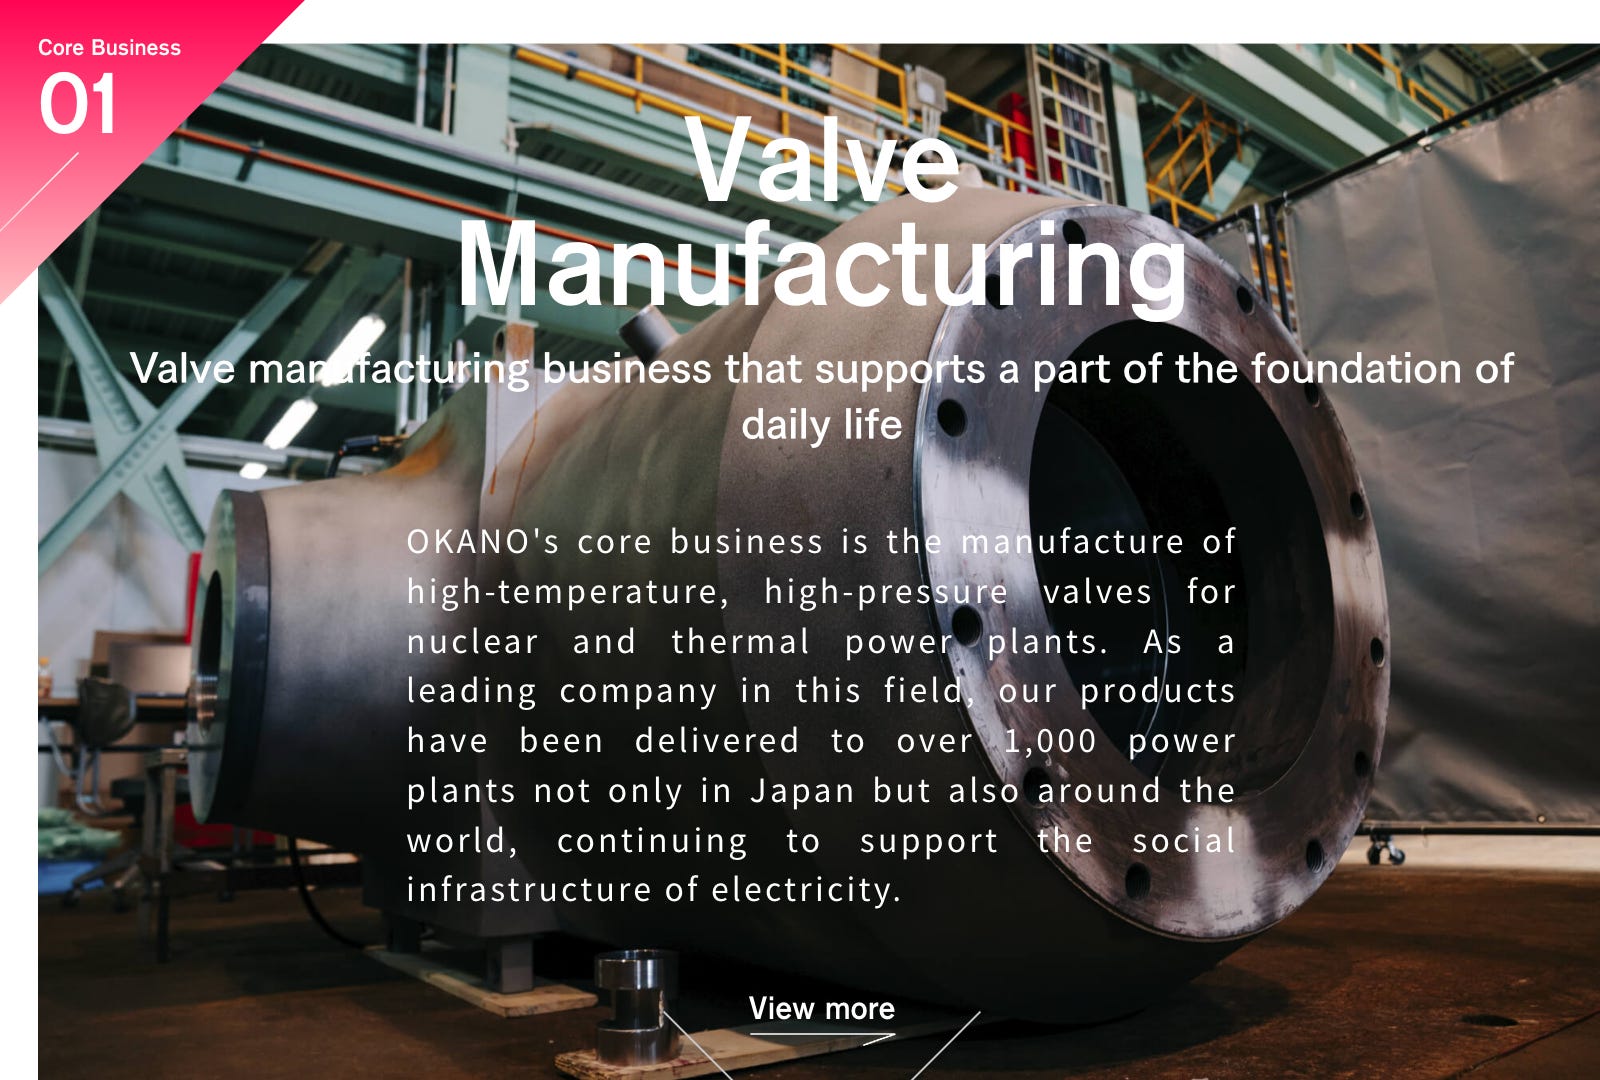
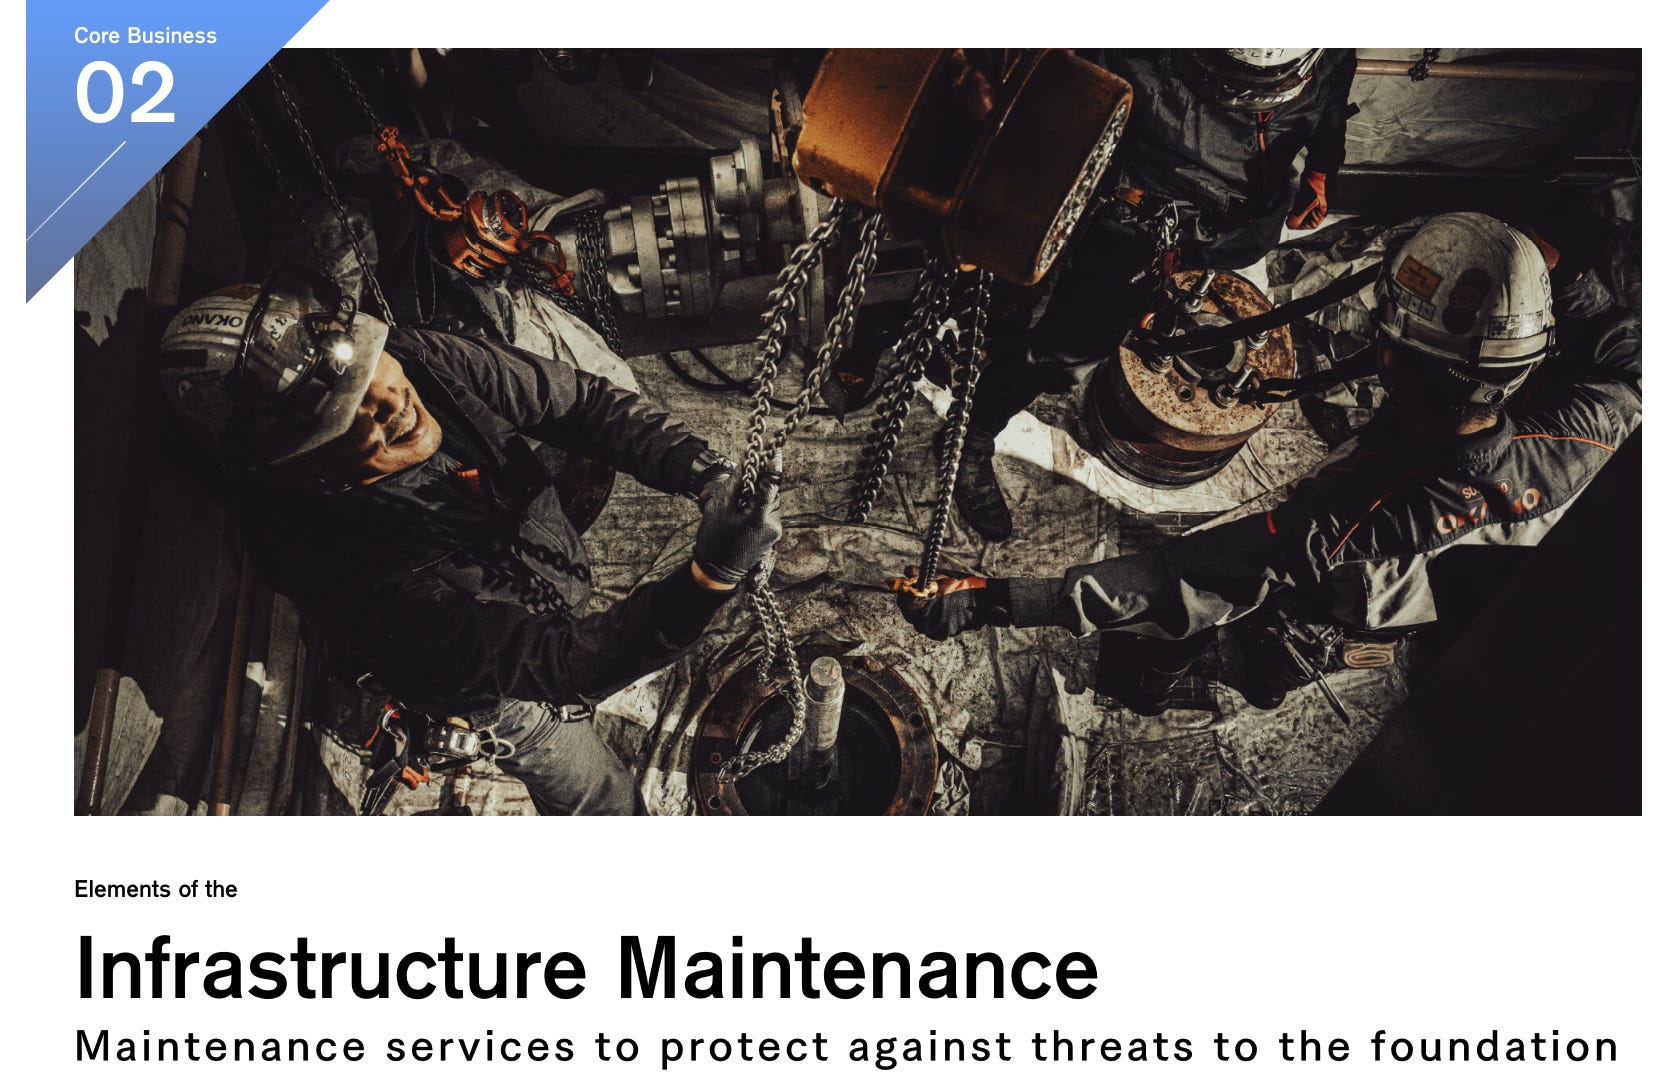
Okano Valve, the leading valve manufacturer and related maintenance for nuclear sites in Japan. Nuclear sites maintenance and survey represents more than 50% of sales and is high margin.
Legal Disclaimer: All content published on Wintergems is intended for informational and entertainment purposes only. It is not intended to serve as a recommendation to buy or sell any security. The views expressed are my own and are subject to change without notice. The information provided here is proprietary. I make no representations or warranties as to the accuracy or completeness of the information provided and will not be liable for any losses, injuries, or damages from the display or use of this information. Readers are solely responsible for their own investment decisions.
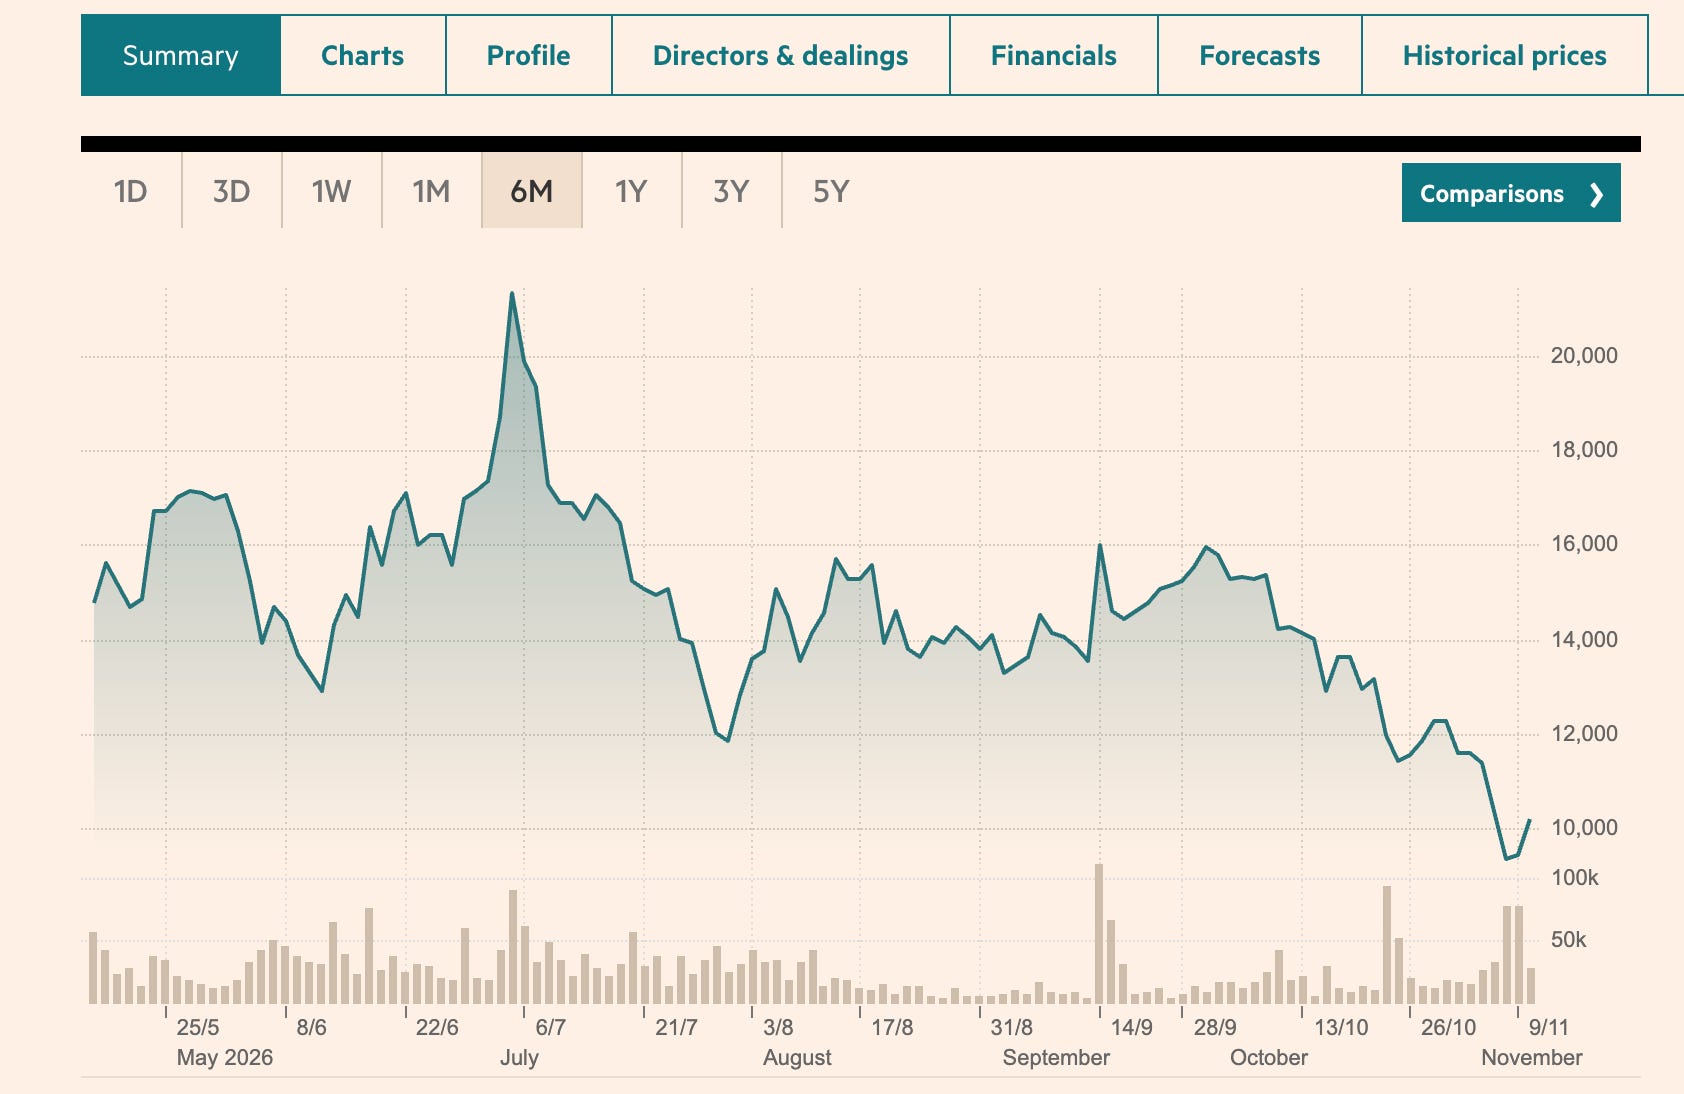
Microcap japan is fun and volatile. As Okano Valve was publishing results Thursday night, at trading lunch on Friday Tokyo time, the stock was plunging to 8500yen as most of the small cap japanese stocks. I was busy buying some shares before close at midnight Thursday night Montreal time at 8500 yen. I started to write this post Saturday. By the time I am done, on Tuesday the stock is back up at 10200 yen.
Still the stock did corrected significantly in the last 6 months and it trading at much more reasonable value than 6 months ago.
The numbers (based on Monday price of 9400yen)
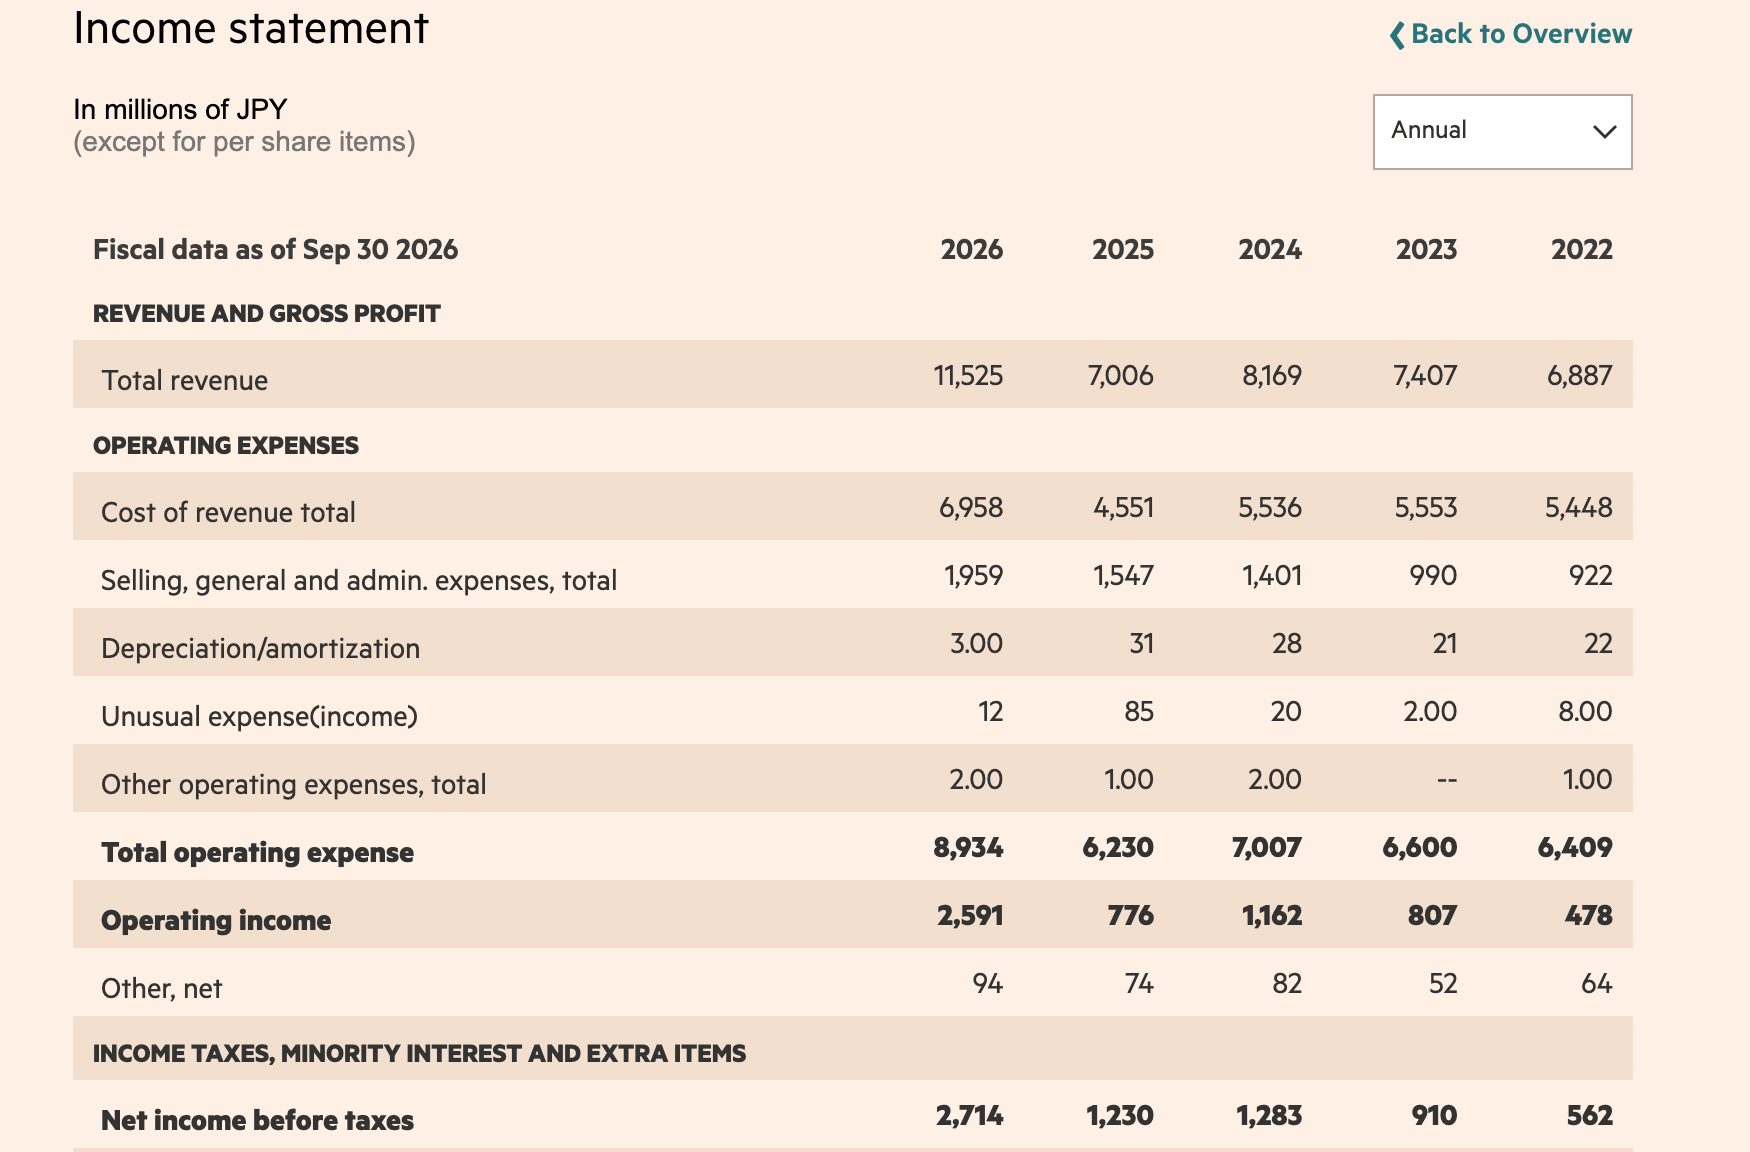
Okano Valve just published some 2026 numbers :
Okano valve TYO: 6492. m=million
2026 Sales : 11525m Yen (YoY +37%)*
2026 Op.inc.: 2606m Yen (YoY +155%)*
2026 Net inc.: 1966m Yen (YoY +99%)*
2026 EPS: 1224 Yen
#shares: 1.6m
Market cap at 9400Yen : 15 040m Yen or 95m USD
Cash : 5 772m Yen
Receivables - payables: 3 200
LT investment: 2 775m Yen
Tangible book per shares: 8750 Yen per share
P/B = 1.07
P/E (trailing) = 7.6
P/E (ex cash) = 4.7
* For 2025 I use the published numbers times 1.2 to adjust for the 10 month reporting period in 2025as the company changed its fiscal end year to September.
The EPS has gone up significantly over the past 5 years
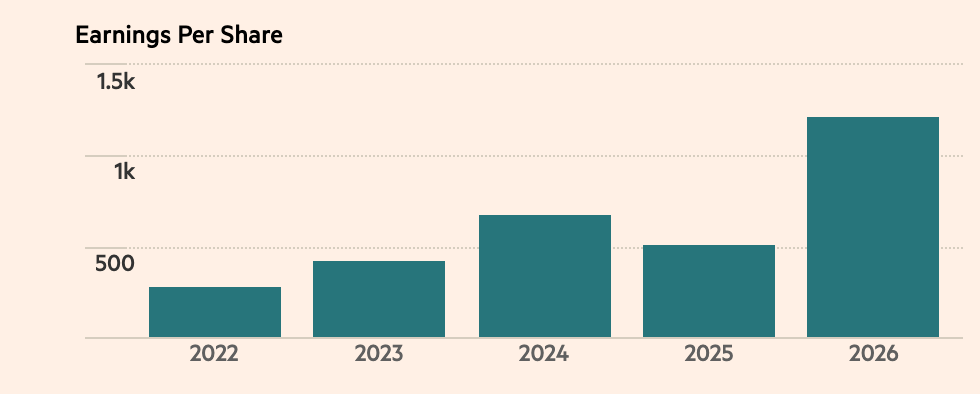
The Business
Okano Valve is a micro cap deeply involve in the nuclear industry in Japan. They are the largest nuclear valve manufacturer in Japan. About 50% of their sales is coming from maintenance. They make most of the valves of the BWR nuclear plants which used to be the dominant technology until the Fukishima disaster which have been developed by Hitachi. Now Hitachi is part of the GE Vernova - Hitachi joint partnership. It is very unlikely that it will get business of the BWRX-300 that will be built in Ontario. Velan will likely get that business. They also make a good amount of valves for the secondary loop (the steam loop) of PWR nuclear plants developed by MHI but TVE makes the valves of the primary loop.
Three BWRs have restarted in Japan in the last 2 years, Onagawa #2, Kashiwazaki-Kariwa #6, and Shimane # 2. These were the first BWRs to get restarted since the Fukushima disaster in 2013. Two other BWRs should restart by 2028-2029 timeframe Kashiwazaki-Kariwa #7 and Tokai Daini. Shimane #3 the first new nuclear plant being completed post Fukushima is targeted to start in 2030. Beyond this decade, 2 or 3 BWRs more should be restarted. So by 2035 we should have a fleet of 7-8 BWRs/ABWR in operation requiring periodic maintenance.
Okano valve is deeply involve in the decontamination of the radioactive water in the Fukushima area using the Advanced Liquid Processing System or ALPS. ALPS is a process where contaminated water are filtered from their radioactive elements whichare then stored in tanks for a period of time to reduce naturally the radiactive level. Then mixed up with salt water to a 1:100 ratio and slowly release to the ocean. Okano valve provide valves, actuators and operation monitoring. Toshiba, Hitachi, Toa Valve, Ebara pumps are also involve. The ALPS decontamination process should go on for at least until 2050.
Okano valve is also working with Hitachi-GE consortium for next generation nuclear plants SMR BWR for the export market (Asia mostly) and the new HI-ABWR.
Competitors
The main domestic competitor is TOA Valve - $6466. TOA valve is not pure play like Okano valve, with business in Steel casting (which is loosing money) and some electrical related product. However, the bulk of the profit is coming from the maintenance of nuclear sites, but the PWR type.
Other competitor is Velan, based in Montreal. They should win the business of the Darlington GE-Hitachi SMR for the valves not Okano Valve. Now Velan is loosing money left and right. Not sure they can compete effectively with new product and can invest extensively in R&D.
Investors
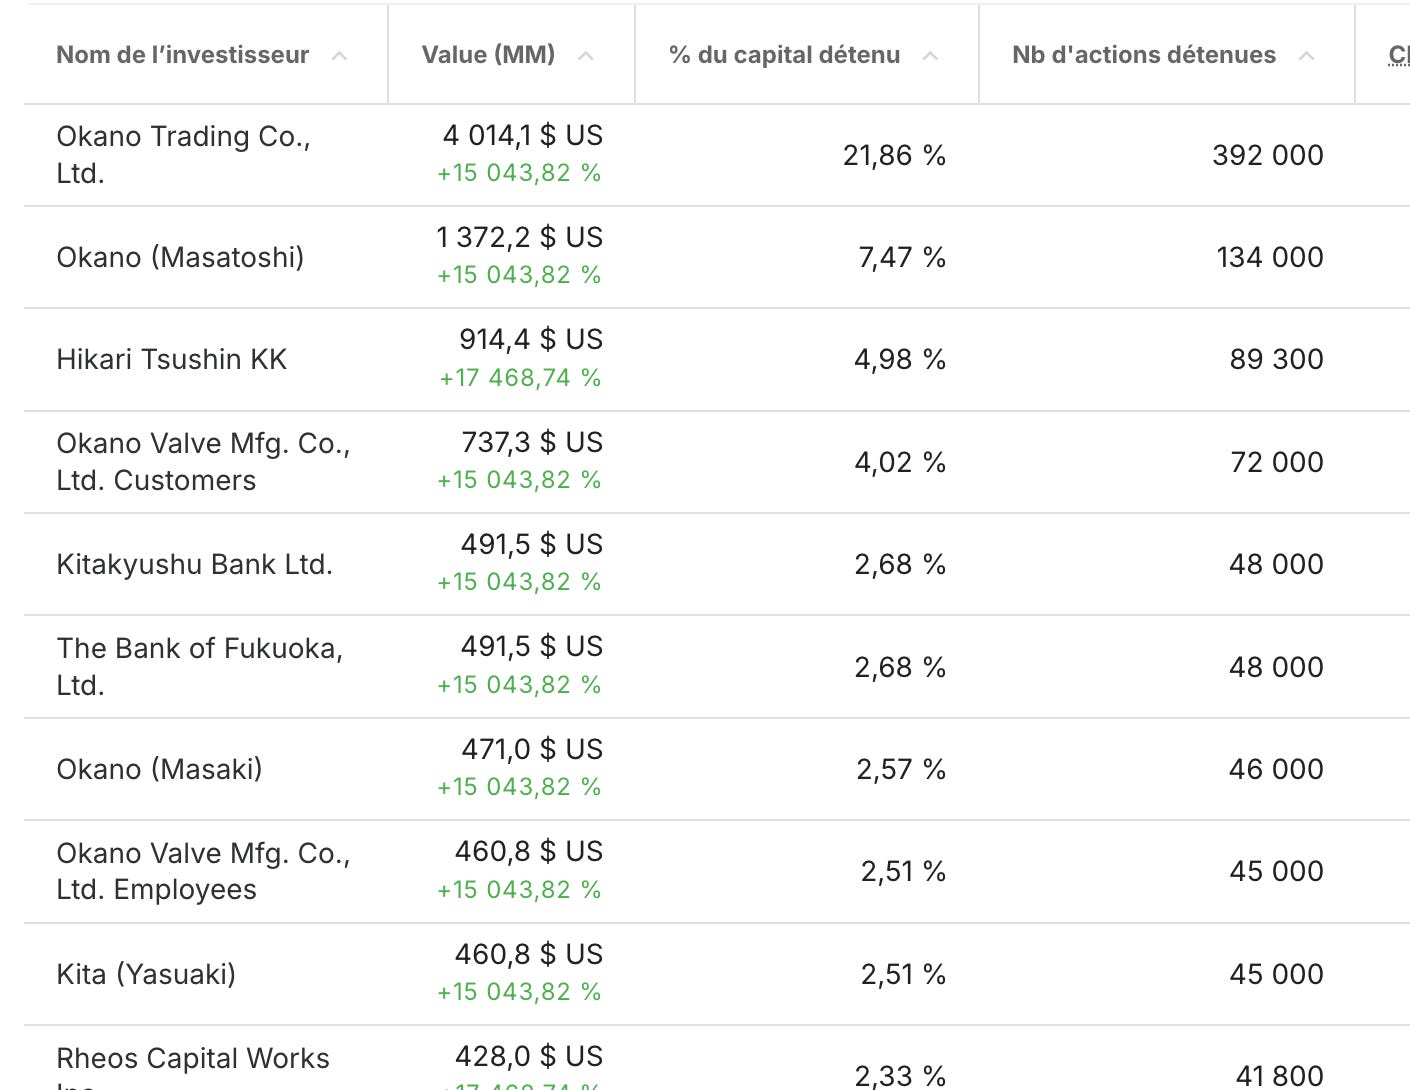
So Okano family owns 10% directly and another 22% from the Okano Trading entity. The CEO is Takeharu Okano, 45 years old. A takeover would be very unlikely.
Hikari Tsushin is 5%.
Ultra Conservative Projections
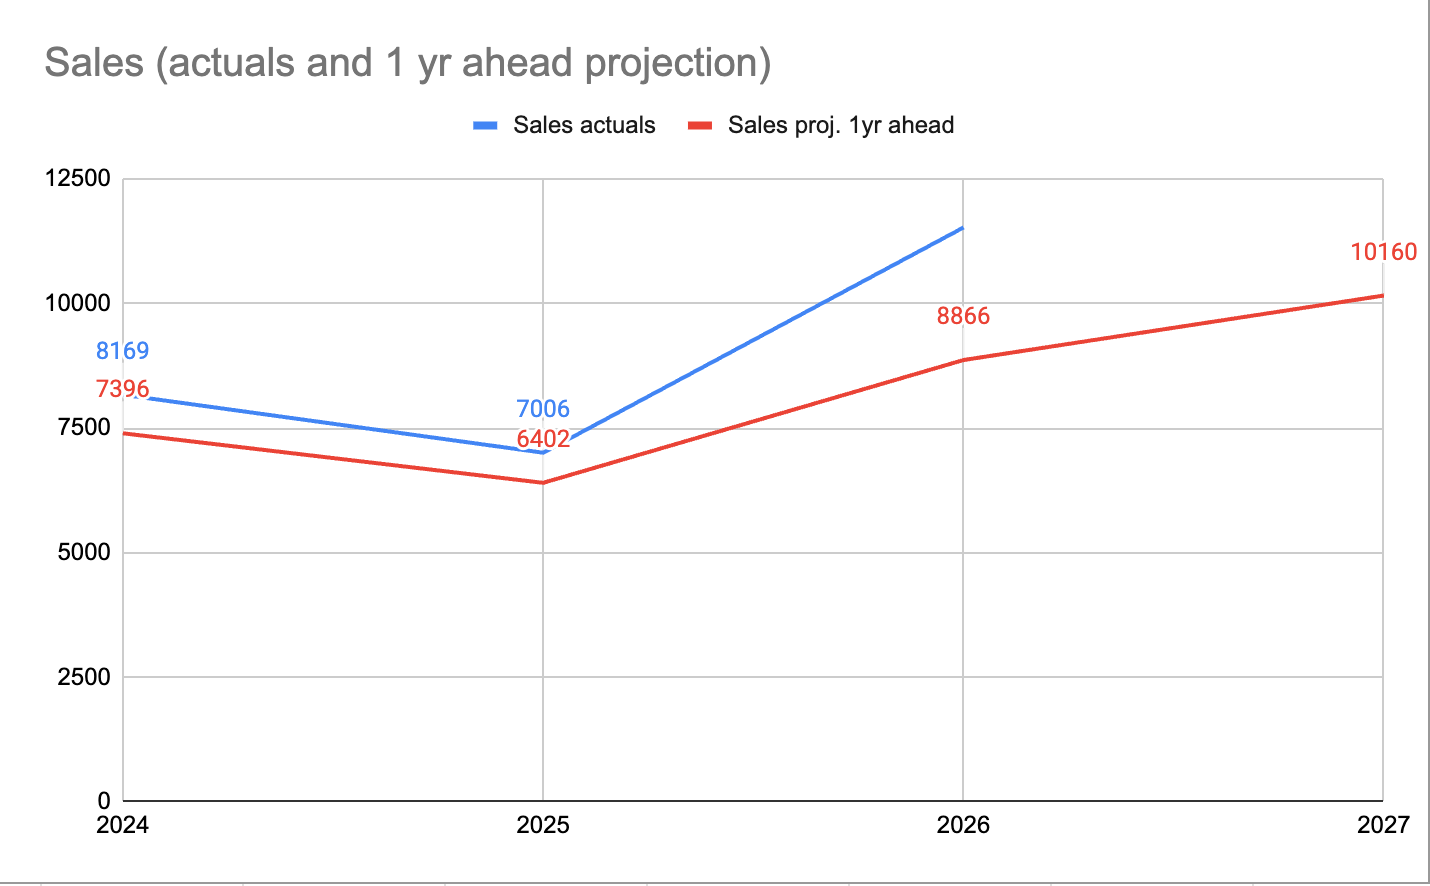
When the company announced fiscal year results, it typically announce a conservative sales projection and some very pessimistic profit guideline.
To illustrate this, I provided the estimates from the company at the beginning of the fiscal year for 2024 (issued end of 2023), 2025, 206 and 2027 (which was issued last week). For sales, the company has been systematically under-estimating sales by 10-30%. You can see that 2026 was exceptionally good beaten the Company estimates by 30%.
For operating income, the Company estimates is way off: where actuals were 55%, 63% and 169% higher than 1 year ahead estimates.
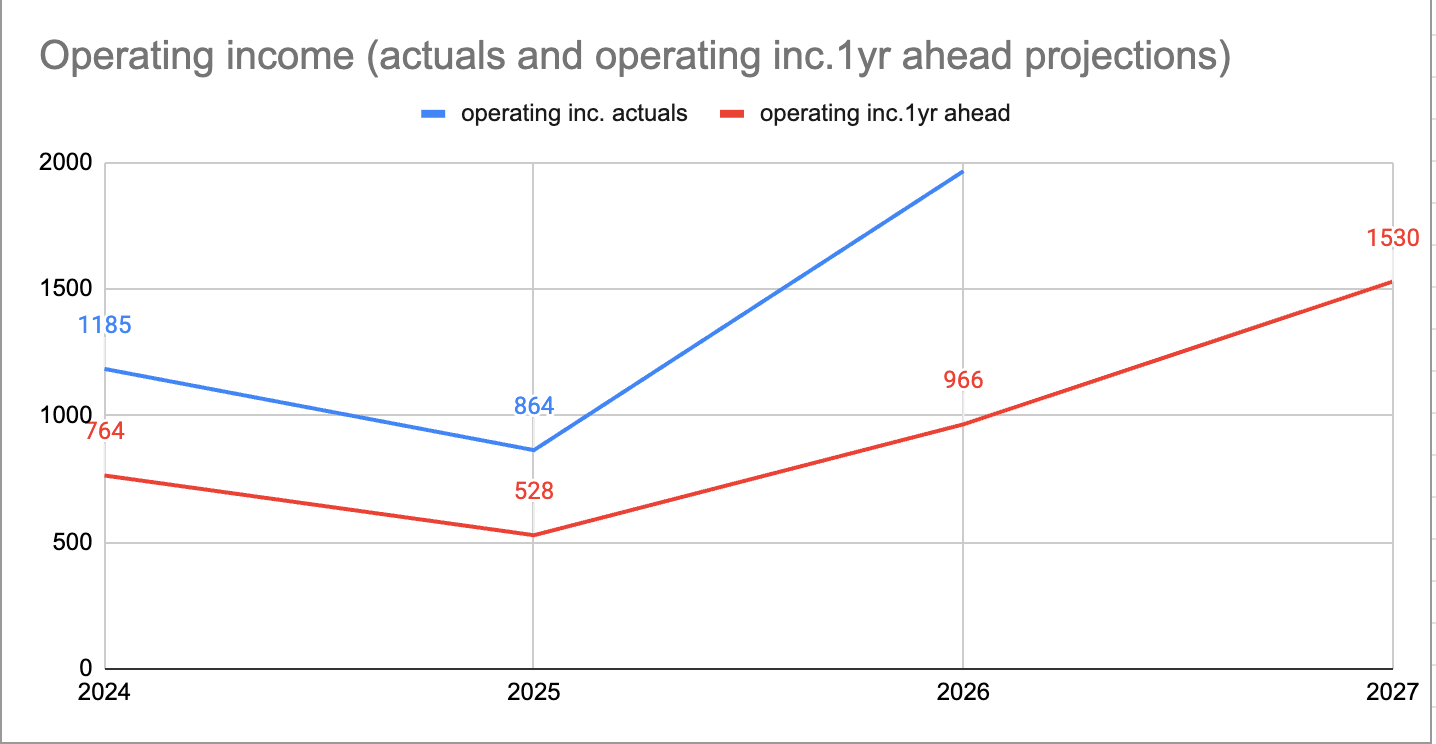
For the year ahead, the Company is estimating operating income of 1530m Yen. Still much better than last year estimates, but way lower than the actuals of 2600m Yen achieved this year. 2026 may have been exceptional in terms of maintenance, having 2 restarted nuclear plant doing an intensive maintenance check after operating for 13-15mo post restart, but KK6 should be within that window in 2027. Something in the middle higher than 1530 but a lower than last year 2600m could be a more realistic estimate. Getting to 800-900 EPS level would be fine for me.
We also have a good floor with a book value now at 8750yen per share, which should climb to 9500yen per share at the end of 2027.
Cheers,
Legal Disclaimer: All content published on Wintergems is intended for informational and entertainment purposes only. It is not intended to serve as a recommendation to buy or sell any security. The views expressed are my own and are subject to change without notice. The information provided here is proprietary. I make no representations or warranties as to the accuracy or completeness of the information provided and will not be liable for any losses, injuries, or damages from the display or use of this information. Readers are solely responsible for their own investment decisions.