

In this analysis, I am taken a look “Under the hood” at the Four Segments of Gérard Perrier. The case I am making is that the operation of Four segments have shown very different behavior and there is a sharp contrast in terms of sales growth, operating margin, stability and so on. The best way to model this company is to take each segment on its own. Further, in the analysis I will take a normalized view of each operating business to better assess the latest results. Stay tune.
Oh.. and I put on pause my X account again so here is the only way to reach me and my preference would be using the comments below.
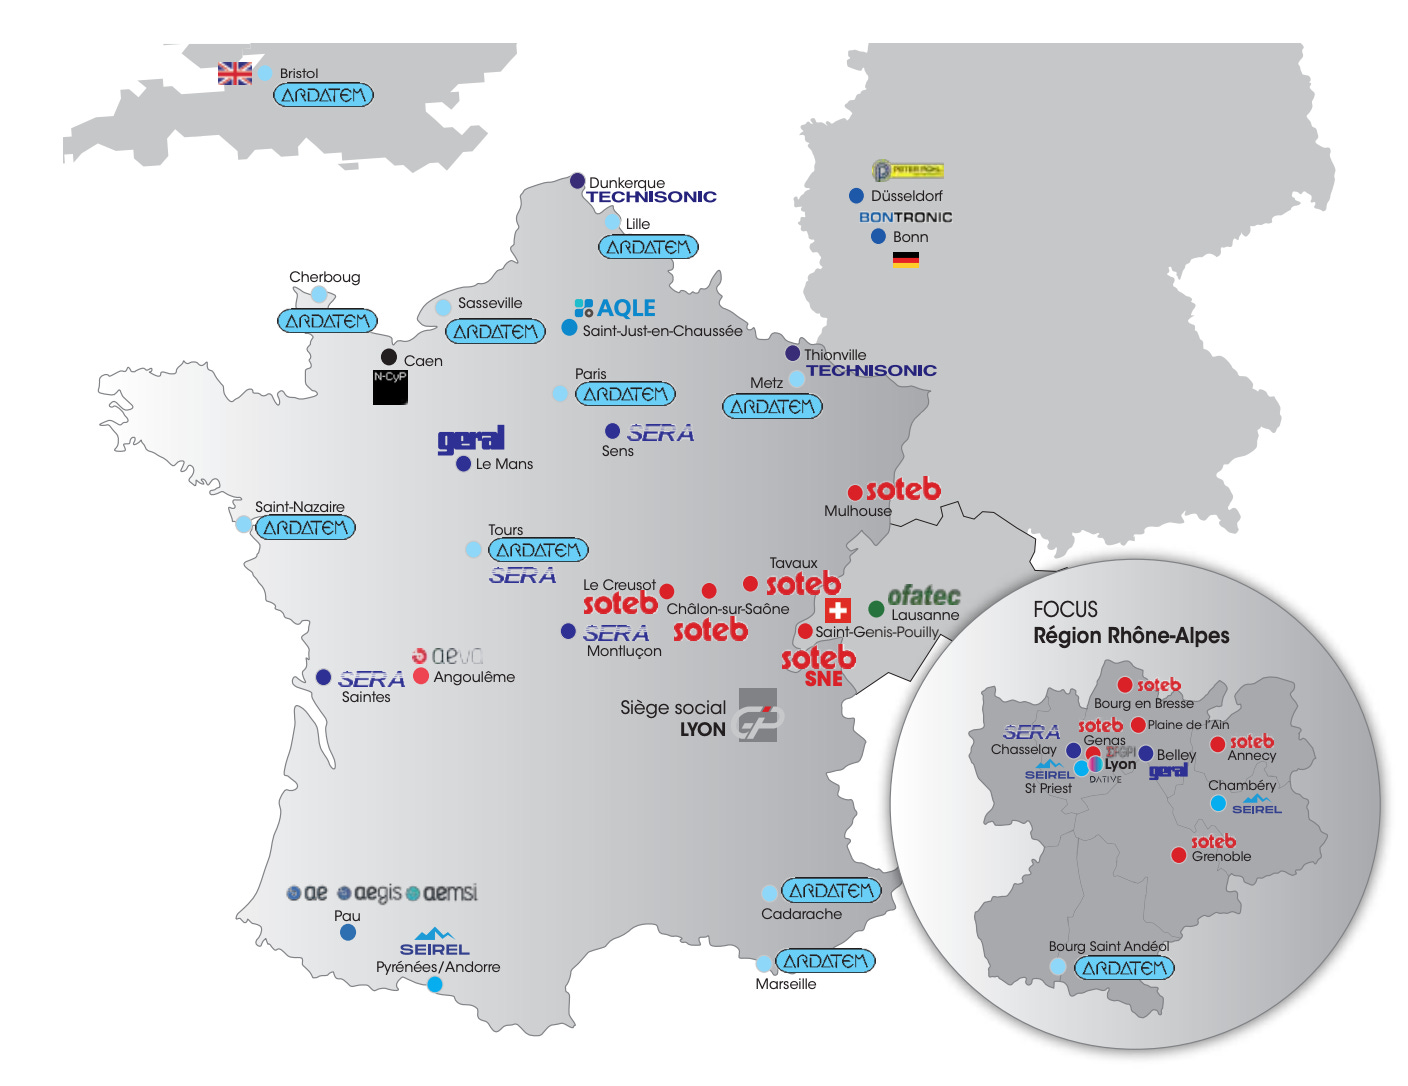
Map showing the locations of the Gérard Perrier operations
No text below was generated by LLM so all hallucinations or errors are solely due to the author.
Legal Disclaimer: All content published on Wintergems is intended for informational and entertainment purposes only. It is not intended to serve as a recommendation to buy or sell any security. The views expressed are my own and are subject to change without notice. The information provided here is proprietary. I make no representations or warranties as to the accuracy or completeness of the information provided and will not be liable for any losses, injuries, or damages from the display or use of this information. Readers are solely responsible for their own investment decisions.
The French market is in disarray due to rising interest and politics tension. An ocean is separating me from all this, but I do feel really sorry for all challenges that the French people are and will be facing. As a French Canadian, I have a strong connection with the French people. I truly believe that something positive will come out of all this …hopefully. But at the same my macro view of the French economy is superficial and so I am not on solid ground for this aspect. So you are warned…
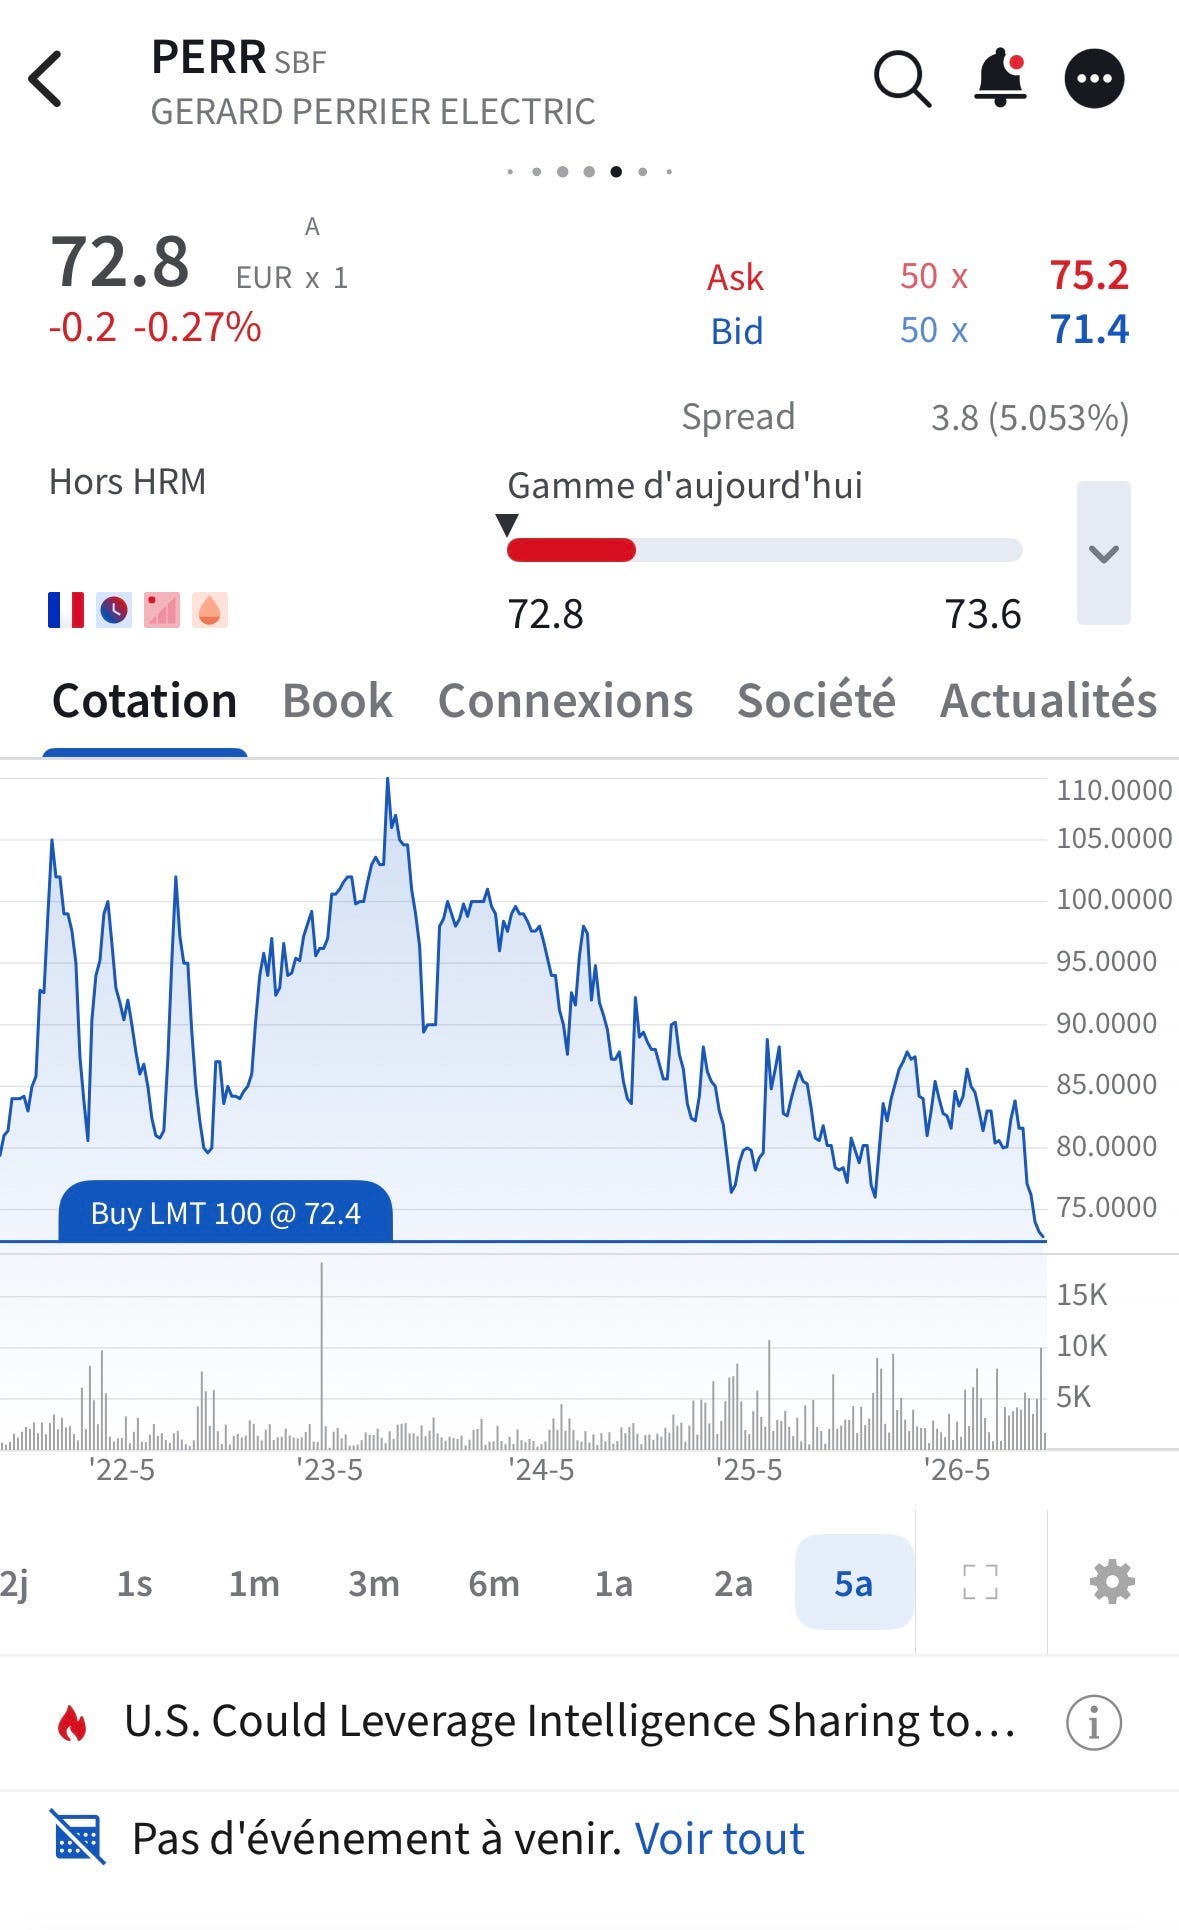
This results in Gérard Perrier trading at a 5 year low as shown below, mostly due to a French market sellof and a strange decision to move to a 2nd tier market in September - Eurogrowth - forcing some funds and most ETF to exit from the stock. Forced seller is music to my ear.
This is an actual bid I have below - still waiting to get those shares. As a disclosure, Gérard Perrier is a top 5 positions and my cost is not very far to the current price.
Before we dig in on the recent results and historical results of the last 5 years, I would invite to look at a memorable post from Memyselfandi007 published in 2013 about the company which made me buy almost instantly some shares in 2013. You will find interesting statistics on historical growth pre-dating 2013.
Gerard Perrier SA (ISIN FR0000061459) – French “Hidden Champion
In those years, coincidently I had been looking at investing at companies providing electrical services only. As a background I am an electrical engineer myself and I knew how nice this type of business is and how sticky it can be. In North America it is very fragmented industry and very difficult to buy as a standalone business except via the large Engineering firm A&E often bundle with EPC which includes large civil engineering arm and project management which tend to be messy. In France, Bouygues has an electrical services operation for example but it is bundled with large civil engineering operation and project delivery. It has also a lot of debt which is painful at current rising yields.
Recent result: Solid Sales & soft rebound in earnings - Relief!
Gérard Perrier published some solid earnings today with operating income up 20% to 11 013 992 Euros, sales is up 10% and EPS is up 16% to 2.09 per share.
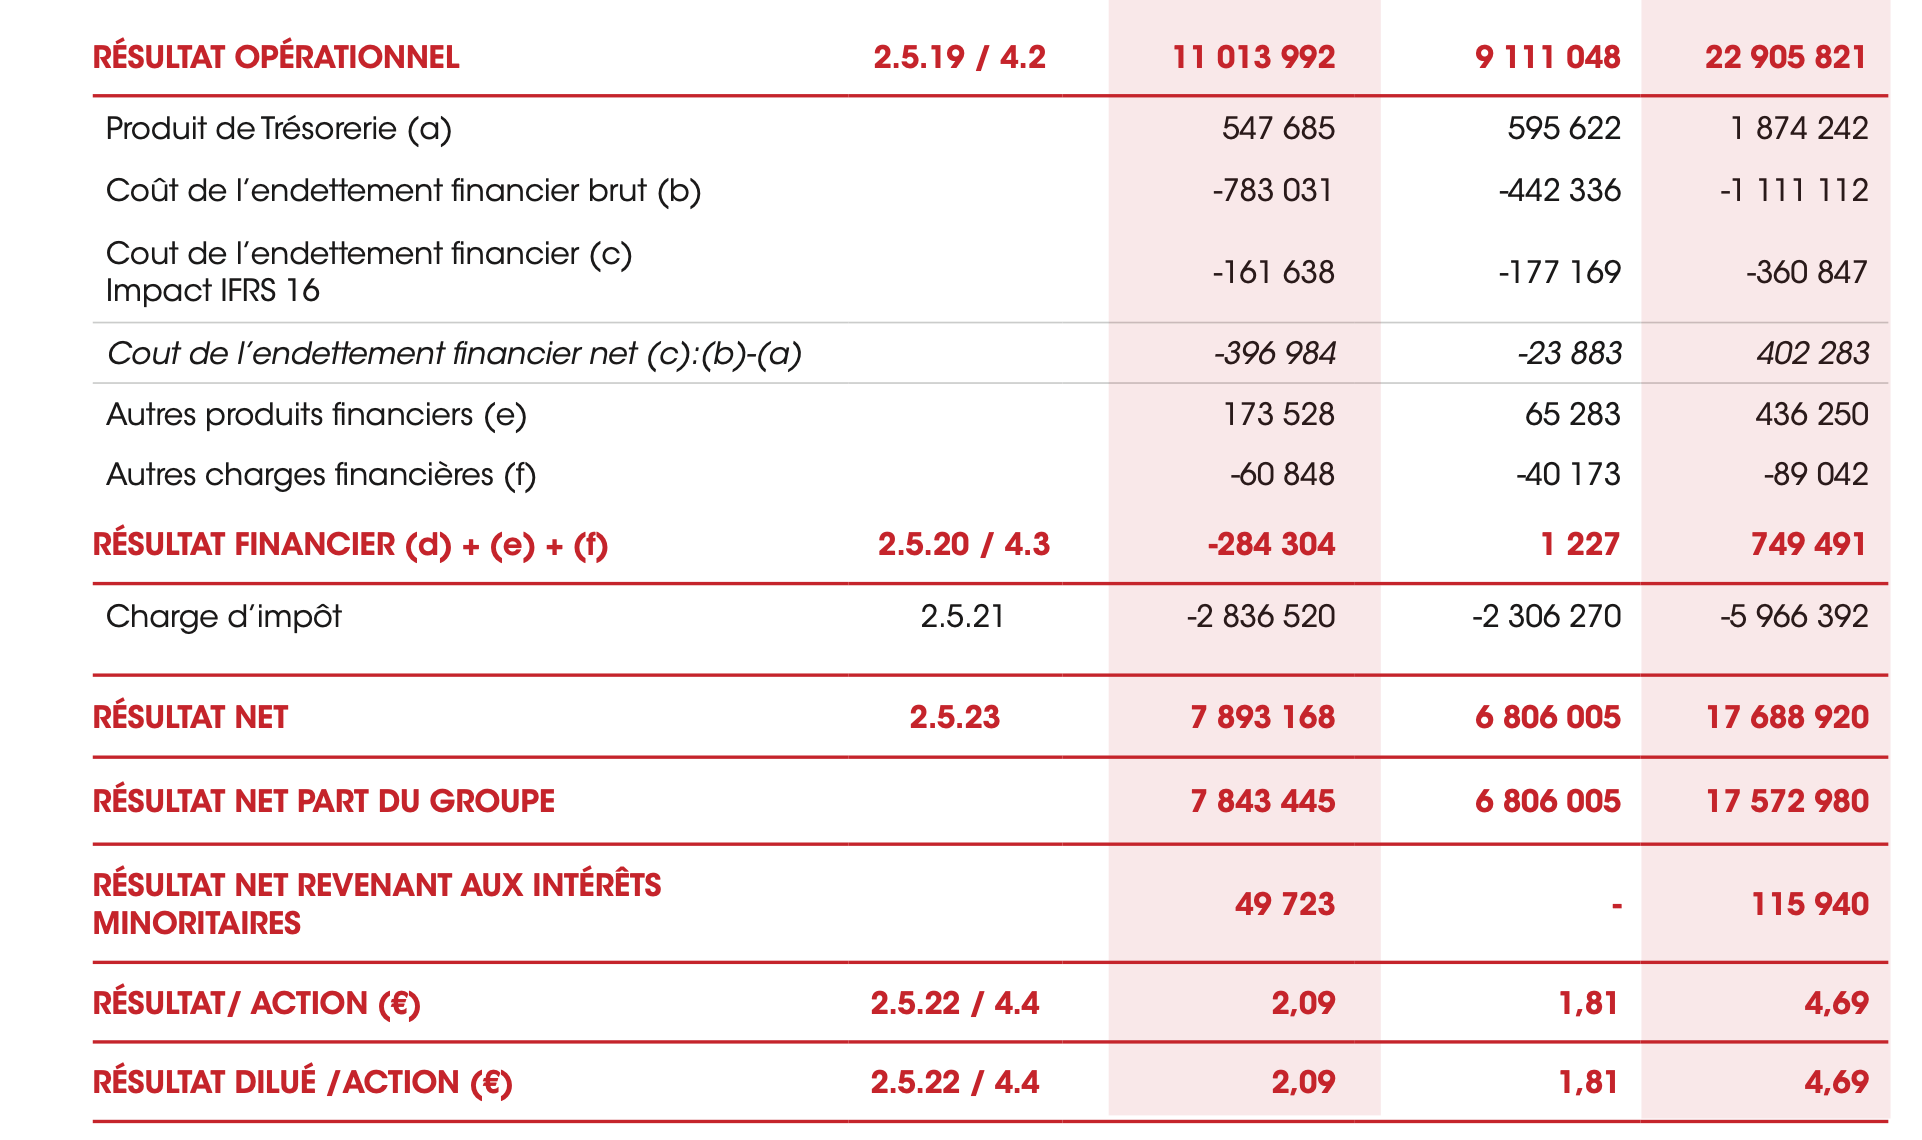
This resulted in a operating margin of 6.23%. This is better than last year operating margin of 5.75%. As I mentioned a few times, Gérard Perrier has seen its operating margin decreasing in the last few years. So any improvement in this aspect gives me a sense of relief. Top line growth has been consistent and is not a problem.
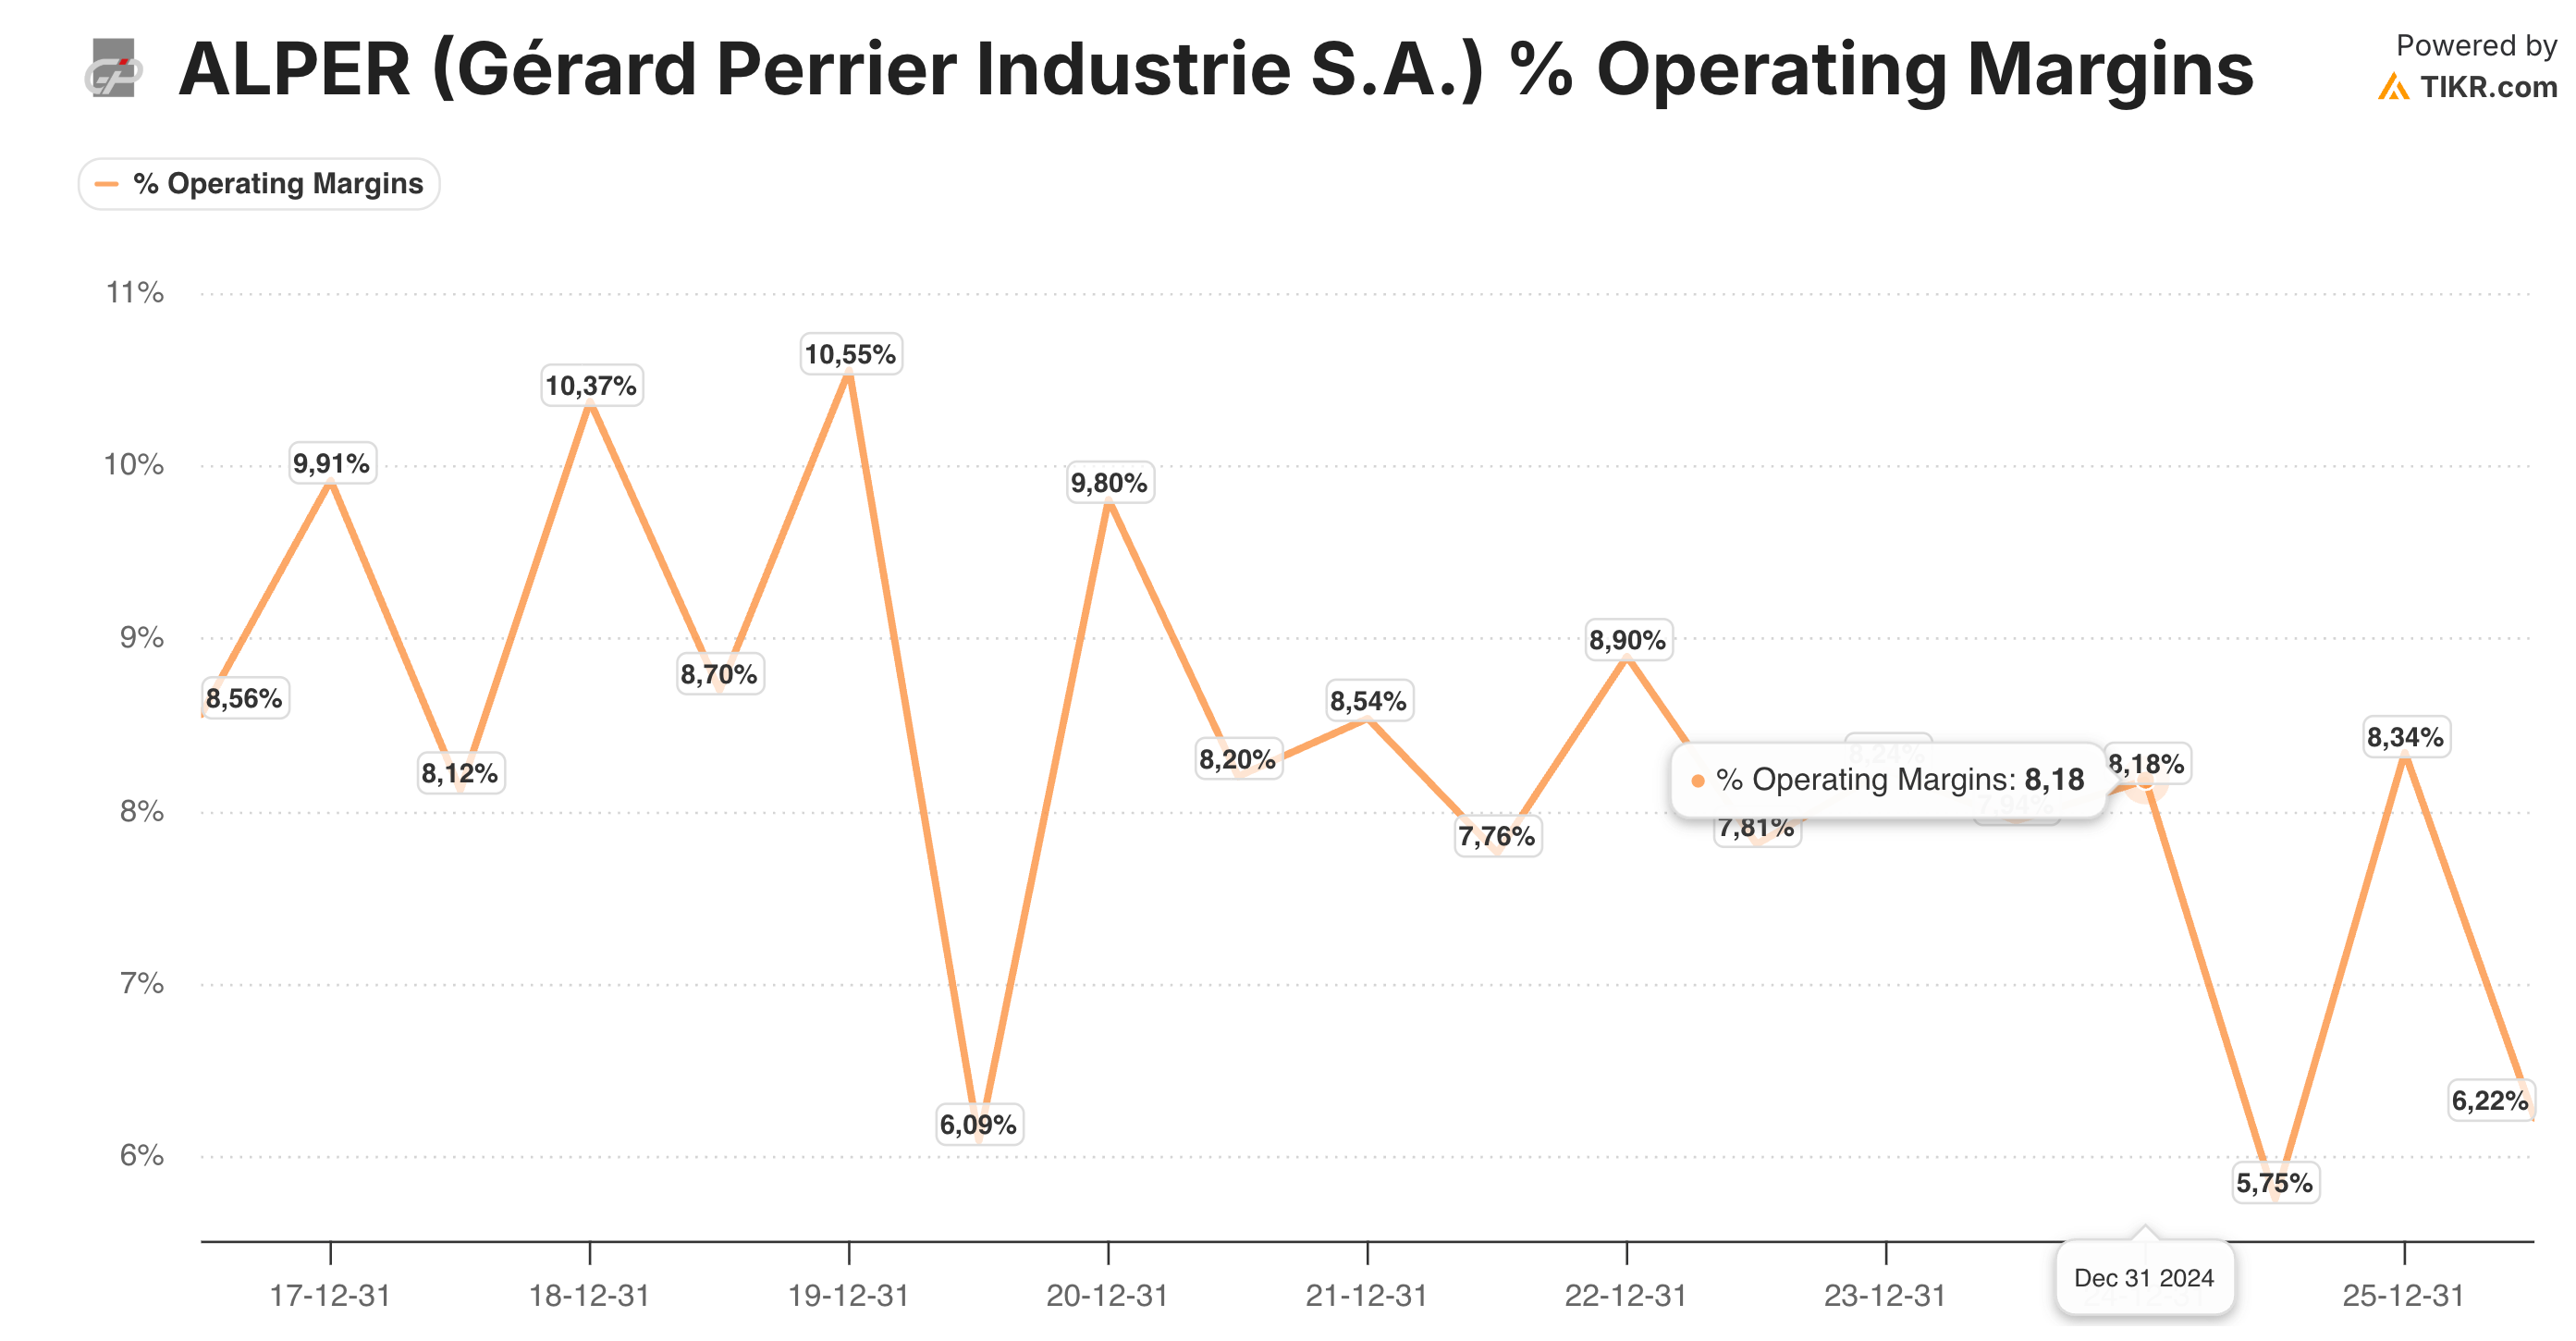
Now if you look at the operating margin, although operating margins has rebounded from 1H2025, it is a soft rebound - 6.22% versus 5.75% last year. But if we compare to the last 5 years, which average around 8%+ there is a lot of ground to cover to get to that historical level.
4 segments with strong contrast in operating income
The company reports sales and operating income in 4 segments as shown below:
Installation et Maintenance: Soteb, Ofatec, N-Cyp, Dativ
Fabrication et métiers: Geral, Sera, Seirel
Energie: Ardatem, Technisonic
Aéronautique et Défense: Aece, Aqle, Somalec, Aeva
Another view presented by the company showing the different subsidiaries based on the market (Vertical Axis) and type of services (horizontal Axis). This shows for example that although only sales of Ardatem and Technisonic are under the energie (nuclear) segment, some sales from Geral reported under fabrication, does relate to the Nuclear industry.
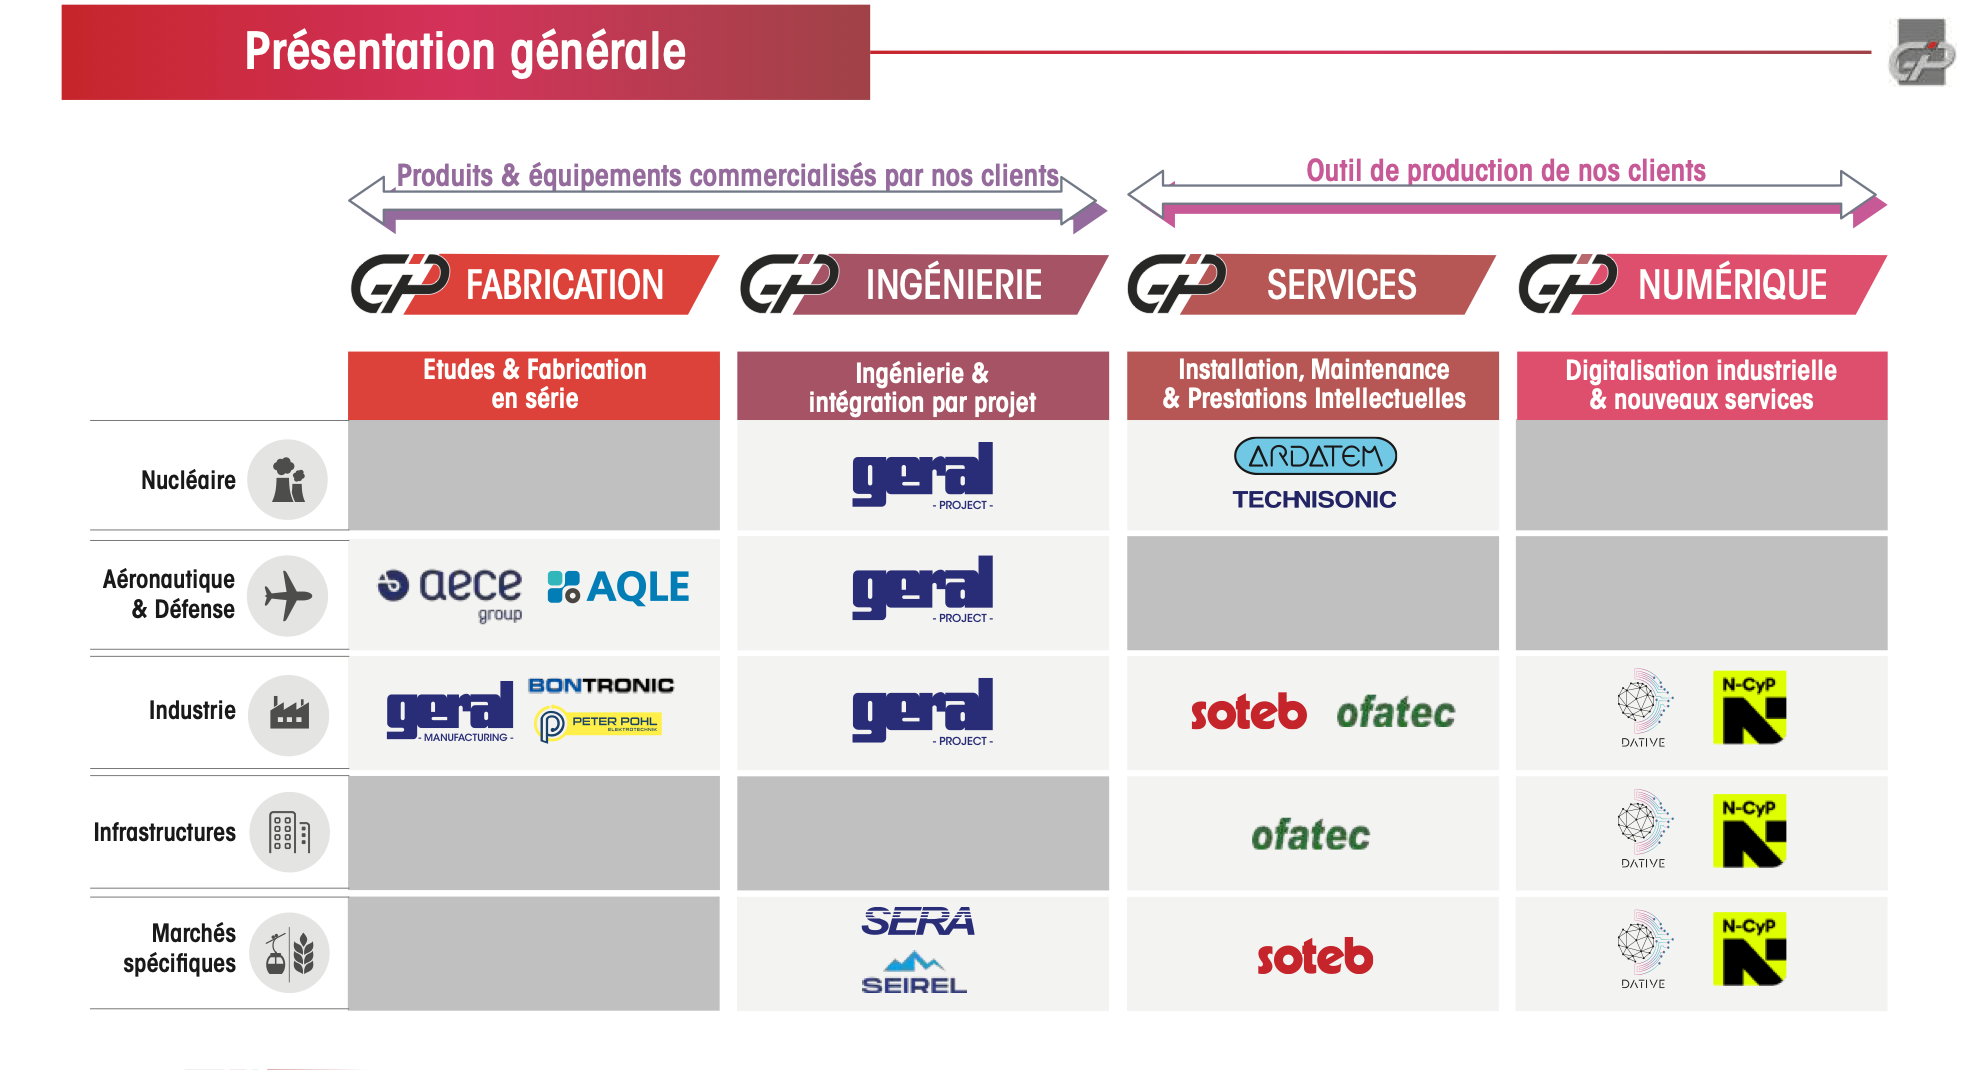
If we look at the results of last semester, we can see a sharp contrast in terms of operating margin from best to worst:
Installation Maintenance: 11.81%
Fabrication et spécialistes métiers: 6.20%
Énergie : 3.61%
Aéronautique: -0.76%
Thankfully, the relative importance of the segments in term of sales also follow the same ranking. So we have the two biggest segments operating well.

If you look at the previous 1st Half semester - 2025, we get the same ranking

Lets look at each segment individually over a 5 year period so we can better understand the situation and attempt to normalize earnings
Installation Maintenance
The main subsidiary of this segment is Soteb. This is also the largest and oldest subs.

They design and install electricity solution for a broad set of industries (pharma, chemistry, oil, steel, agro, hydro) and provide a wide array of services, going from high voltage, to low voltage solution, process automation, instrumentation solution. They are mostly in the West part of France and in the French part of Switzerland. They have the CERN has a customer. They also purchased Ofatec based in Switzerland recently which provides services specialized in securing and ensuring the reliability of electrical power networks for sensitive location including data center.
Cloud services Dativ is also part of this segment.
I have charted sales of the “Installation et Maintenance” segment per semester for the last 5 years :
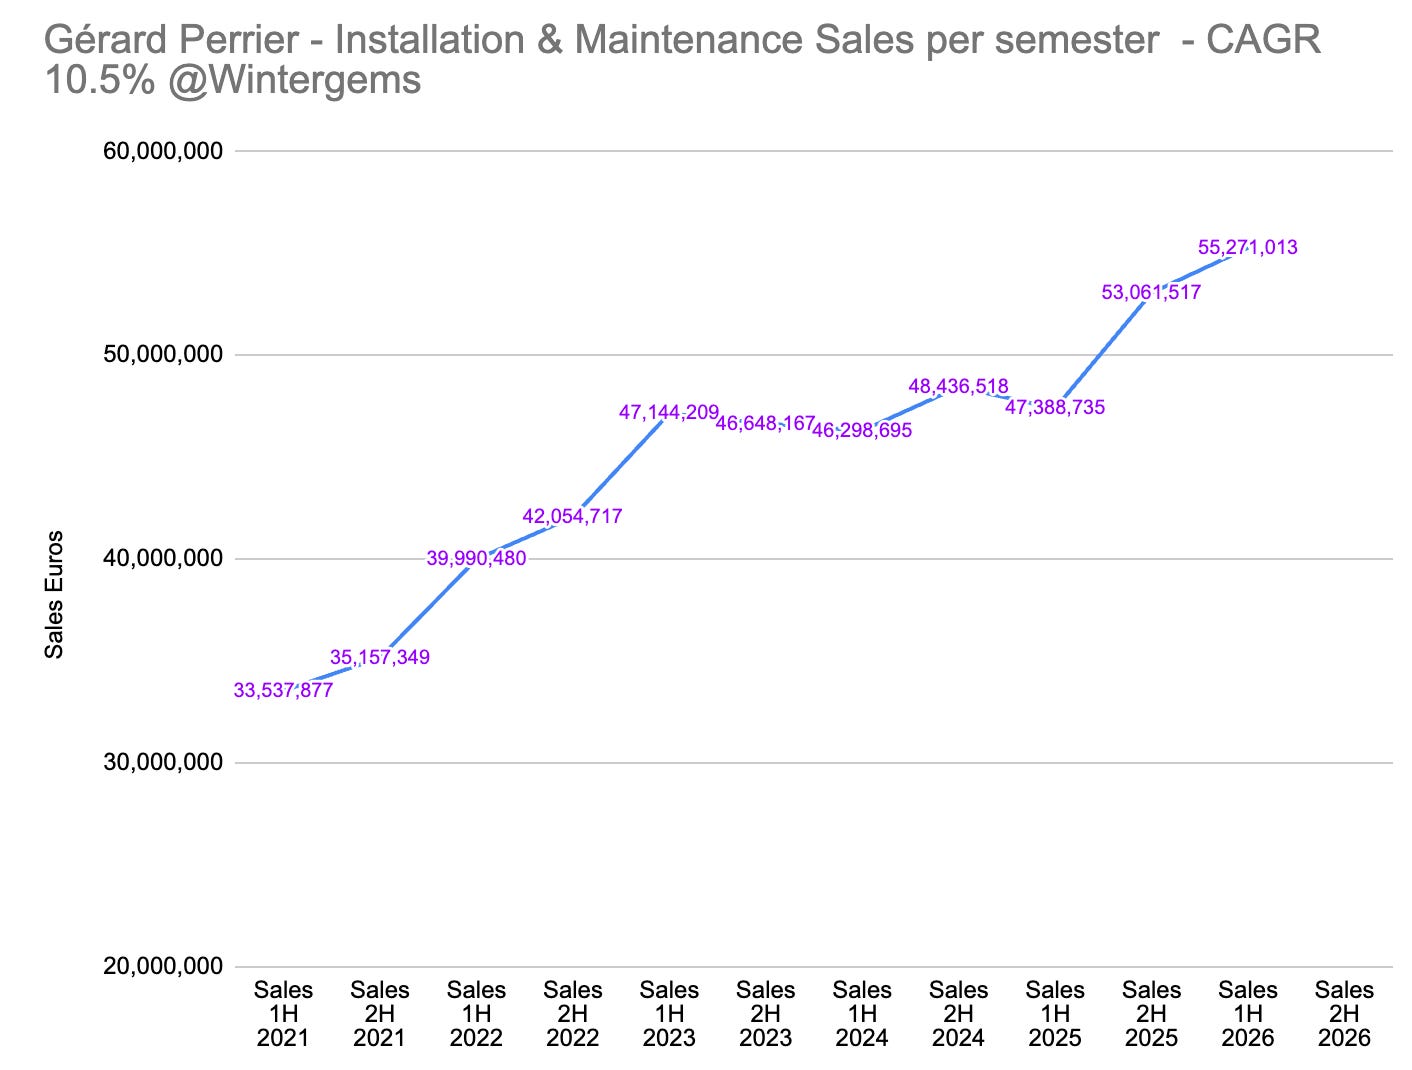
This segment has seen a constant upward trend since 2021, with a CAGR of 10.5%. Ofatec acquisition did contribute to the recent growth, so not all is organic.
If we move to the operating income margin, the situation is positive. We have seen operating income hovering below 10% for the first part and now trending between 10% and high 11% since 2023. Average operating margin over the last 5 years is 10.7%.
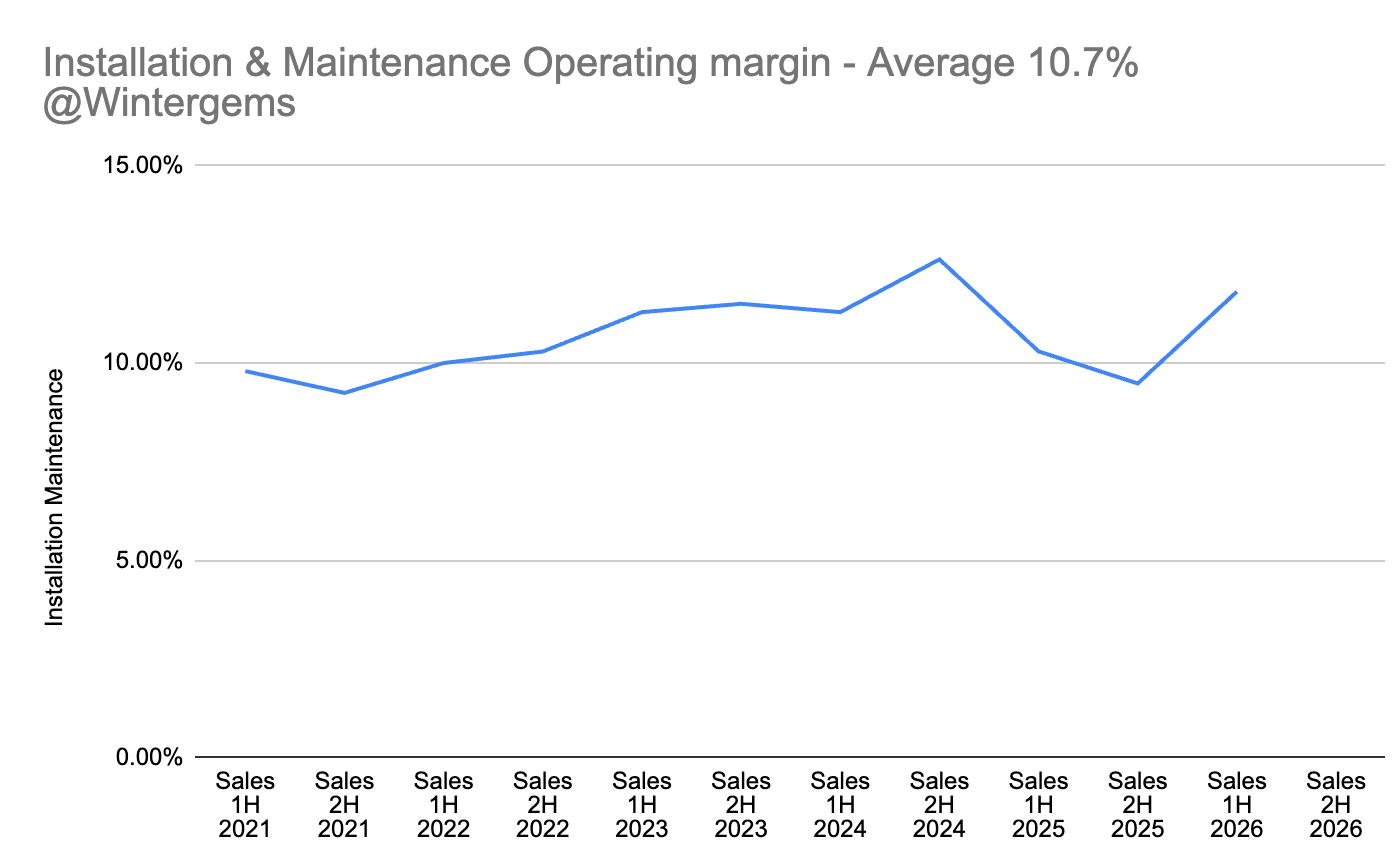
In the last semester, this segment represents roughly 60% of the total operating income.
Fabrication et métiers
The most important subsidiary in this segment is GERAL. GERAL design and manufacture of tailor-made electrical and electronic equipment for automated systems and electric power supply of industrial machines and processes. GERAL is the second oldest and second largest subsidiary of the Group.
It also provides End-to-end assistance, from design to commissioning with a multi-technique integration capacity. The segment also regroups SERA, SEIREL and Bontronics in Germany.
I have charted sales of the “Fabrication et métiers” segment per semester for the last 5 years :
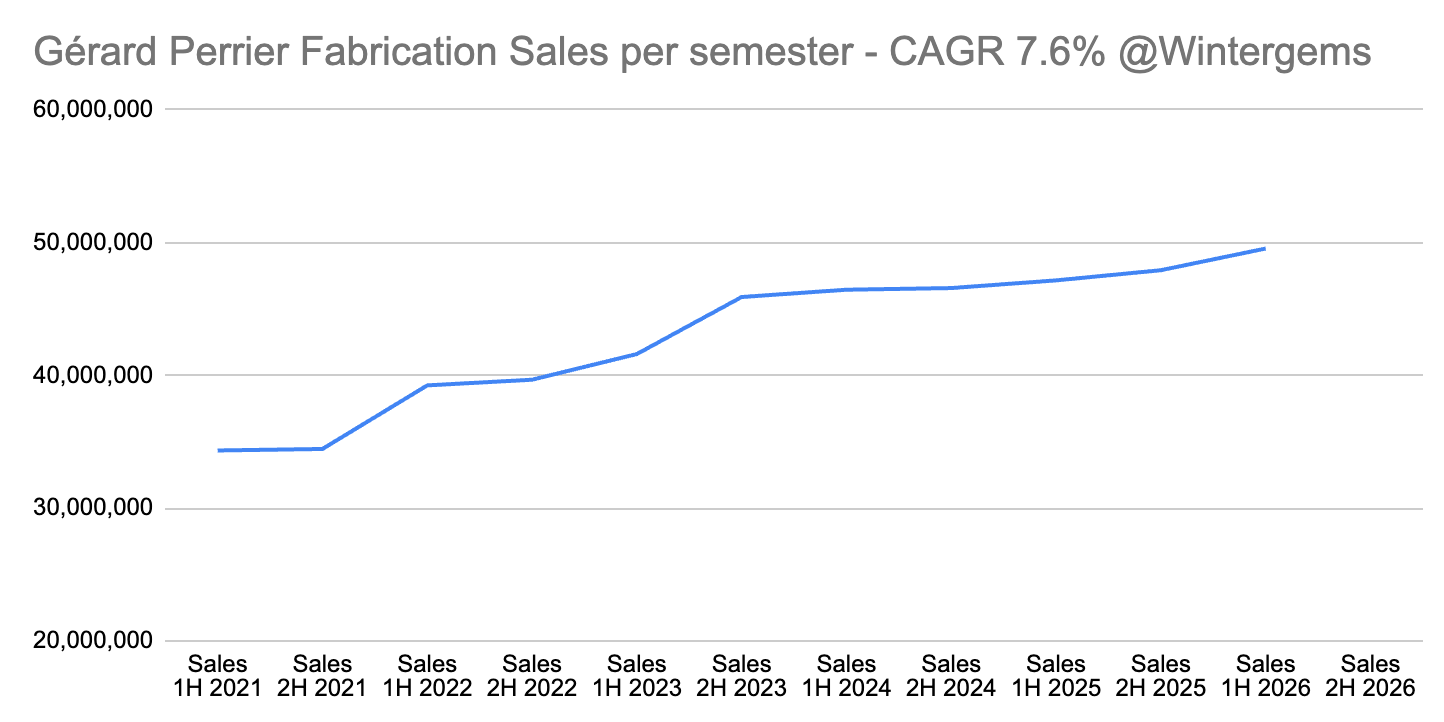
This segment has seen a constant upward trend since 2021, with a CAGR of 7.6%. I am not aware of many acquisitions recently so this is mostly organic.
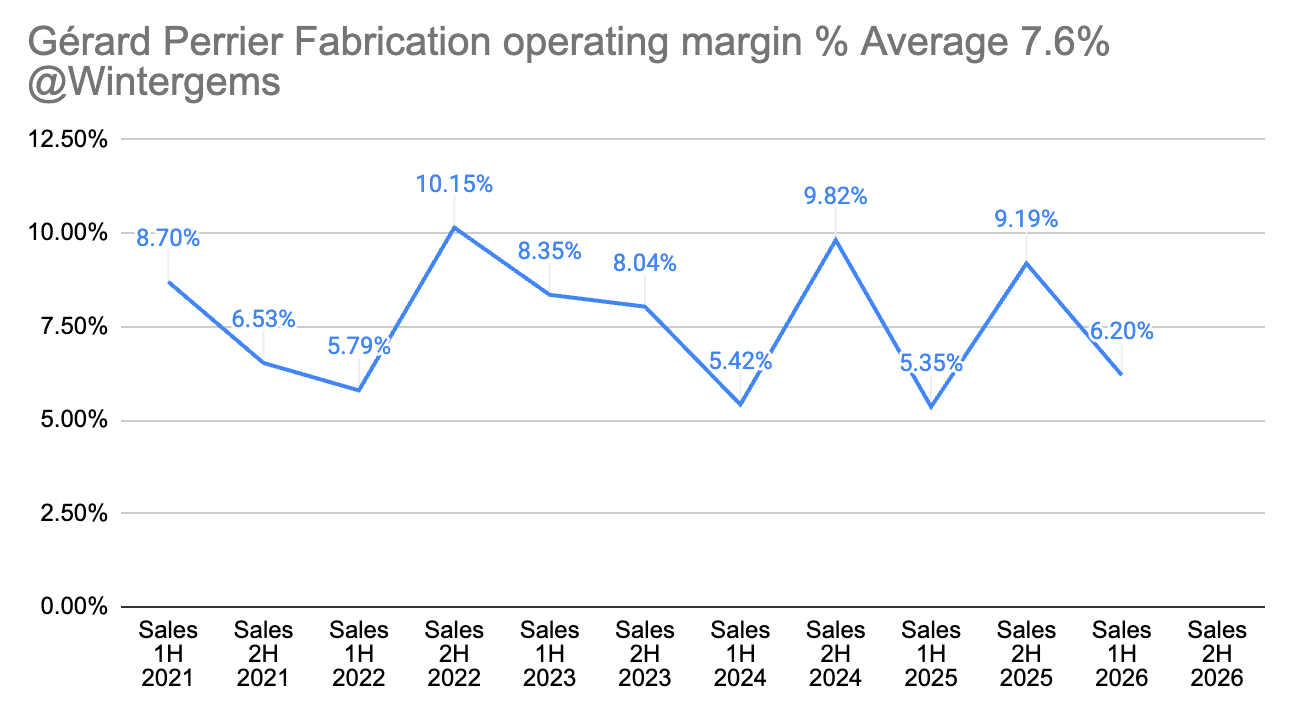
Clearly there is a seasonality aspect here - 2nd half seem to exhibit better margin for the past 2 years. The long term trend of the yearly margin seems to be quite stable at an average 7.6%.
As a sidenote, Soteb and Geral in my opinion a quite synergic, as I suspect that when Soteb wins a contract to open or extend a factory, the custom made Geral product can be a good way to provide an integrated solution made in GERAL facility at Le Mans.
Energie
This segment is composed of Ardatem and Technisonic. Ardatem was founded in 1987 and was acquired by GP in 2006. As shown below, Ardatem offices are spread all over France and in Bristol UK, likely located closed to nuclear facilities of EDF. EDF is the largest customer of GP overall.
Here is a description of Ardatem and Technisonic services

There are involved in almost all electrical aspects of a nuclear reactor including the critical control of valve systems. It is one of the few companies in France certified by EDF for this type of activities.
I have charted sales of the “Energie” segment sales per semester for the last 5 years :
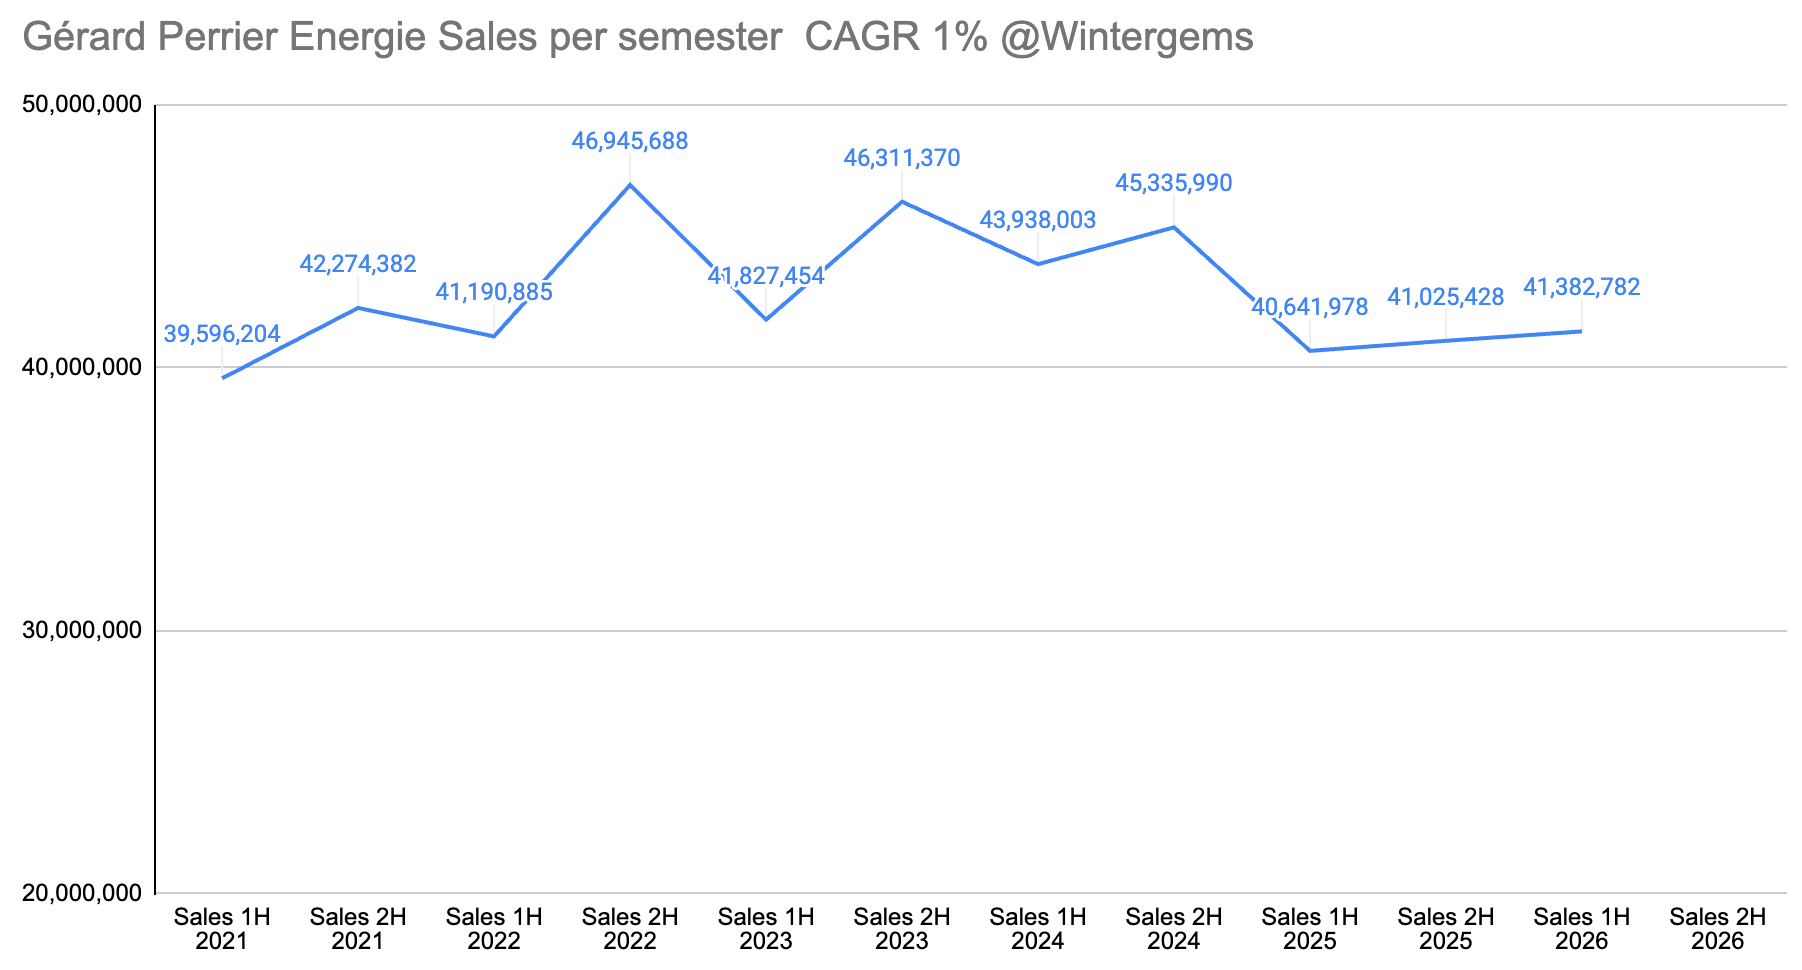
Clearly sales have been stagnant for the past 3 semesters. The company is explaining this by record uptime of the nuclear facilities and thus limited downtime allowing Ardatem to do some maintenance. This is viewed as temporary and maintenance is expected to increase in 2027.
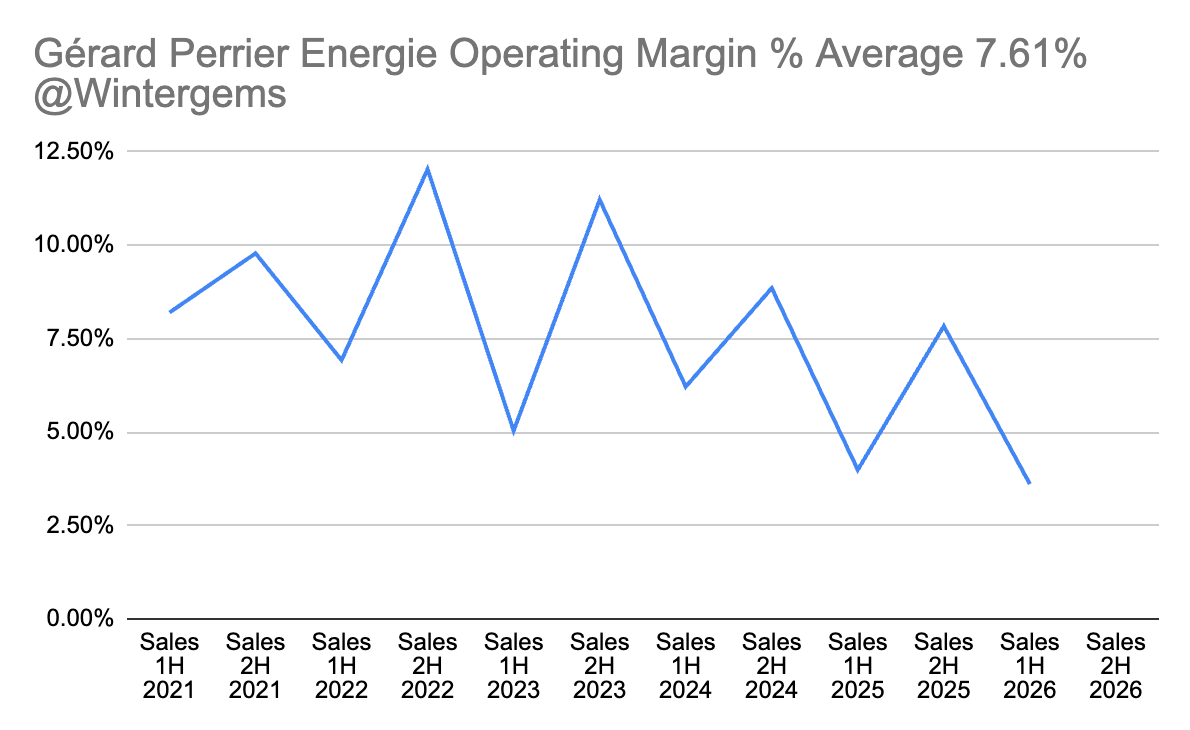
In terms of profitability, this lack of activity has impacted the bottom line as well.
Aeronautique
The Aeronautique segment was created in 2021 following the acquisition of AECE. This is what GP said about AECE in their 2021 annual report
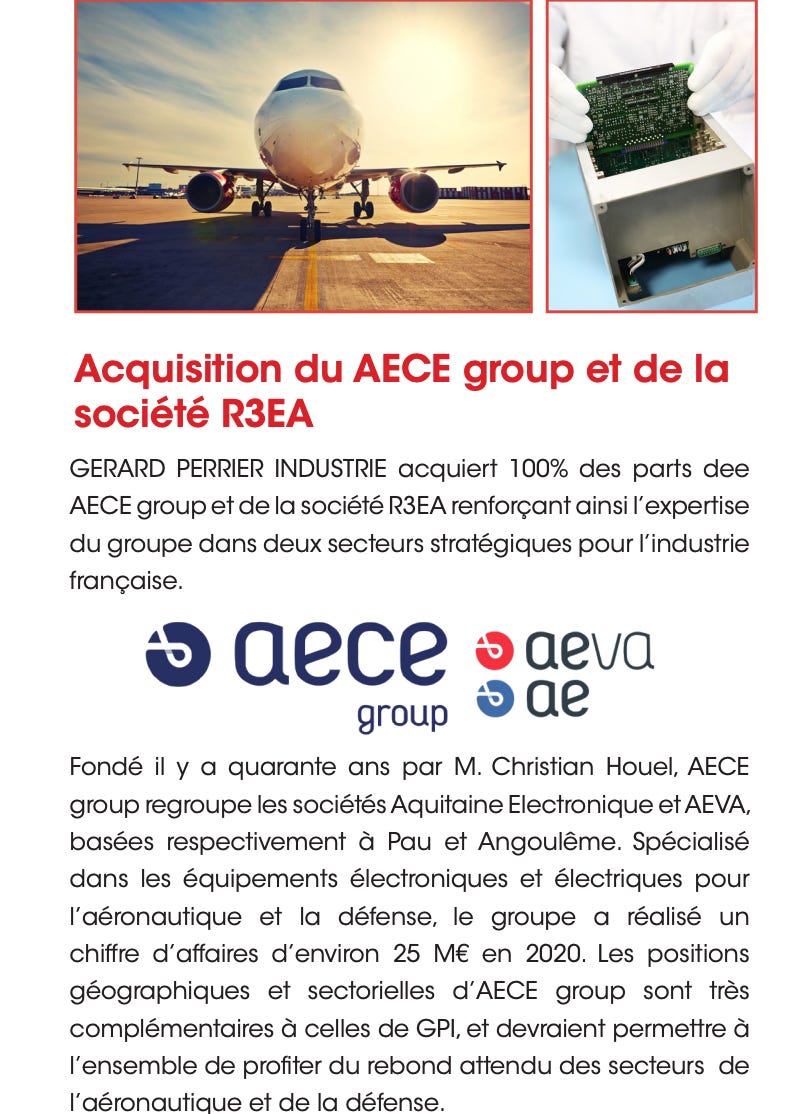
AECE is providing onboard electronic and electric circuit for Aerospace and Defense business with more than 25m Euros in sales in 2020.
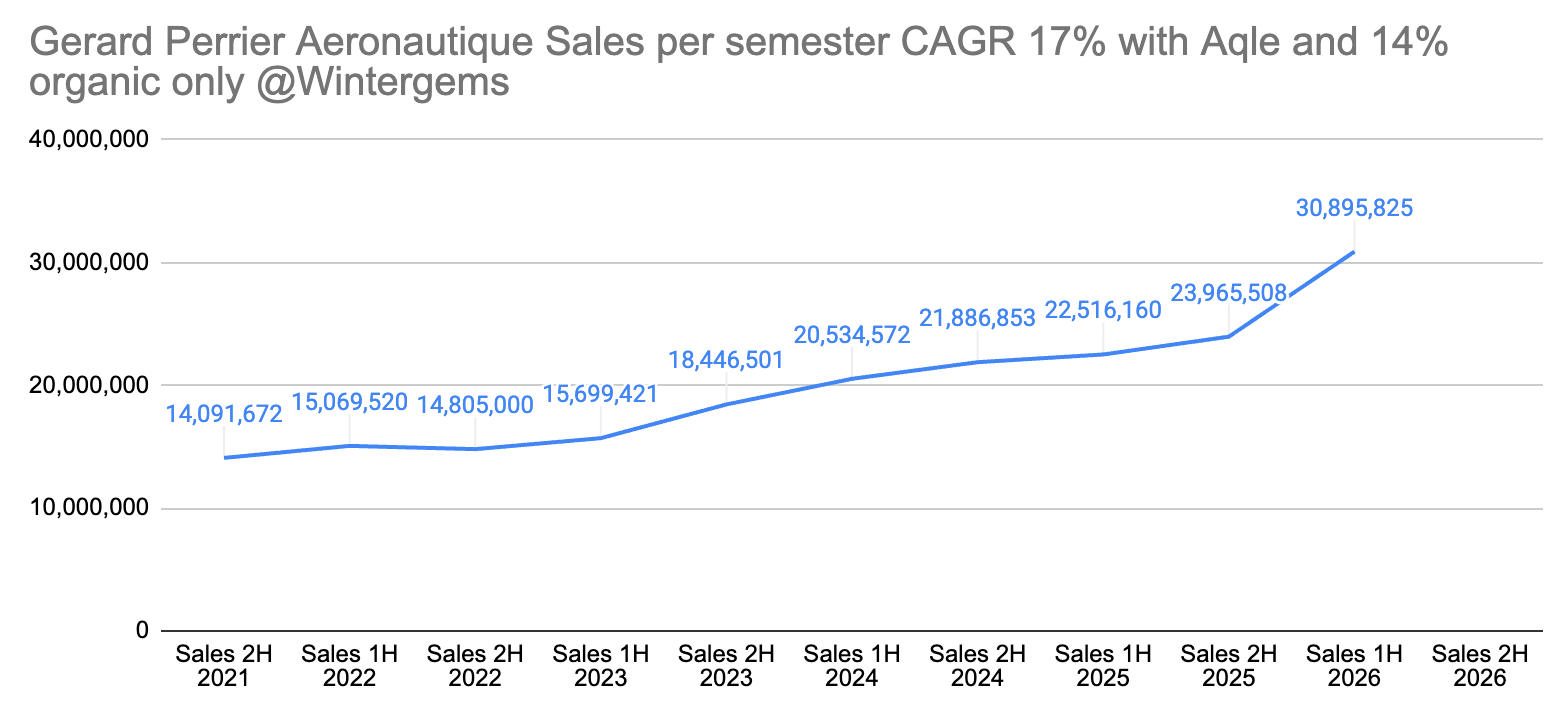
Since then, sales has grown quite rapidly at more than 17% CAGR. Although some of the growth - recent jump in the last quarter - is due to the recent acquisition of Aqle. If we exclude the latest semester and the Aqle impact, the sales growth is closer to 14%.
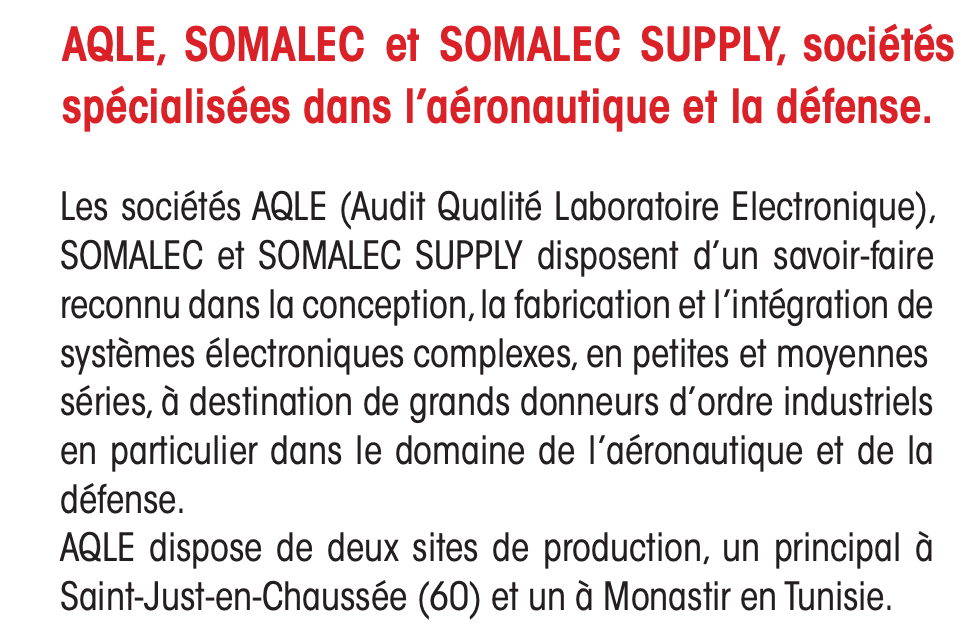
Here is what the company had to see about Aqle in the latest annual report. The company had sales of 12.4m in 2025.
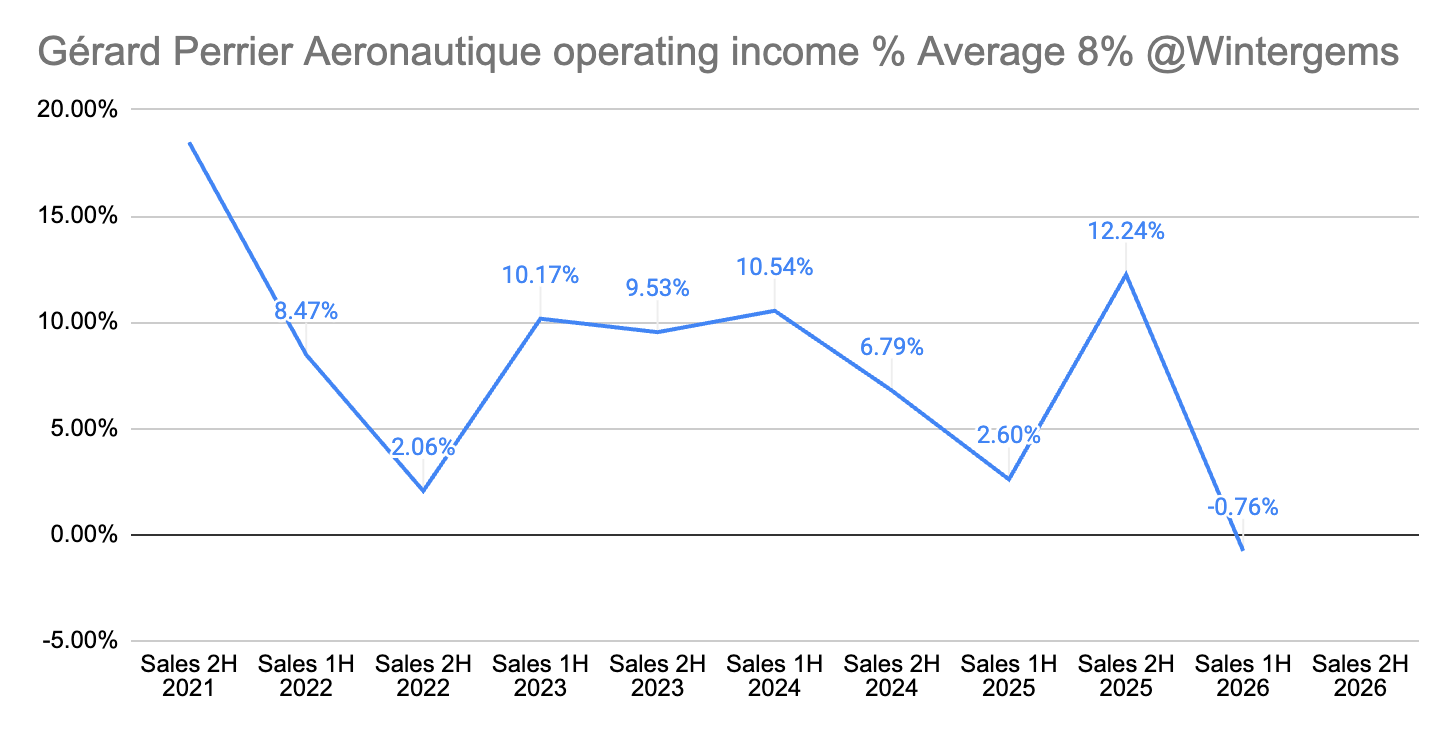
If we look at the operating margin, there is a lot of wide variation from one semester to another. Over the last 10 semester there was 3 large miss, and 4 very good semester reaching 10% and more. This average to about 8%. I think the GP management is not very happy about this situation and they have put some new measures in place to correct the situation. My understanding is that we should expect better results in 2027.
Normalized earnings
As stated earlier, I decided to estimate the normalized earnings of the company by using
The 12 month trailing sales of each segment
The average operating income margin of each segment of the last 5 years.
Using this method we get an operating income of 29.6m euros
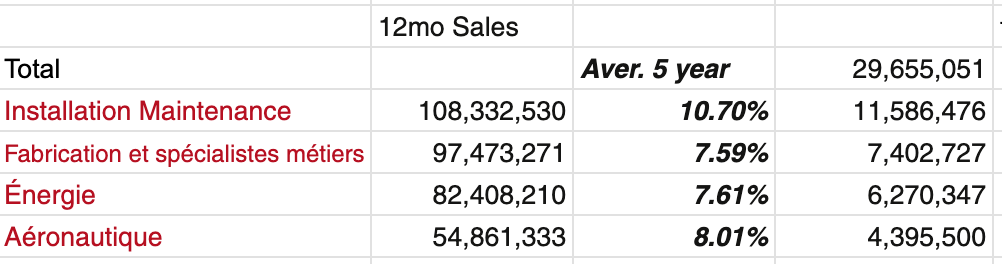
which would result in a EPS of 5.89 or 12.30 PE or 10.78 per share excluding net cash of 9Euro per share.

Now current trailing 12mo EPS is 4.92 EPS, or 14.75 PE.
This is a good entry for a patient investor.
Did I say that the company has no debt and has net cash balance of around 9euros per share?
As we dont need to assume any growth here, just normalization of margin and EPS should improve by 20%.
Now we have seen that 2 segments have seen its sales growing at more than 10% CAGR (Installation and Aeronautique) and Fabrication is also growing steadily. The company is benefiting from the continued robust electrification trend and aeronautic and Defense boom in France (Safran, Thales are major customers) . So you have a nice compounder here. A French Champion like Memyselfandi007 would state in 2013.
I have not done elaborate projections in terms of expected sales on a segment basis and so on over the next 3 years. I just dont need to.
Cheers,
Oh.. and I put on pause my X account again so here is the only way to reach me and my preference would be using the comments below.
No text here was generated by LLM so all hallucinations or errors are solely due to the author.
Legal Disclaimer: All content published on Wintergems is intended for informational and entertainment purposes only. It is not intended to serve as a recommendation to buy or sell any security. The views expressed are my own and are subject to change without notice. The information provided here is proprietary. I make no representations or warranties as to the accuracy or completeness of the information provided and will not be liable for any losses, injuries, or damages from the display or use of this information. Readers are solely responsible for their own investment decisions.
Gerard Perrier has lost contracts in the Energy Division in recent years, as EDF has brought in-house some of the activities it previously outsourced to GP. There is hope that EDF will return to a generally slightly higher volume of contracts in 2027 and 2028, but this is by no means certain. In my view, the cash position shown on the balance sheet is not freely available either, as major clients in system-critical sectors only award contracts if the contractor is financially sound. Furthermore, GP is relatively weak when it comes to communicating with the capital market regarding investor updates.