

Last week, LVMH reported Q3 sales and I took the opportunity to update my model of their Champagne and Cognac sales. It is been also one year since my post “ Spirits Landslide and Champagne Supernova”. Let me also be clear that the materials below only applies to the Moet Hennessy (MC) part of the LVMH and as such is a small part of this holding now. So it should certainly not be viewed as a big positive for LVMH. But still it indicates that this part of the business is getting under control, stabilizing and growing.
No text below was generated by LLM so all hallucinations or errors are solely due to the author.
Legal Disclaimer: All content published on Wintergems is intended for informational and entertainment purposes only. It is not intended to serve as a recommendation to buy or sell any security. The views expressed are my own and are subject to change without notice. The information provided here is proprietary. I make no representations or warranties as to the accuracy or completeness of the information provided and will not be liable for any losses, injuries, or damages from the display or use of this information. Readers are solely responsible for their own investment decisions.
One thing also to consider as well, is that the current French crisis has limited impact to 90% exporter company like LVMH. The whole French crisis is actually creating some weakness to the Euros which should provide a currency tailwind to exporters like LVMH.
Also as a disclosure I did take a small position around 380euros on LVMH before the results came out. However I am re-allocating most of my investment in French small caps with no debt while small cap French funds are offloading “délester” aggressively out of French companies. I do not need to report quarterly performance to anyone on Earth in contrast to these funds… and will never do so to Wintergems readers. The long game is the only one I am playing. I do not have to wait out the presidential election.
Champagne Supernova
LVMH is the largest player in the Champagne market, but it is not dominant like Hennessy - Moet-Chandon sales represents 10-15% of the overall market. Still it is 10x larger than Laurent Perrier for example. They also have the first and second largest brands in terms of sales with Moet-Chandon and Veuve Clicqot and the most prestigious brands with Dom Pérignon and Kuig.
I initially captured the sales of LVMH Champagne on a quarterly basis but was not able to get the data before 2021. Also large fluctuations per quarter makes it very difficult to capture a long term trend.
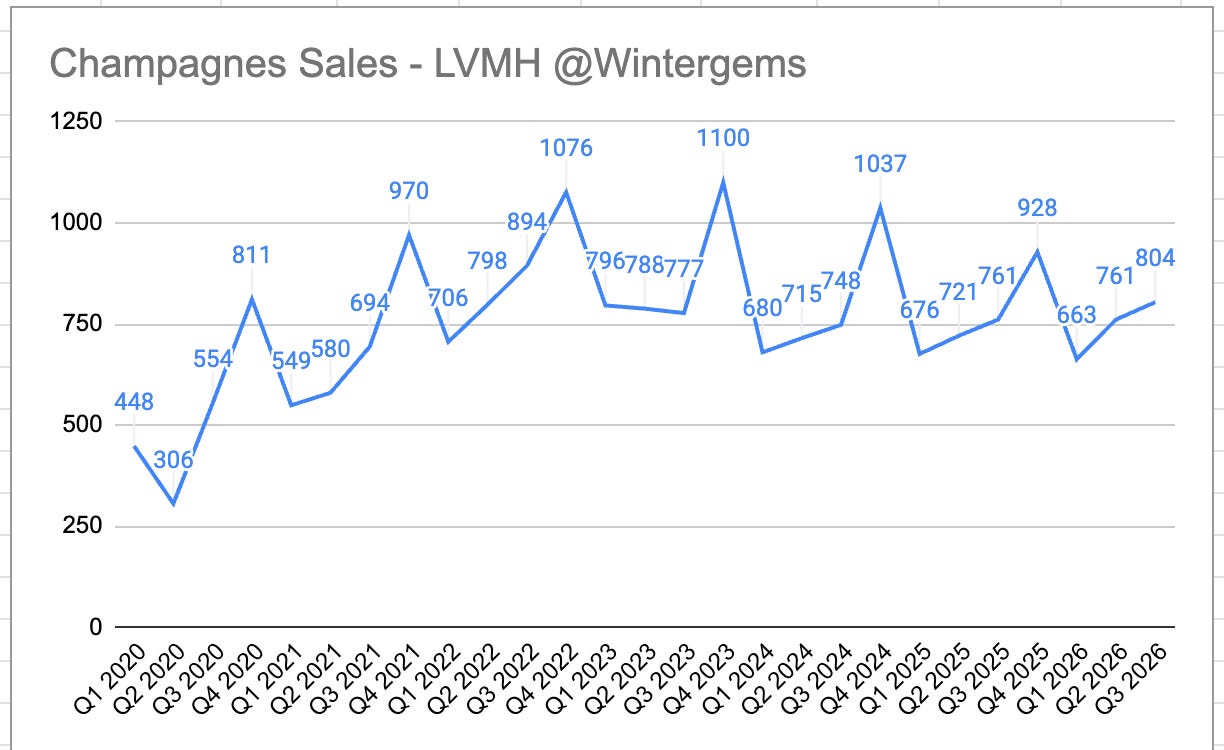
We do see that the latest two quarters, top line has risen YoY and if you normalize for Euro headwind, Champagne sales had actually increase organically in Q3 2025, breaking the downtrend since Q1 2024.
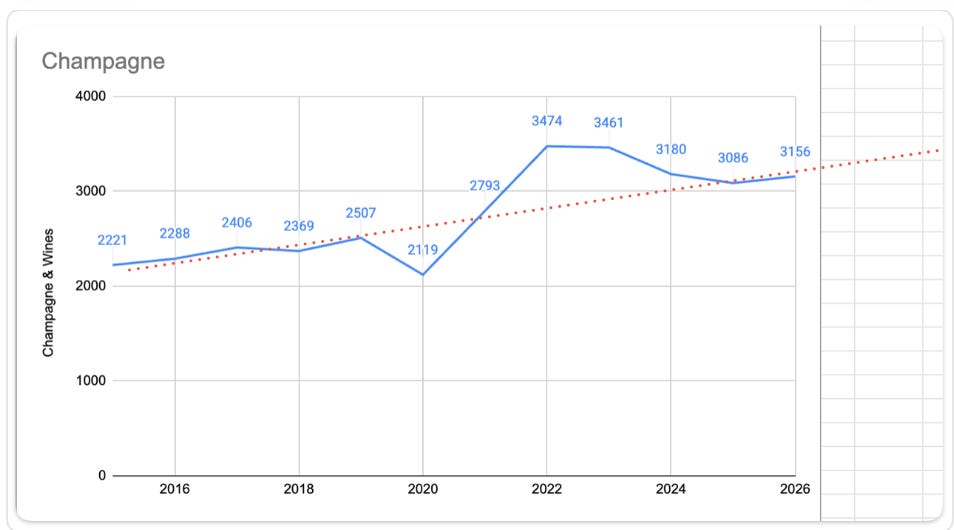
If you look at the annual sales from 2015, you can spot an linear upward trend from 2015 to 2026 with a COVID discontinuity. Please note that I used the 12mo TTM for 2026 so we should expect slightly higher numbers for 2026 if the current trend continues. It is interesting to note that LMVH sales has increased by 42% since 2015 or 3.6% CAGR.
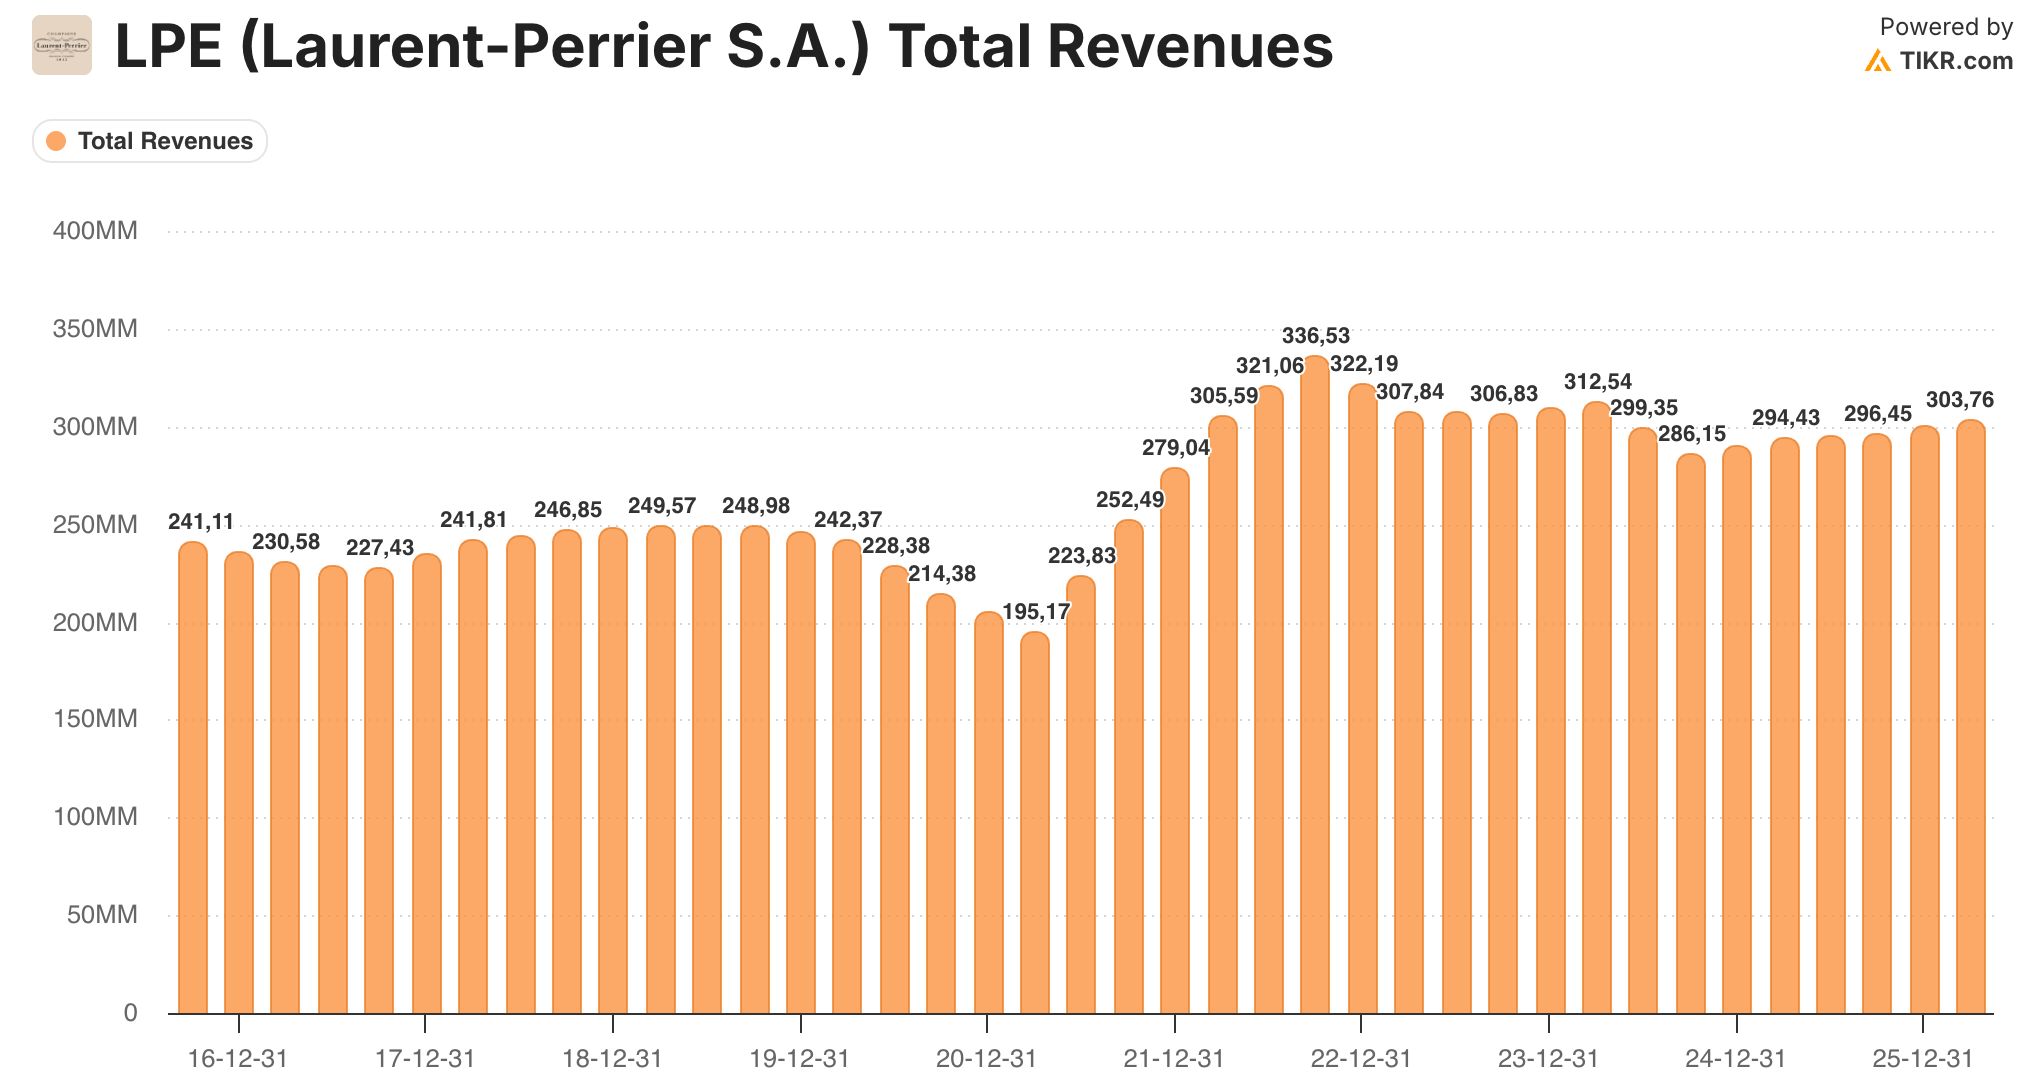
We can also look at other players in the industry. Laurent Perrier sales has seen a similar trend, although at a smaller rate for the same period. Sales did not rise during the 2016 to 2019 but resume growth to reach 303m rising 25% over the period.
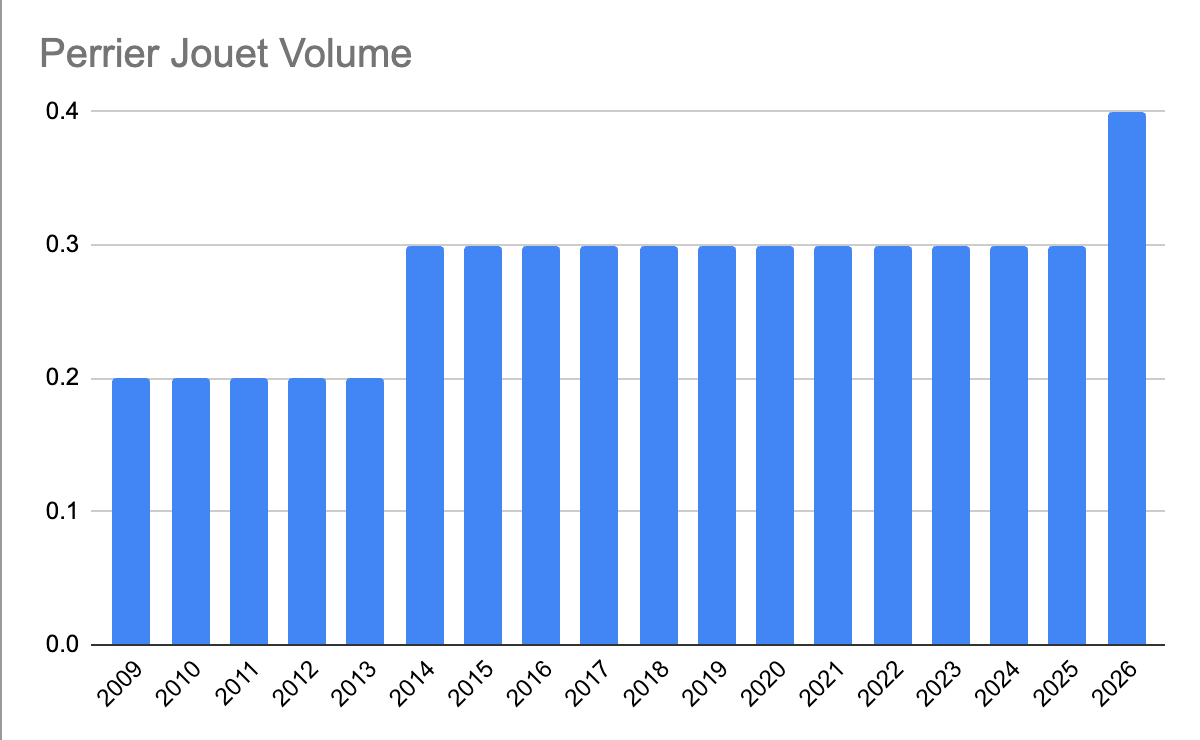
If you look at Pernod Ricard and the Perrier Jouet brand over the same period we get those trends:
The granularity of the volume data does not gives a good idea of what happen every year, but still Perrier Jouet’s volume increase by 33% roughly since 2014, which is in line with the trend seen by LVMH and Laurent Perrier.
So in summary, Champagne is the only alcool in my opinion that has sustained continued growth for the last 12 years. Bourbon and Tequila which was trending positively until 2023-2024 are trending lower and still are. Aperol is popular but for how long?
Cognac Circa 2015
If we do the same exercise for Cognac, we can see that Cognac is also rebounding but from a much lower level. Here are Hennessy quarterly sales bundled with marginal spirits brands. Starting Q3 2022, a severe downtrend on cognac by almost half was felt. Since Q1 2026, sales have stabilized to a certain level. We have seen 2 positive quarters YoY.
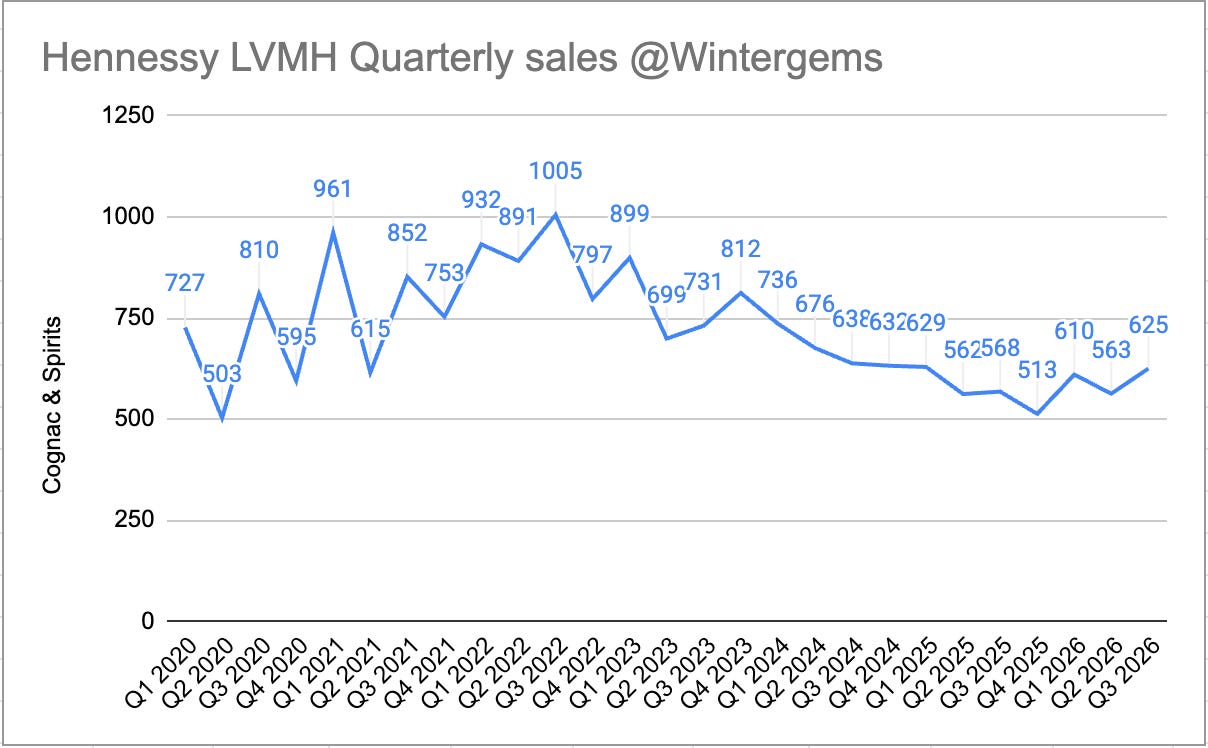
Cognac sales is known for being cyclic and often follow decade long cycle. It peaked in 1985, reached an ultimate low in 1997 to rebound slowly in the 2000s decade.
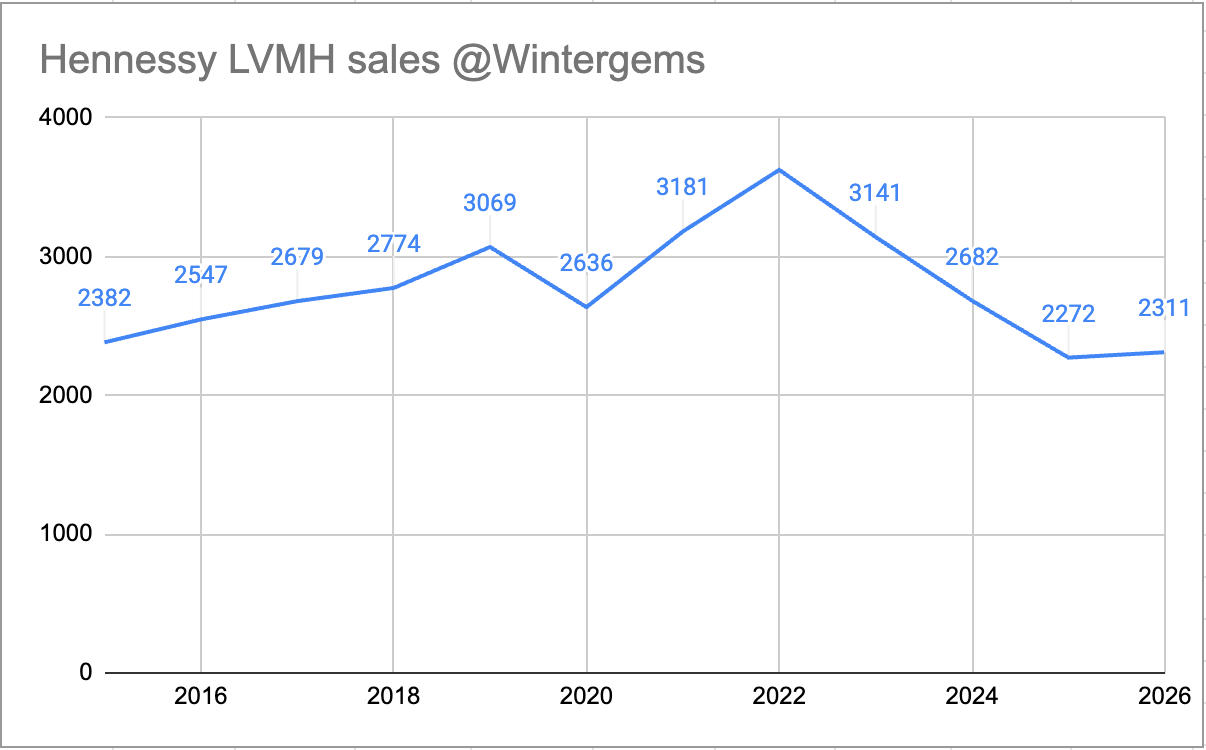
If you look at Hennessy sales for the past 12 years, sales has risen steadily until 2022 by 50% to turn South sharply and is stabilizing to 2015 level. What it will do next is anyone guess but the days of sharp drop in sales YoY seems to be over.
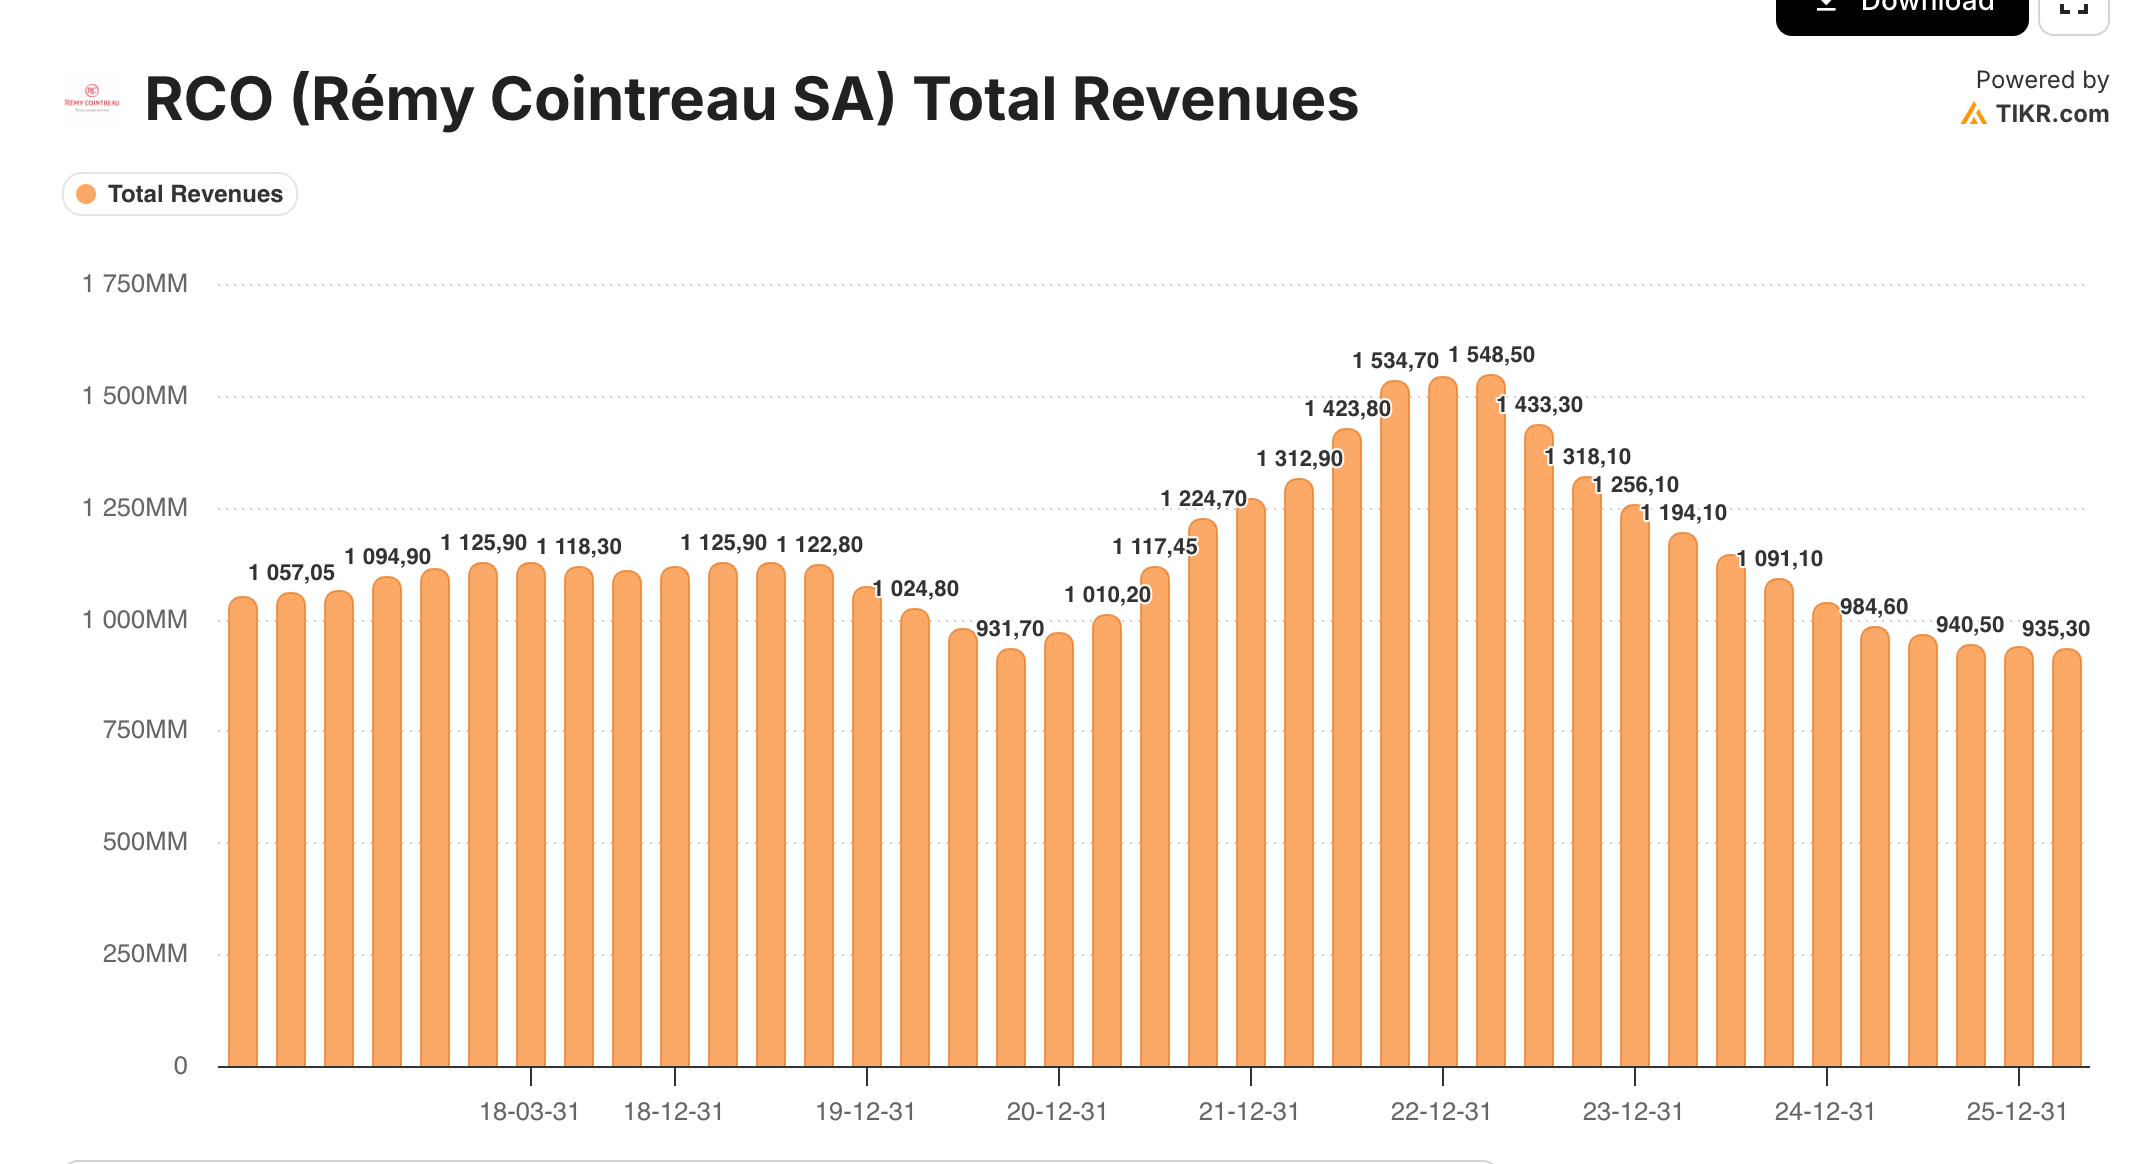
We can look at Remy Martin sales to verify if we get the same pattern. We see a less sharp increase in sales from 2016 to 2019, and sharper growth post COVID and a similar sharp drop to current level. Topline sales has not yet rebounded compared to Hennessy yet but still a similar pattern.
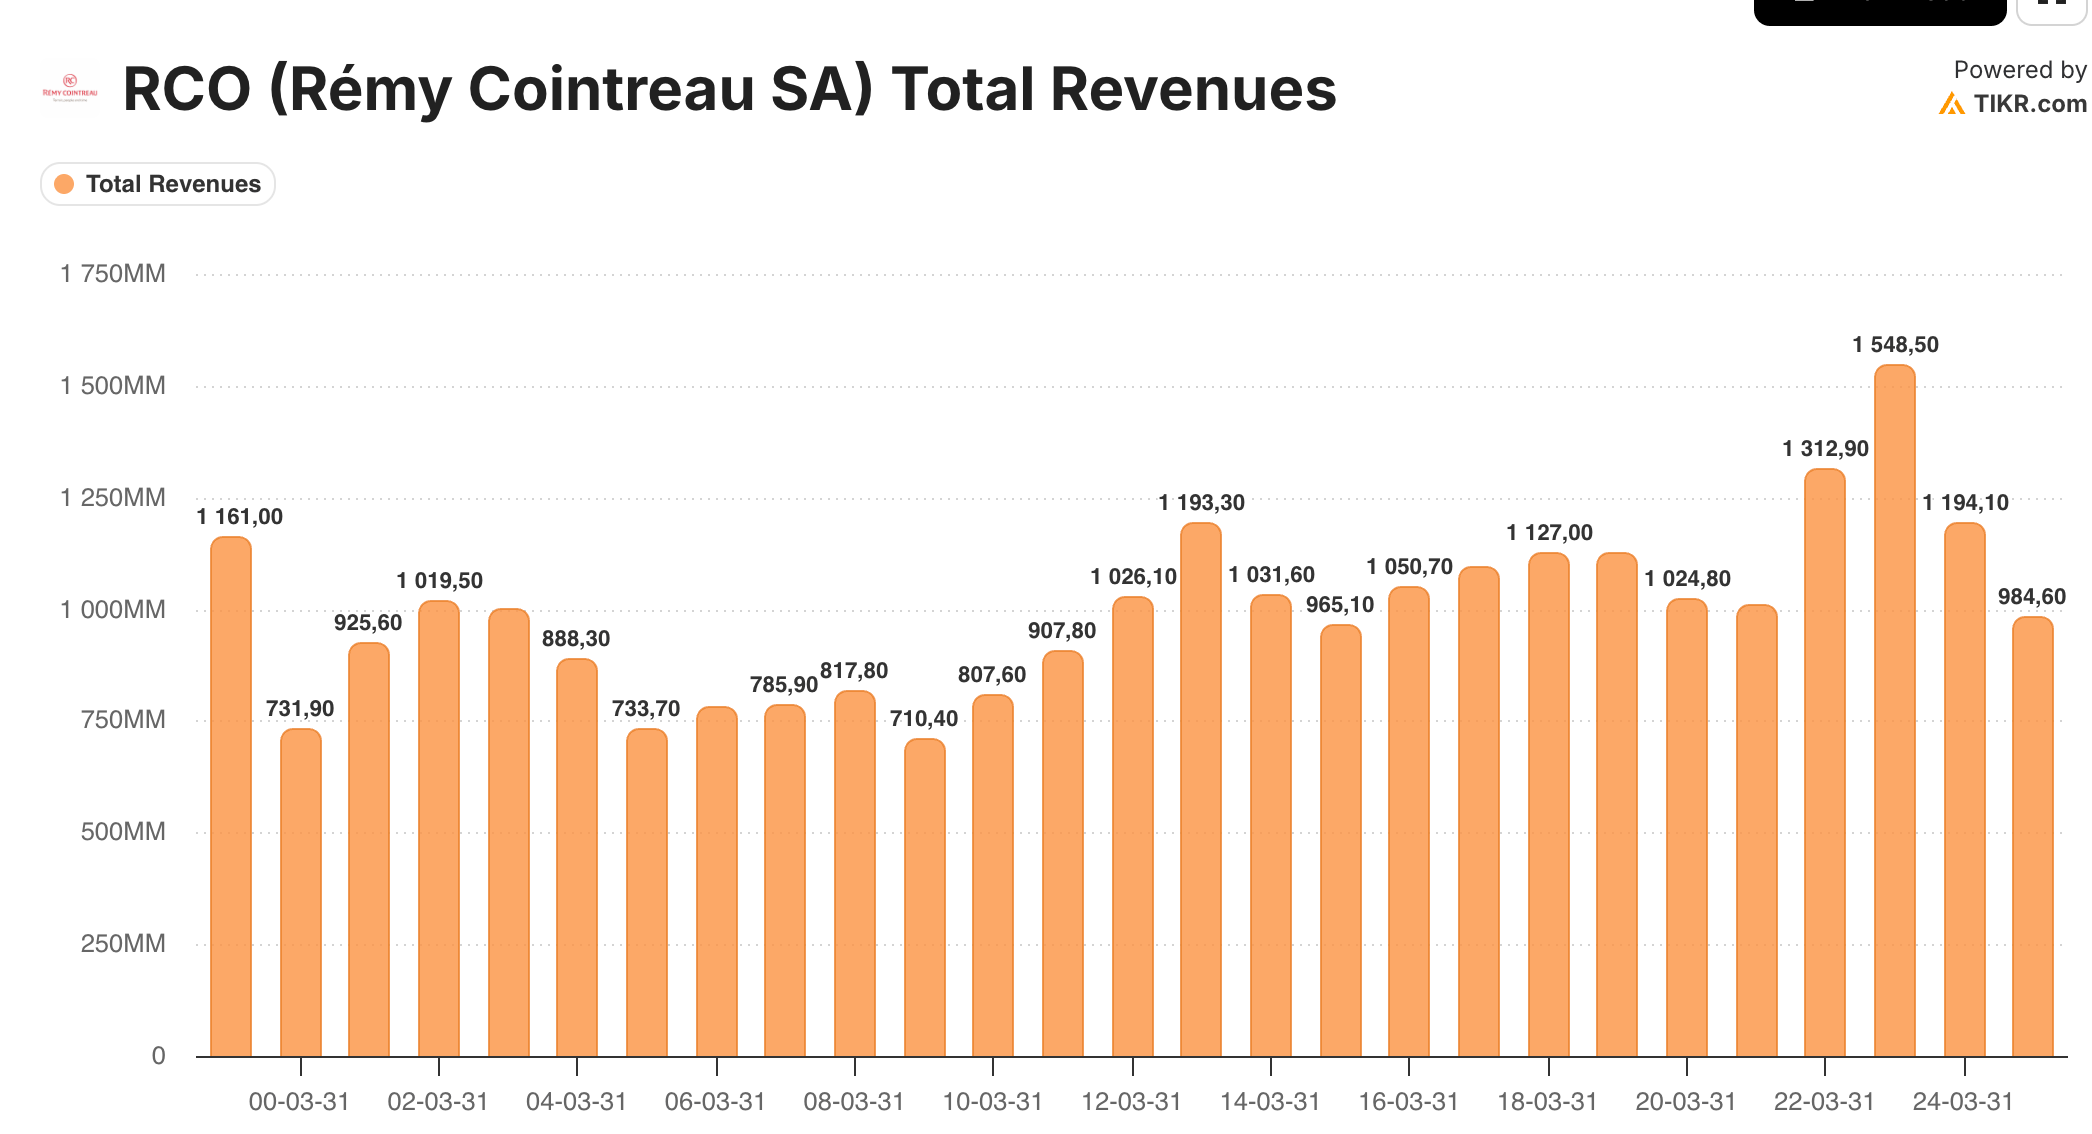
If we go back to 1999, we can clearly see sales of Remy Martin going through some rough cycles. The 2015 sales also corresponds to the current 2026 level. 2015 was actually a down year versus previous years.
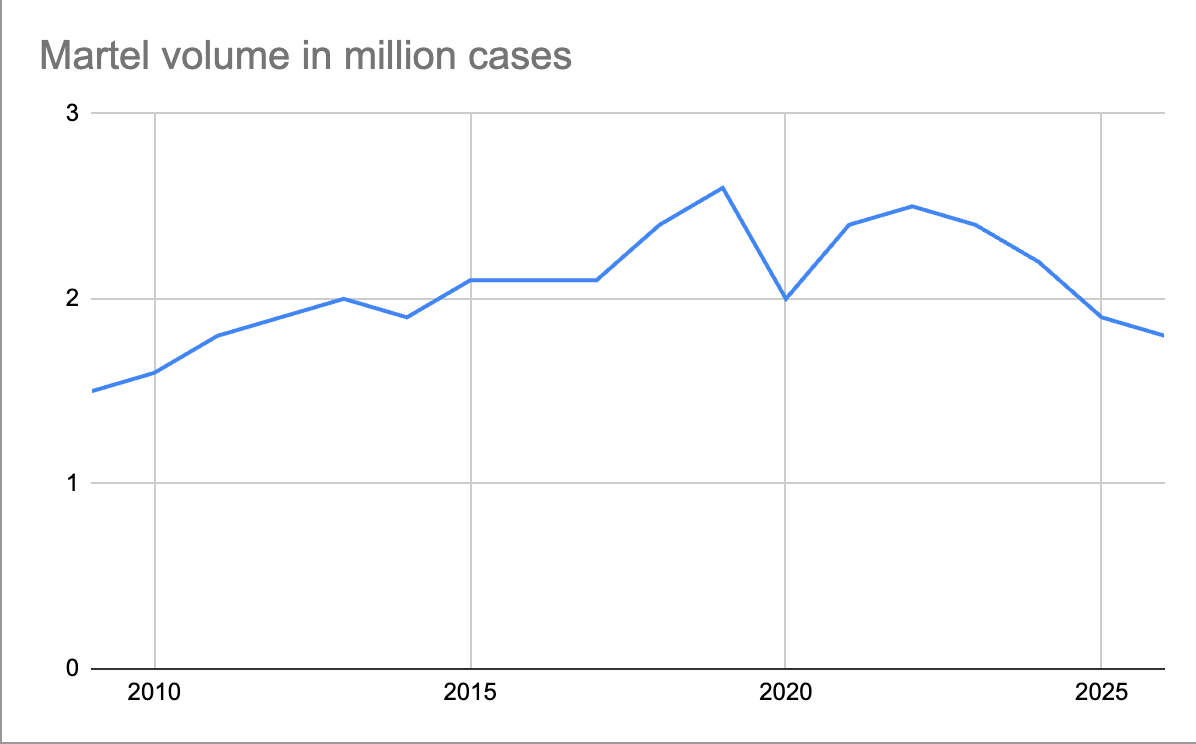
Martell volume sales confirms a similar trend where we have seen a steady rise from 2009 low sales to 2022 with volume rising close to 50% and then a sharp drop to 2015 level in 2026. Martell being more exposed to the China market which is still weak compared to Hennessy - has not rebounded yet. It may take another year before stabilization.
Moet-Hennessy
One conclusion is that both Hennessy and the Moet-Chandon brands are overperforming their broad market in terms of steady growth and rebound speed.
For Moet Hennessy, we should expect stabilization on Hennessy, improved margin and continued sales increase in Champagne with improved margin as well. So that side of LVMH turn from being a very negative segment in the past few years to a positive segment. If we look at the other segments, both Tiffany and Sephora are strong. Perfume is stable. The focus is now to understand the trend on Fashion and Leather segment, the largest segment. This is what we need to figure out next.
Until then
Cheers!
No text below was generated by LLM so all hallucinations or errors are solely due to the author.
Legal Disclaimer: All content published on Wintergems is intended for informational and entertainment purposes only. It is not intended to serve as a recommendation to buy or sell any security. The views expressed are my own and are subject to change without notice. The information provided here is proprietary. I make no representations or warranties as to the accuracy or completeness of the information provided and will not be liable for any losses, injuries, or damages from the display or use of this information. Readers are solely responsible for their own investment decisions.