

As a follow-up to the danger zone post, I have decided to rank 12 holdings in what I believe is the sweet spot zone for GARP stocks, trading at below PE of 20. I have decided to rank those stocks based on valuation as well as earnings quality.
Legal Disclaimer: All content published on Wintergems is intended for informational and entertainment purposes only. It is not intended to serve as a recommendation to buy or sell any security. The views expressed are my own and are subject to change without notice. The information provided here is proprietary. I make no representations or warranties as to the accuracy or completeness of the information provided and will not be liable for any losses, injuries, or damages from the display or use of this information. Readers are solely responsible for their own investment decisions.
Update October 26 2026: I no longer own Eurokai Takeuchi, Robertet, Intuit and SAP. Not necessarily because I dont like those names, but because I decided to concentrate on Gérard Perrier, Thermador and Aeroedge which are facing 20%-40% drawdown from 200ma which are not backed by fundamental.
Forward PE ranking:
The following table ranks the 12 stocks based on the forward earnings for the current year, from the lowest PE to the highers. All companies are trading between 12 and 19 PE. Similar to the magic formula approach but with my own twist, I will rank all companies based on the lowest PE to the highest. Then I will rank the companies based on the earnings quality (Growth, cyclical, short term momentum).

As we see below, Eurokai, Takeuchi, Teikoku and Kimura Kehko are trading at the cheapest PE. Not surprising, all stocks are small cap. The most expansive are Intuit and SAP. Stocks that typically are never trading below a PE of 20. These are good time.
Earnings quality ranking:
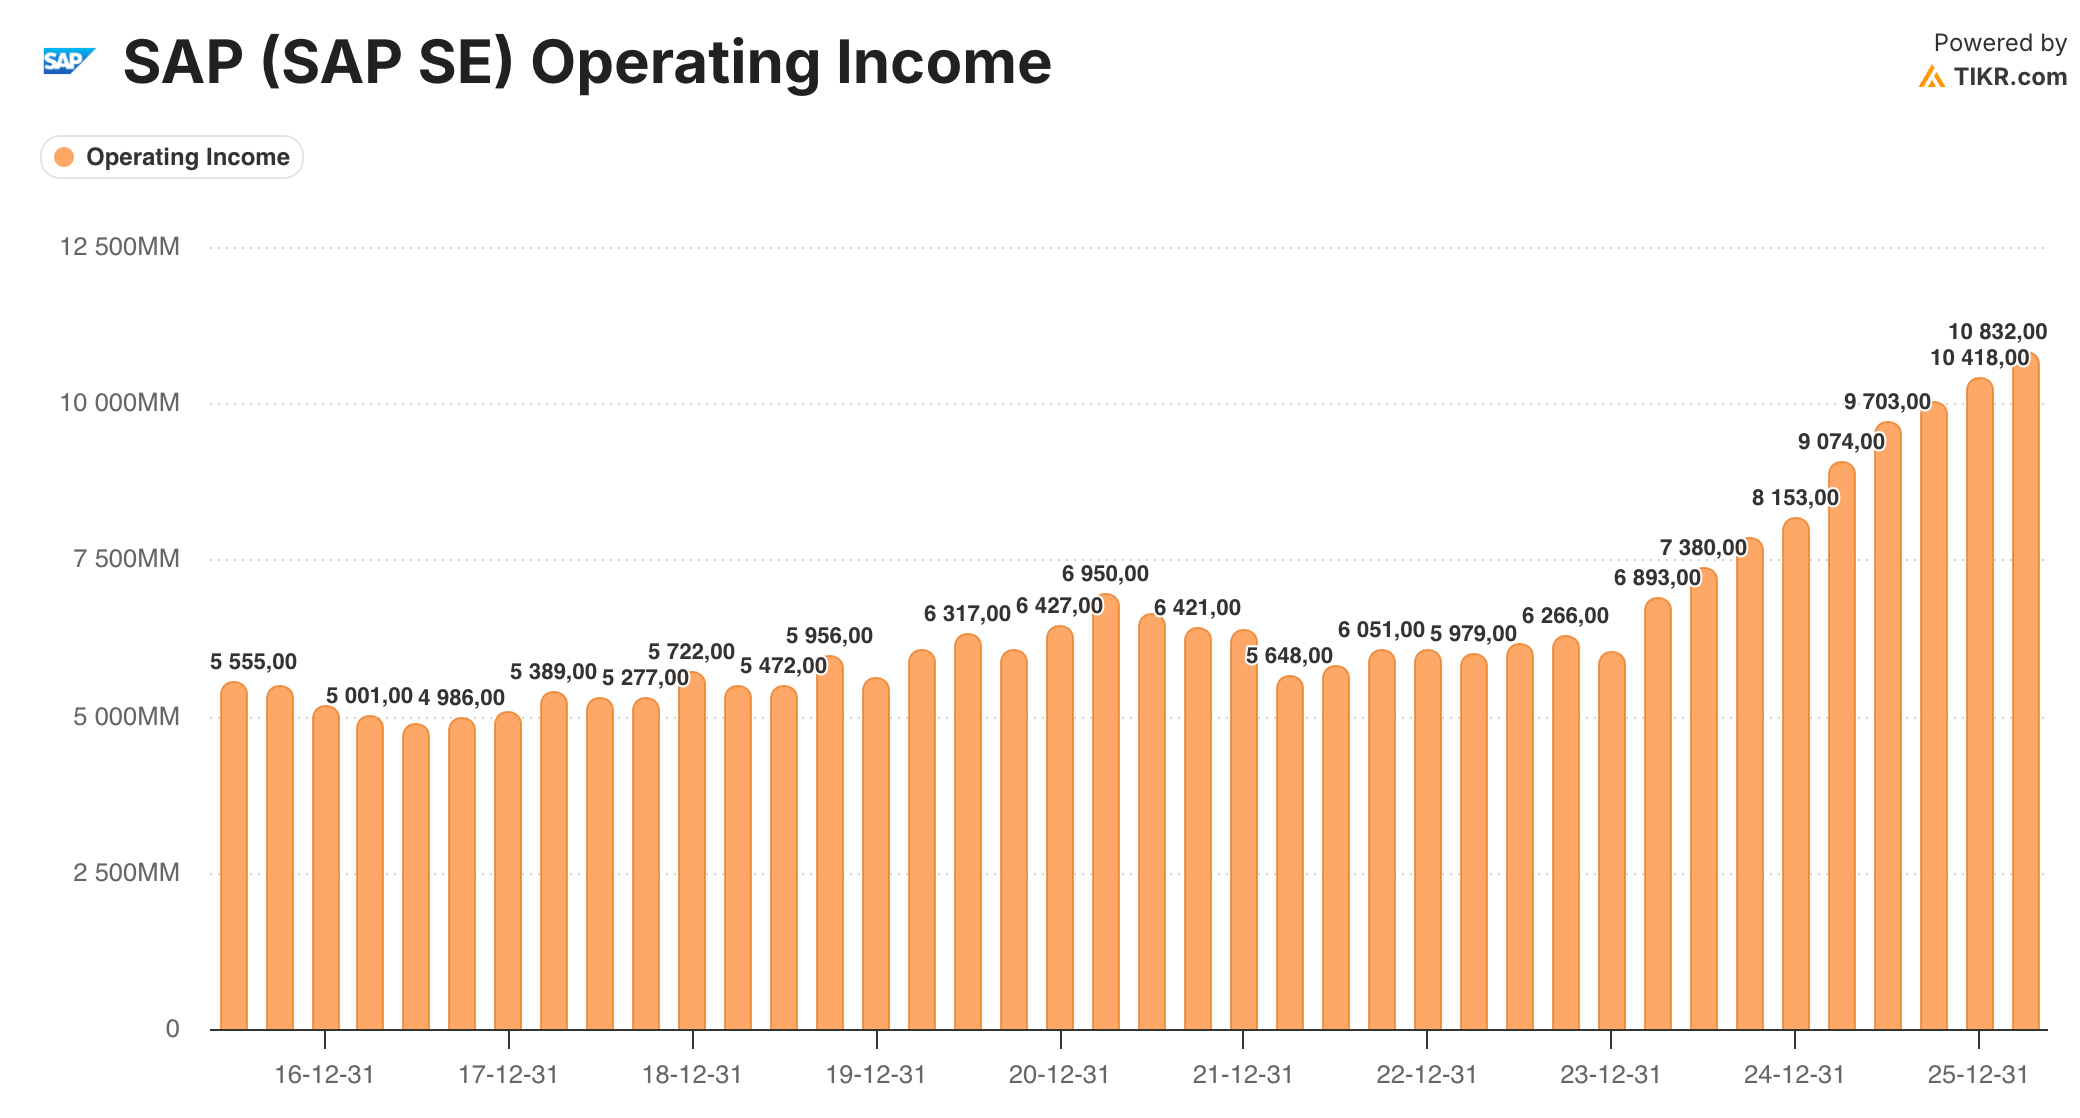
I have then ranked the 12 companies based the earnings quality. My first criteria is growth. I also assign some value on cyclical earnings versus steady earnings. For the same growth I will favor steadiness. I also look at the short term momentum in the near future based on my own understanding of the business. I always favor companies with short term momentum growth for similar growth. A company like SAP with good momentum in growth recently (in operating income) was judged to have superior earnings quality than Thermador (more cyclical) even though Thermador was able to grow EPS more in the last 10 years. This is not exact science…
1. Intuit
Monopoly on accounting for small business and independent workers with QuickBooks and domination of the annual tax report with turbotax in North America (USA and Canada).
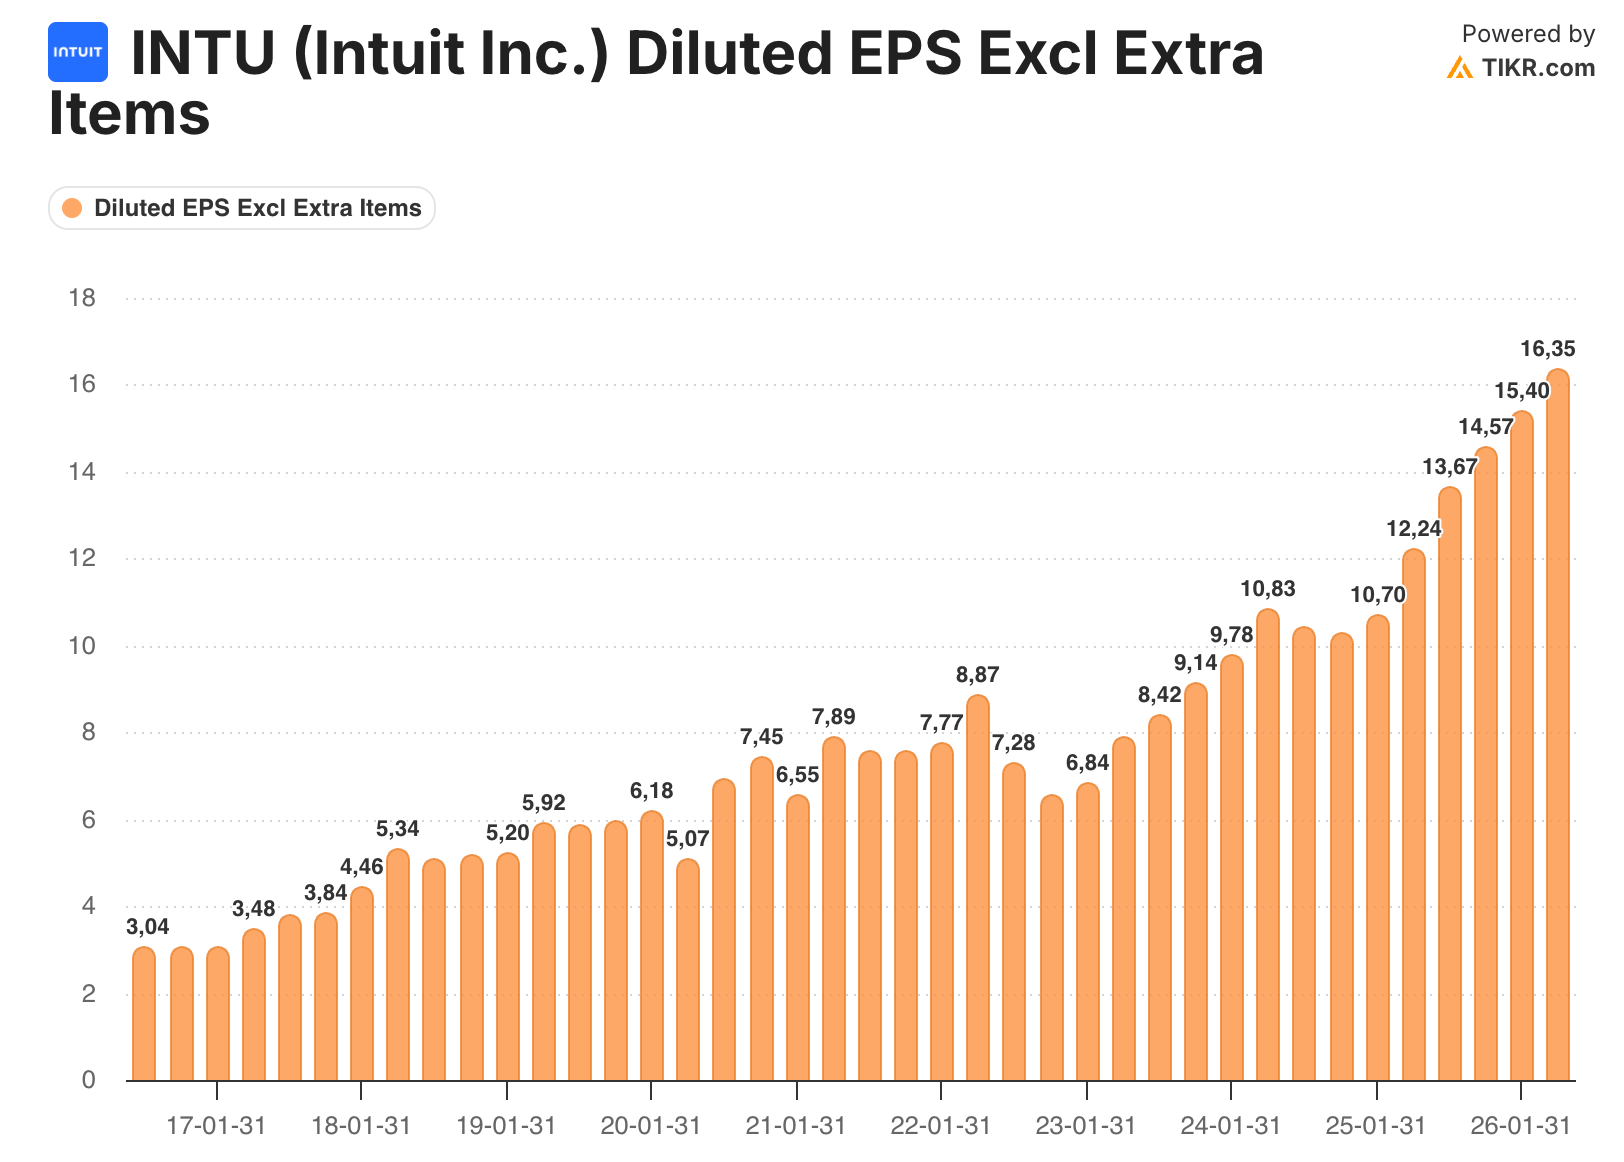
Steady 5x: Intuit had seen an increase in EPS at a 20% CAGR from 2016 to 2020. The EPS raise has accelerated even more since 2023 small drop in EPS. Over a 10 year period, EPS has increase at a 20% CAGR.
2. Kimuka Kohki
Kikuka Kohki makes high-end industrial air conditioning systems for large-scale factories, food processing plants, precision equipment factories, and data centers; commercial air conditioning business includes large retail stores, commercial facilities, and office buildings; and our healthcare air conditioning business includes medical and welfare facilities, schools, libraries, and hotels.
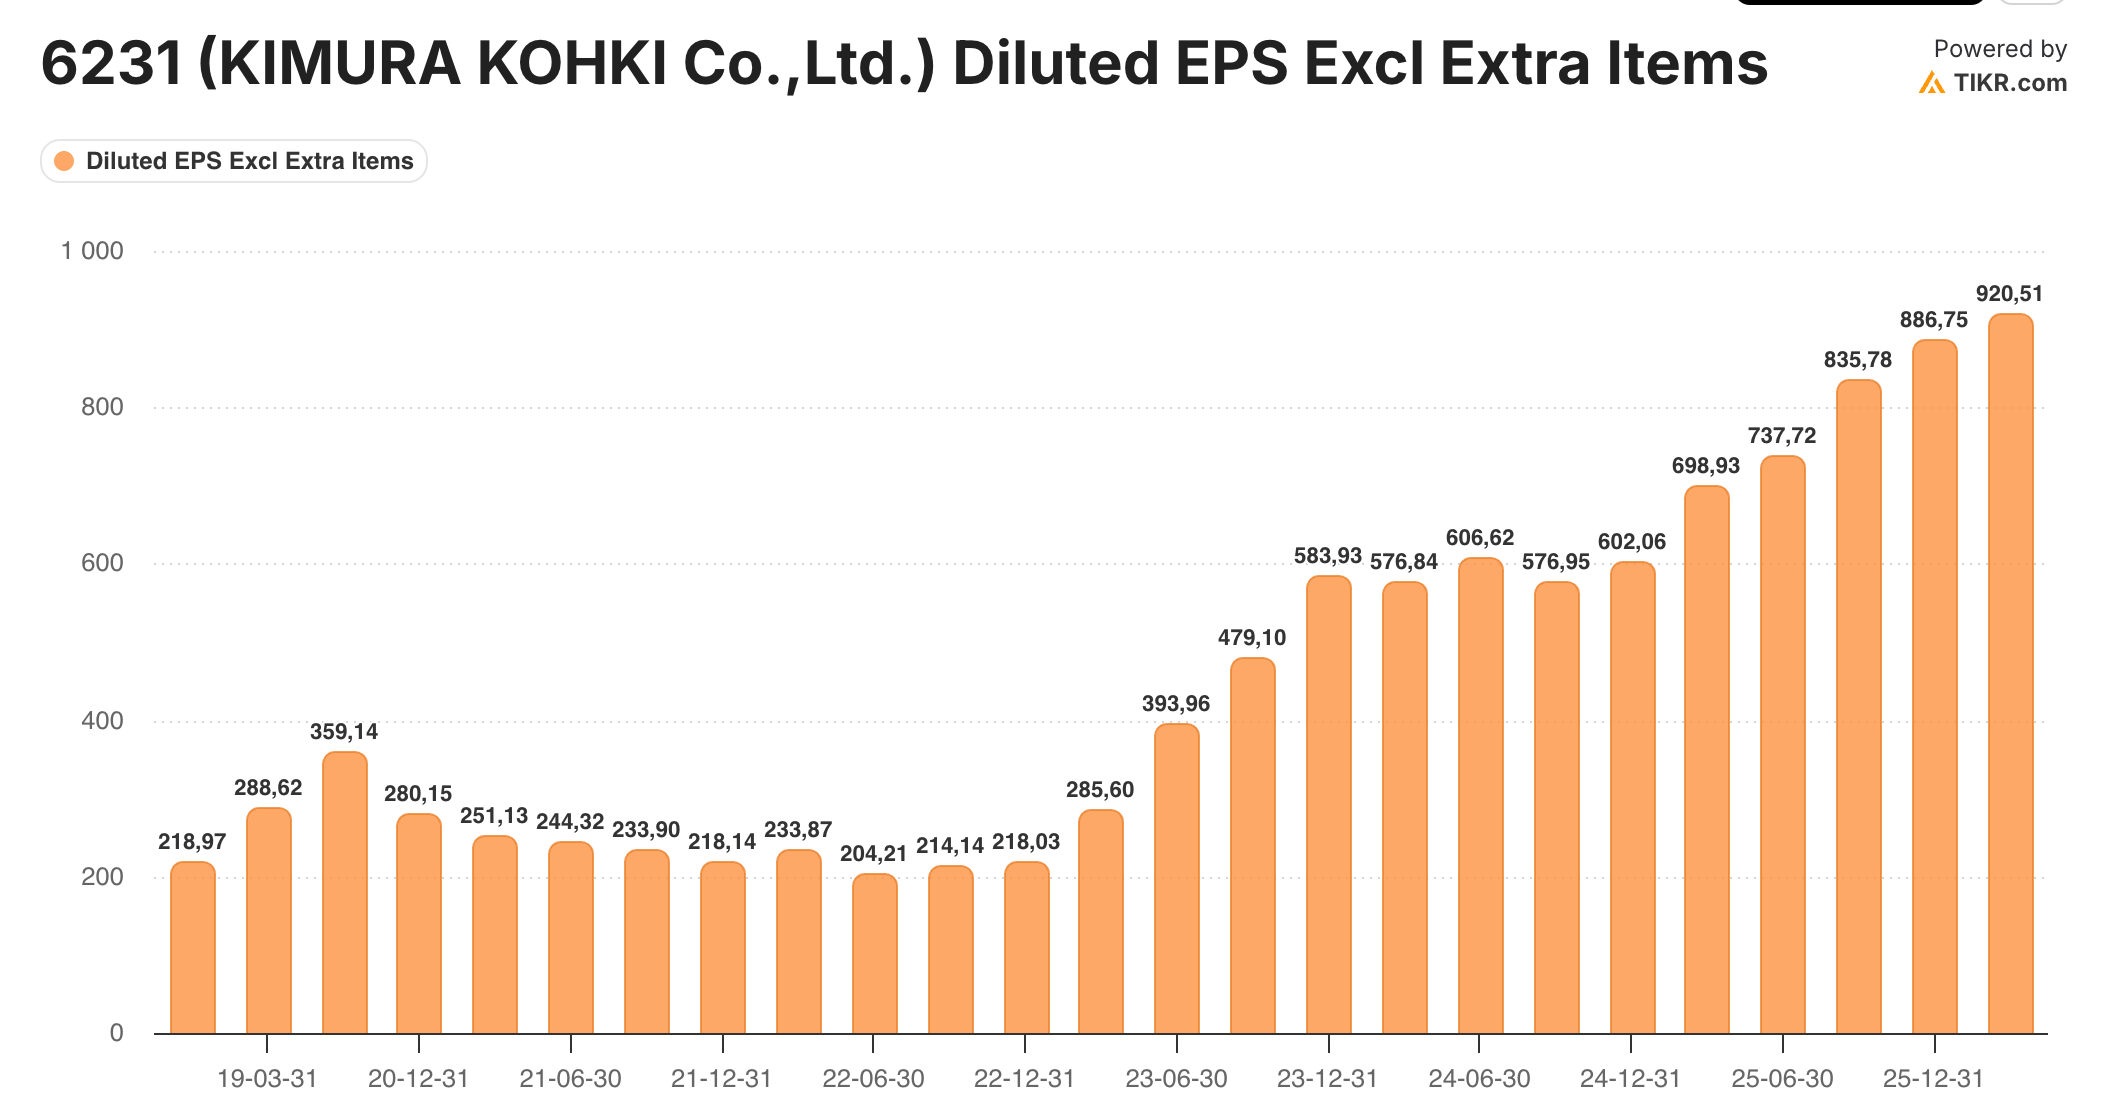
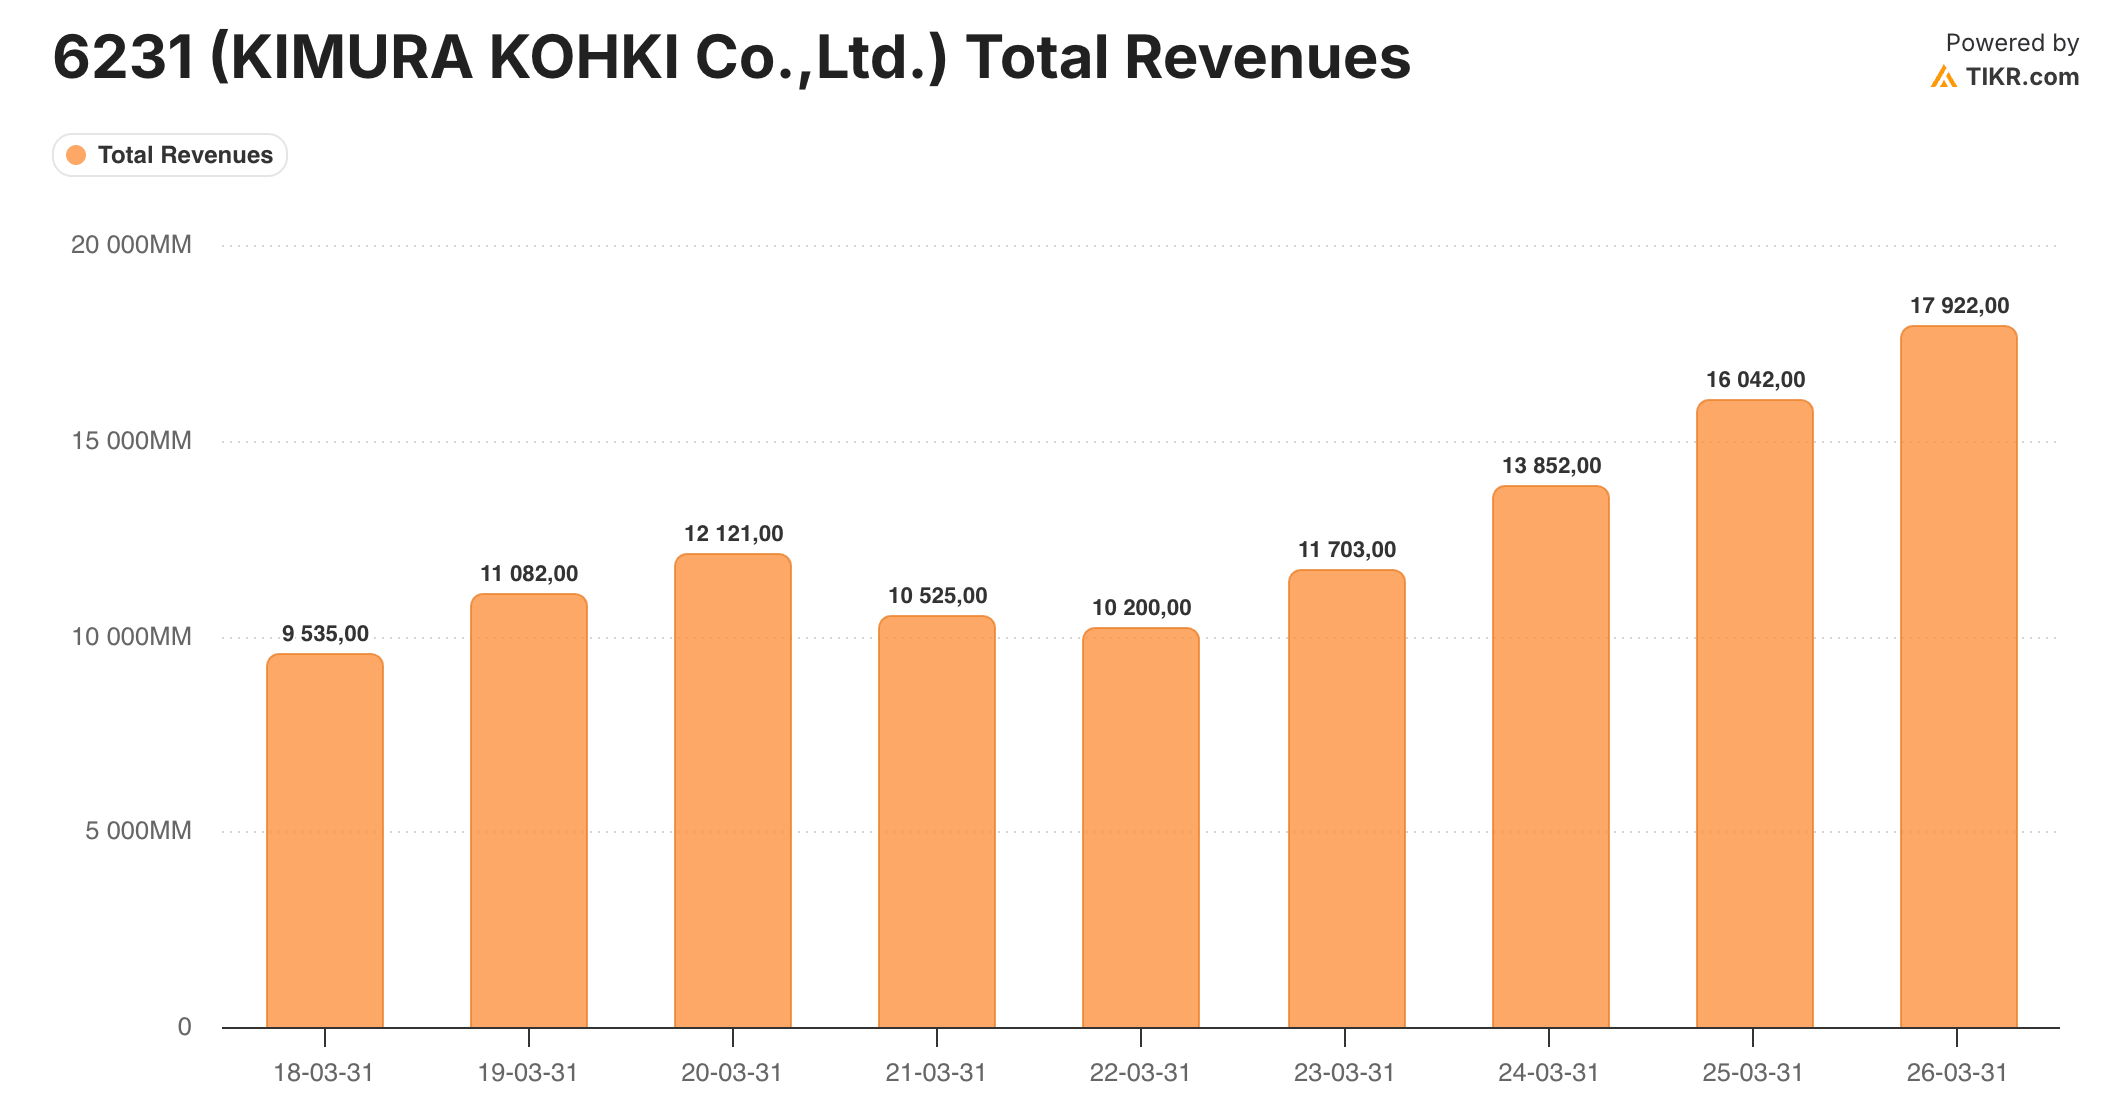
Steady 4x -8 years : Kimura Kohki has quadrupled EPS since 2018. Sales has doubled in 8 years while margin has expanded steadily from 10% operating margin to 25% today.
3. Teikoku
Teikoku is the leading sealless pump manufacturer in the world with 40% market share and 60% market share in Japan.
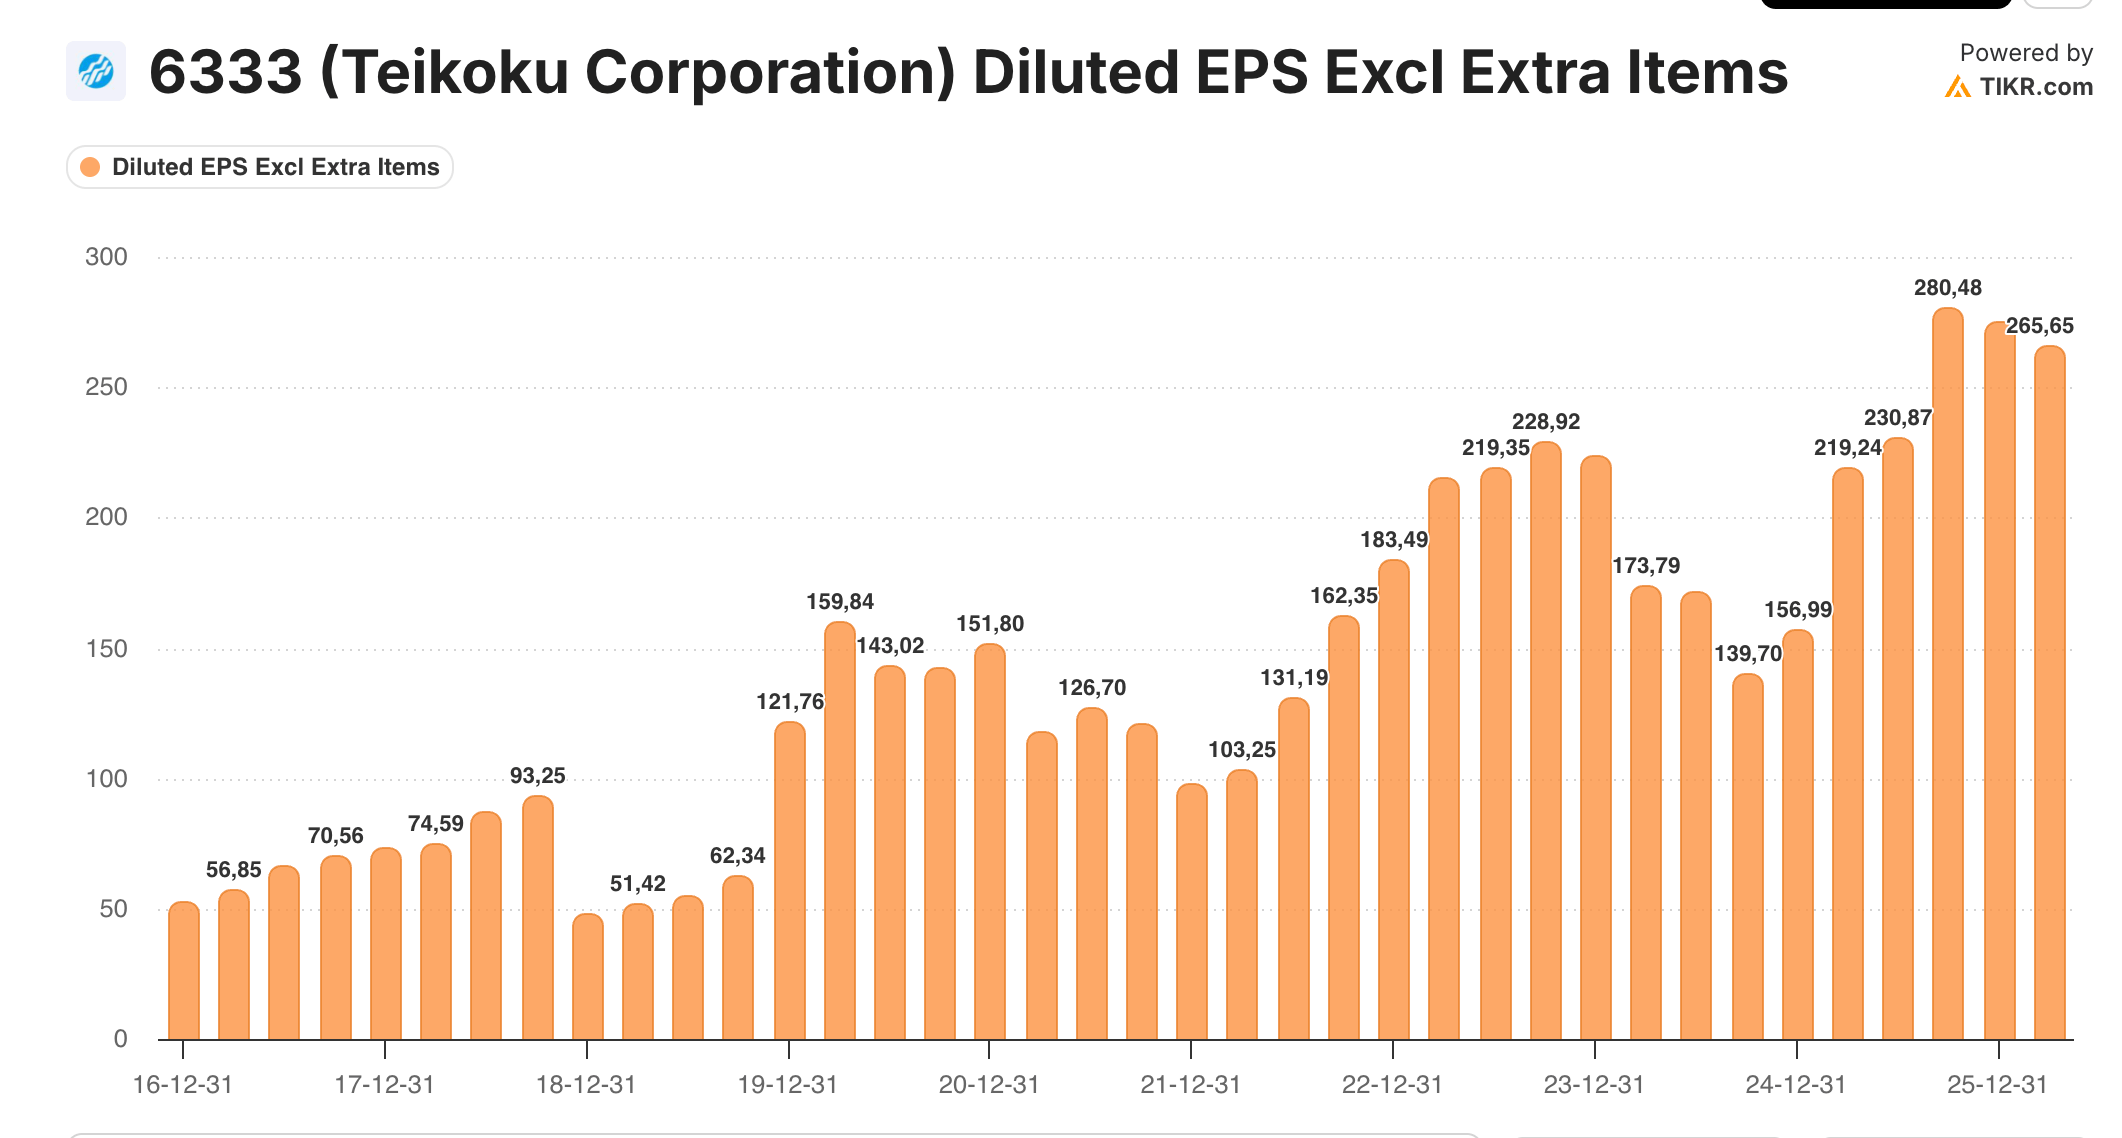
Cyclical 5x: Teikoku’s EPS has risen sharply by 5x over the last 10 years. There is some short term cyclicality with decline in 2018, 2021, 2023. But a straight upward trend can be interpolate clearly over this chart.
4. Okano Valve
Okano valve is the leading valve manufacturer for the Japanese domestic nuclear market with a monopoly for the BWR type.
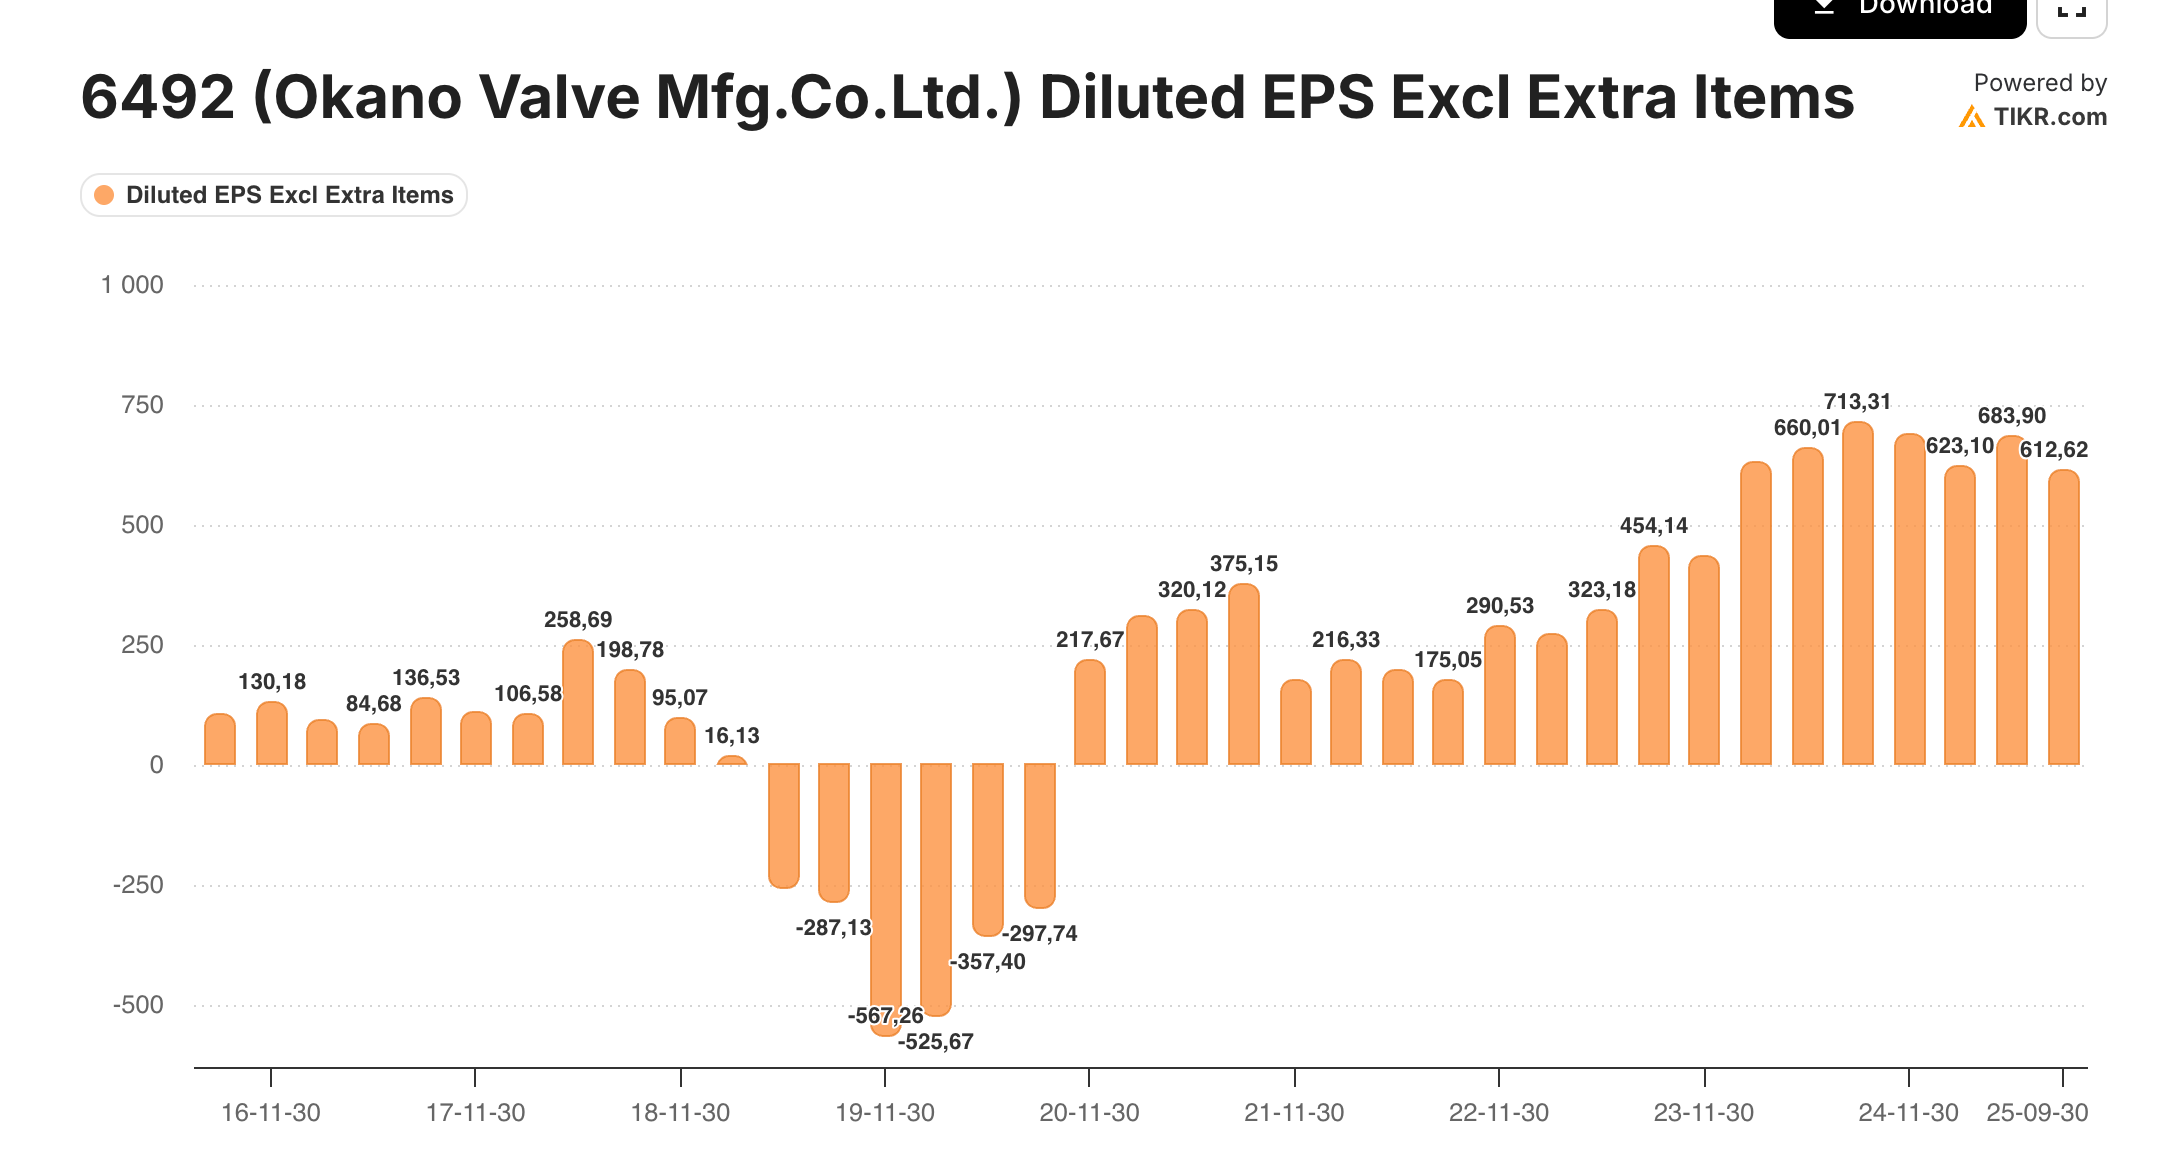
4x Steady since 2021 - strong pipeline ahead . EPS has grown steadily since the preparation work for the BWR nuclear plants restart has started. EPS is expected to reach 872 Yen in fiscal 2026 so almost 4x. The number of restarted BWR plants should double (from 3 to 6) by 2029. This should bring further increase in earnings.
5. Fukui Computer
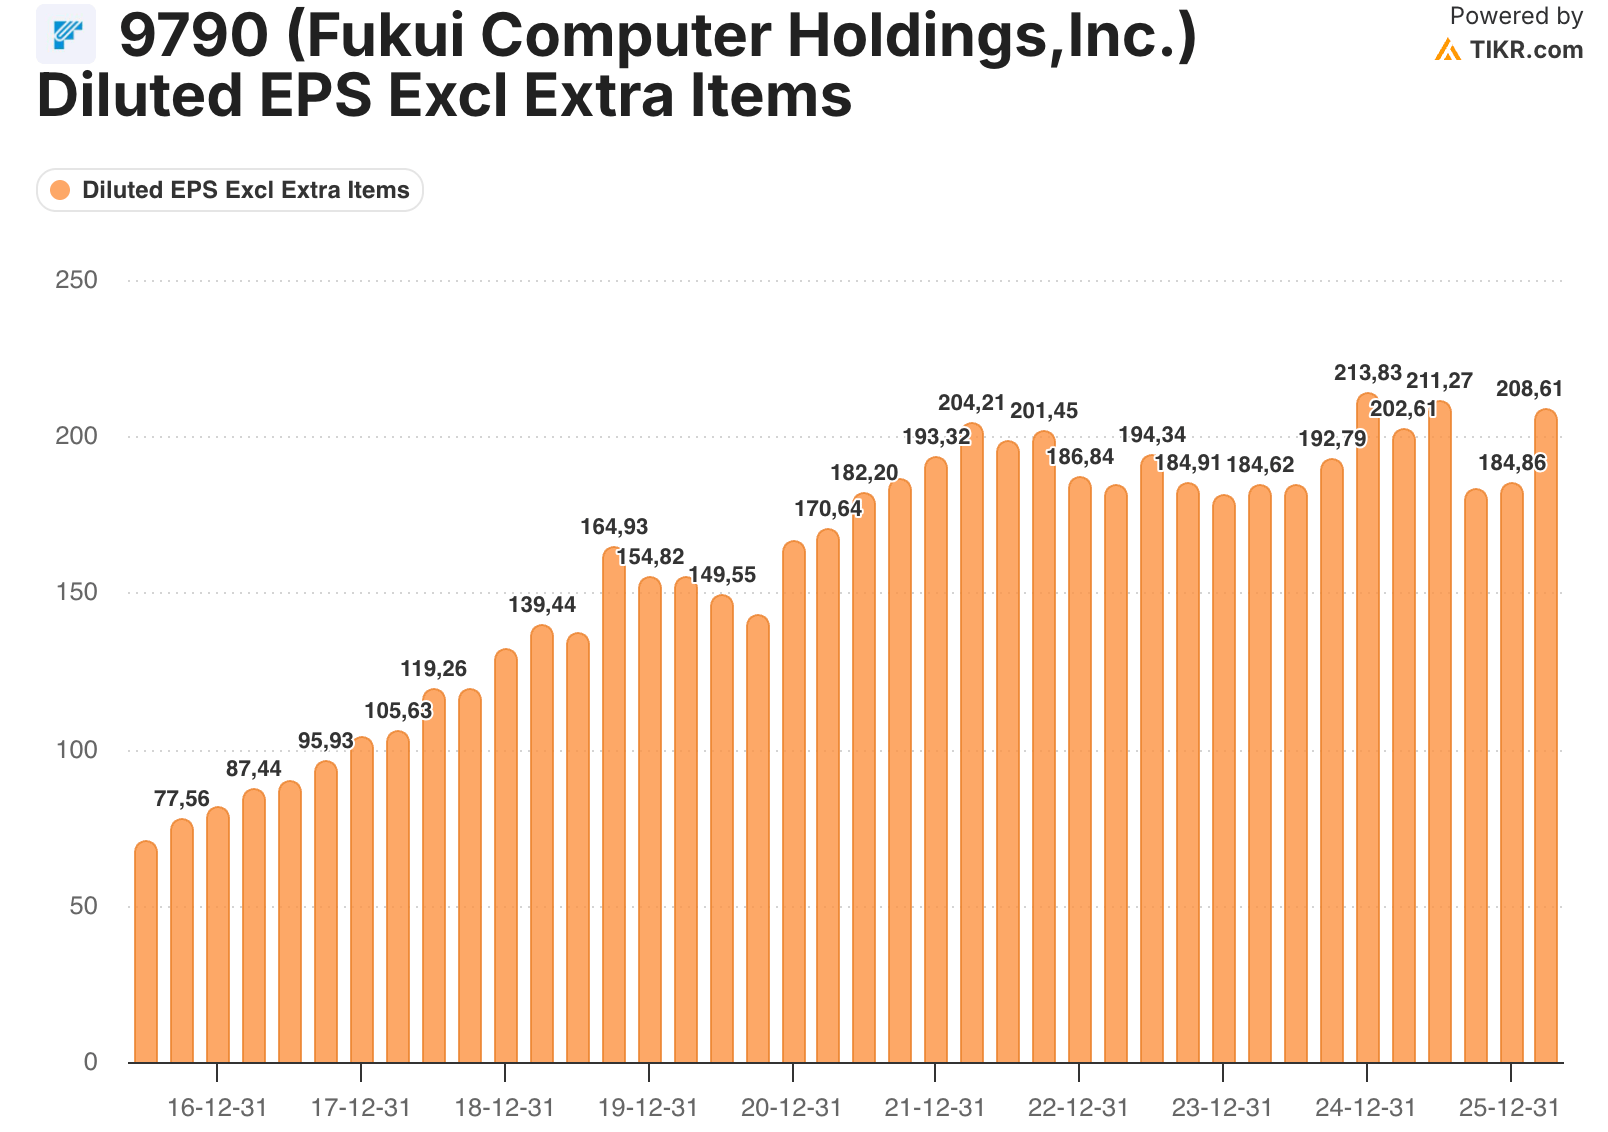
Steady 3x + Accretive Merger : Sharp increase in EPS from 2016 to 2021, then plateau from 2023 to fiscal 2025. In fiscal 2026, EPS went up (EPS 230) without a one time investment charge of 600m Yen. The main product Architrend saw a raise in sales again of 16%.
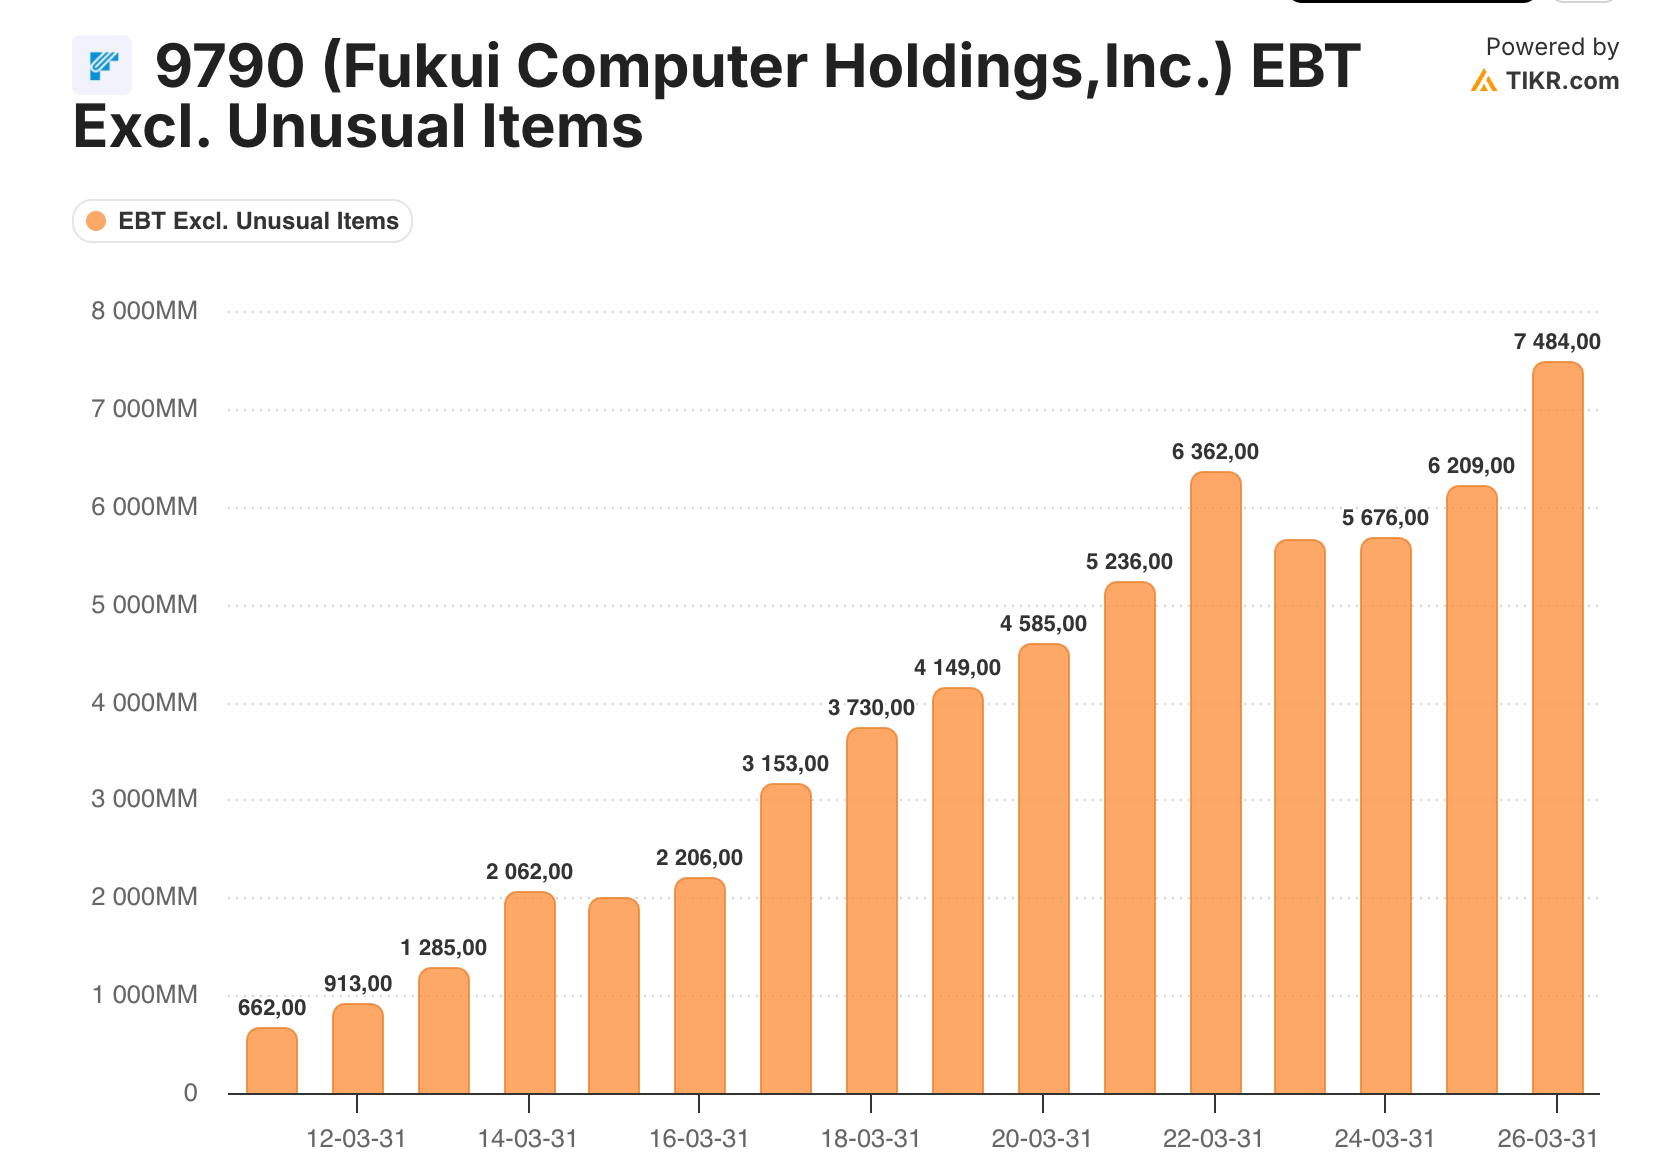
Fukui Computer is merging with its largest shareholder Daitec (47% shareholder) in April 2027. This should be acreditive by almost 20% as Fukui Computer made 350Yen in operating income per share in fiscal 2026 (20 670 000 shares) while post merging, operation combined with Daitec would have generated 16 961 000 thousands Yen or 403 Yen per share in operating income (over 42 058 000 shares). Synergies over a few years should bring EPS to the 300 level in my opinion.
As we can see, besides the drop in 2023 and 2024, operating income has risen steadily since 2011.
6. Robertet
Robertet is the leading natural flavour supplier in the world.
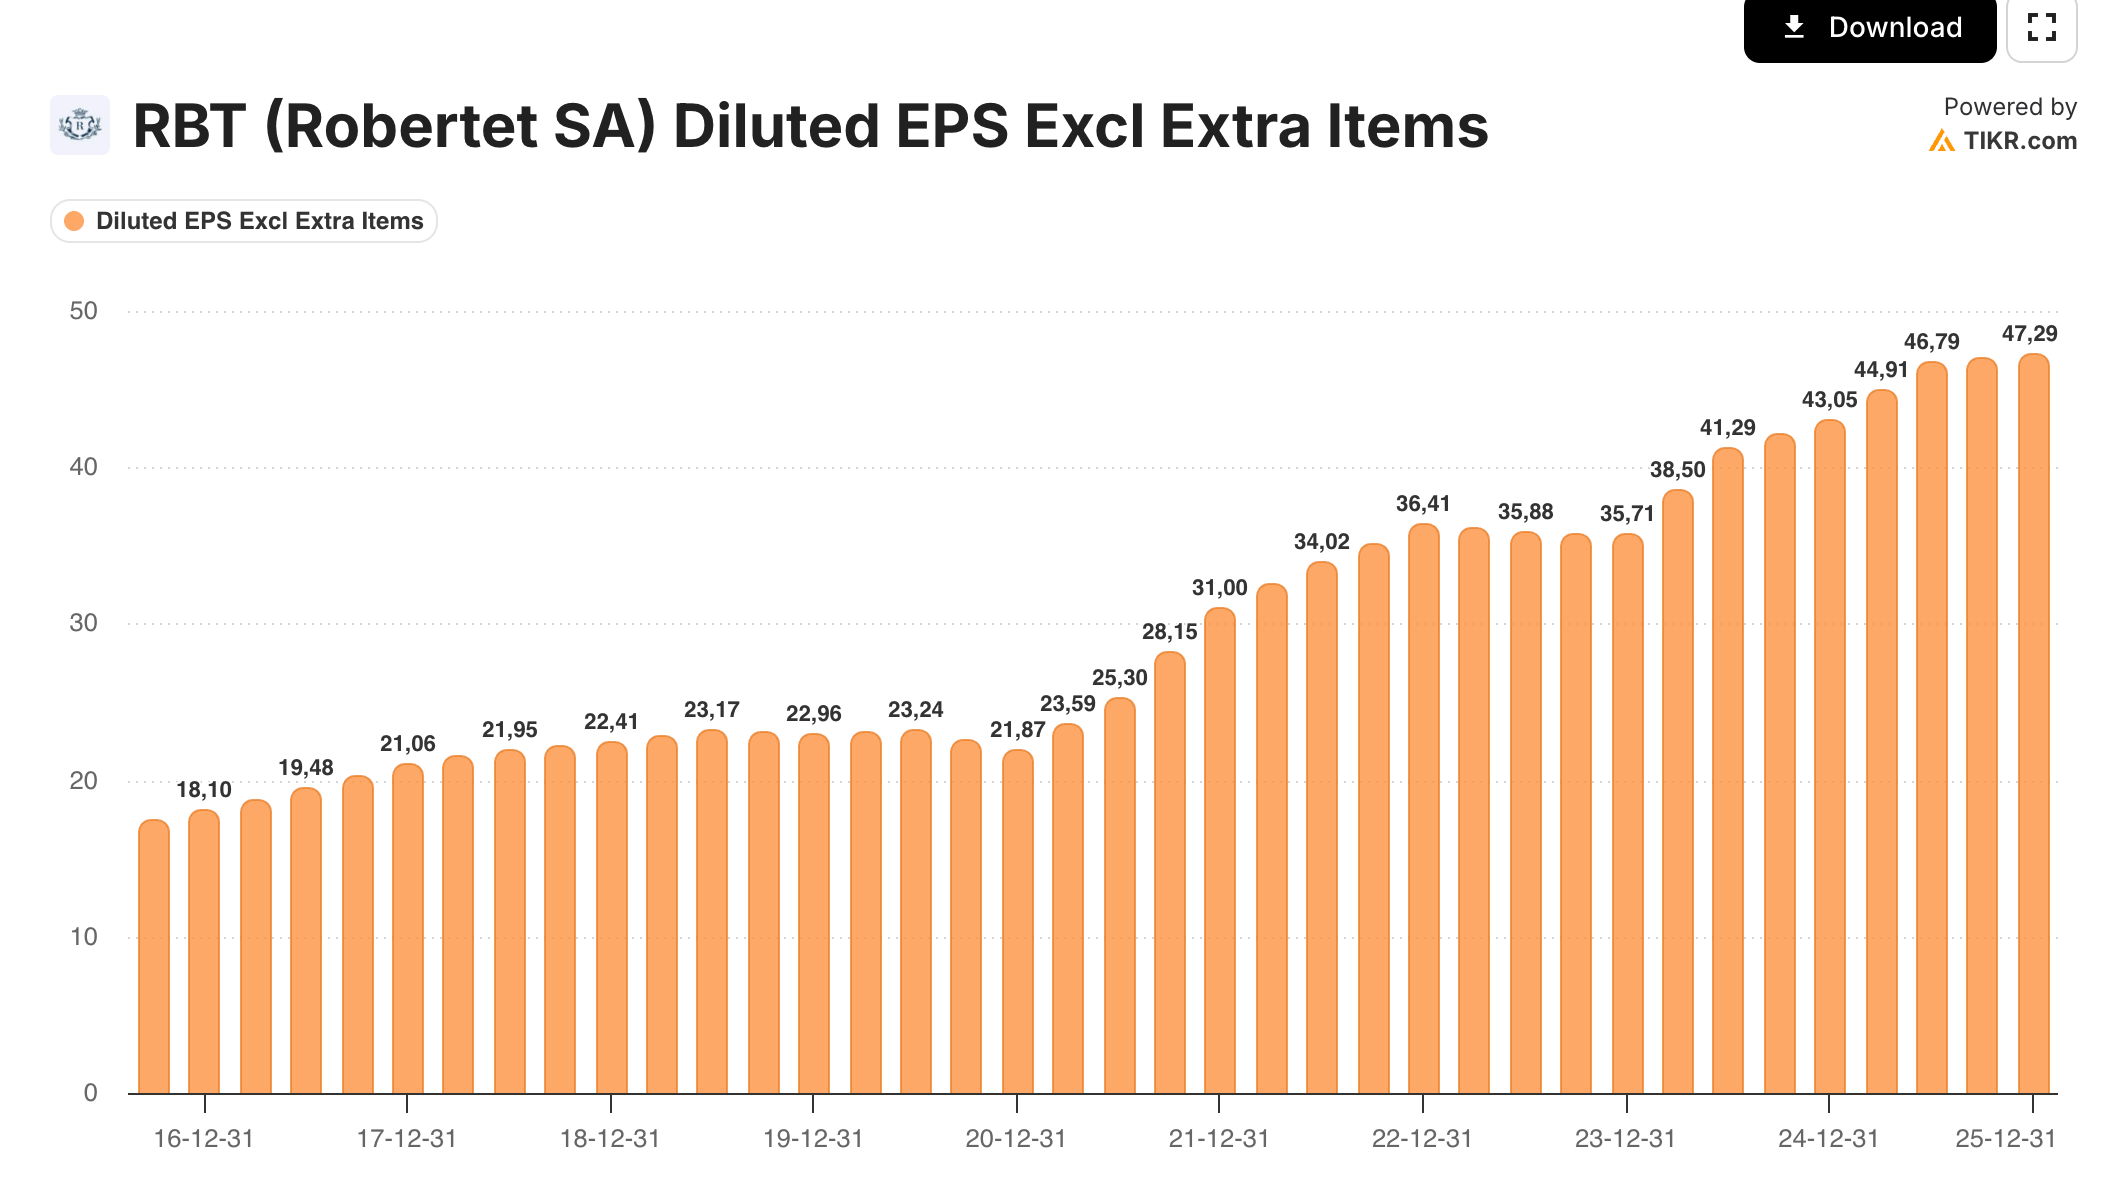
Steady 3x: Robertet has increased EPS steadily by 3x over the last 10 years. The growth is very steady and is immune to economic cycle.
7. Sony
Sony is the leading game console, the #1 music publisher and recorder in terms of operating income and the #1 chip provider for image sensor.
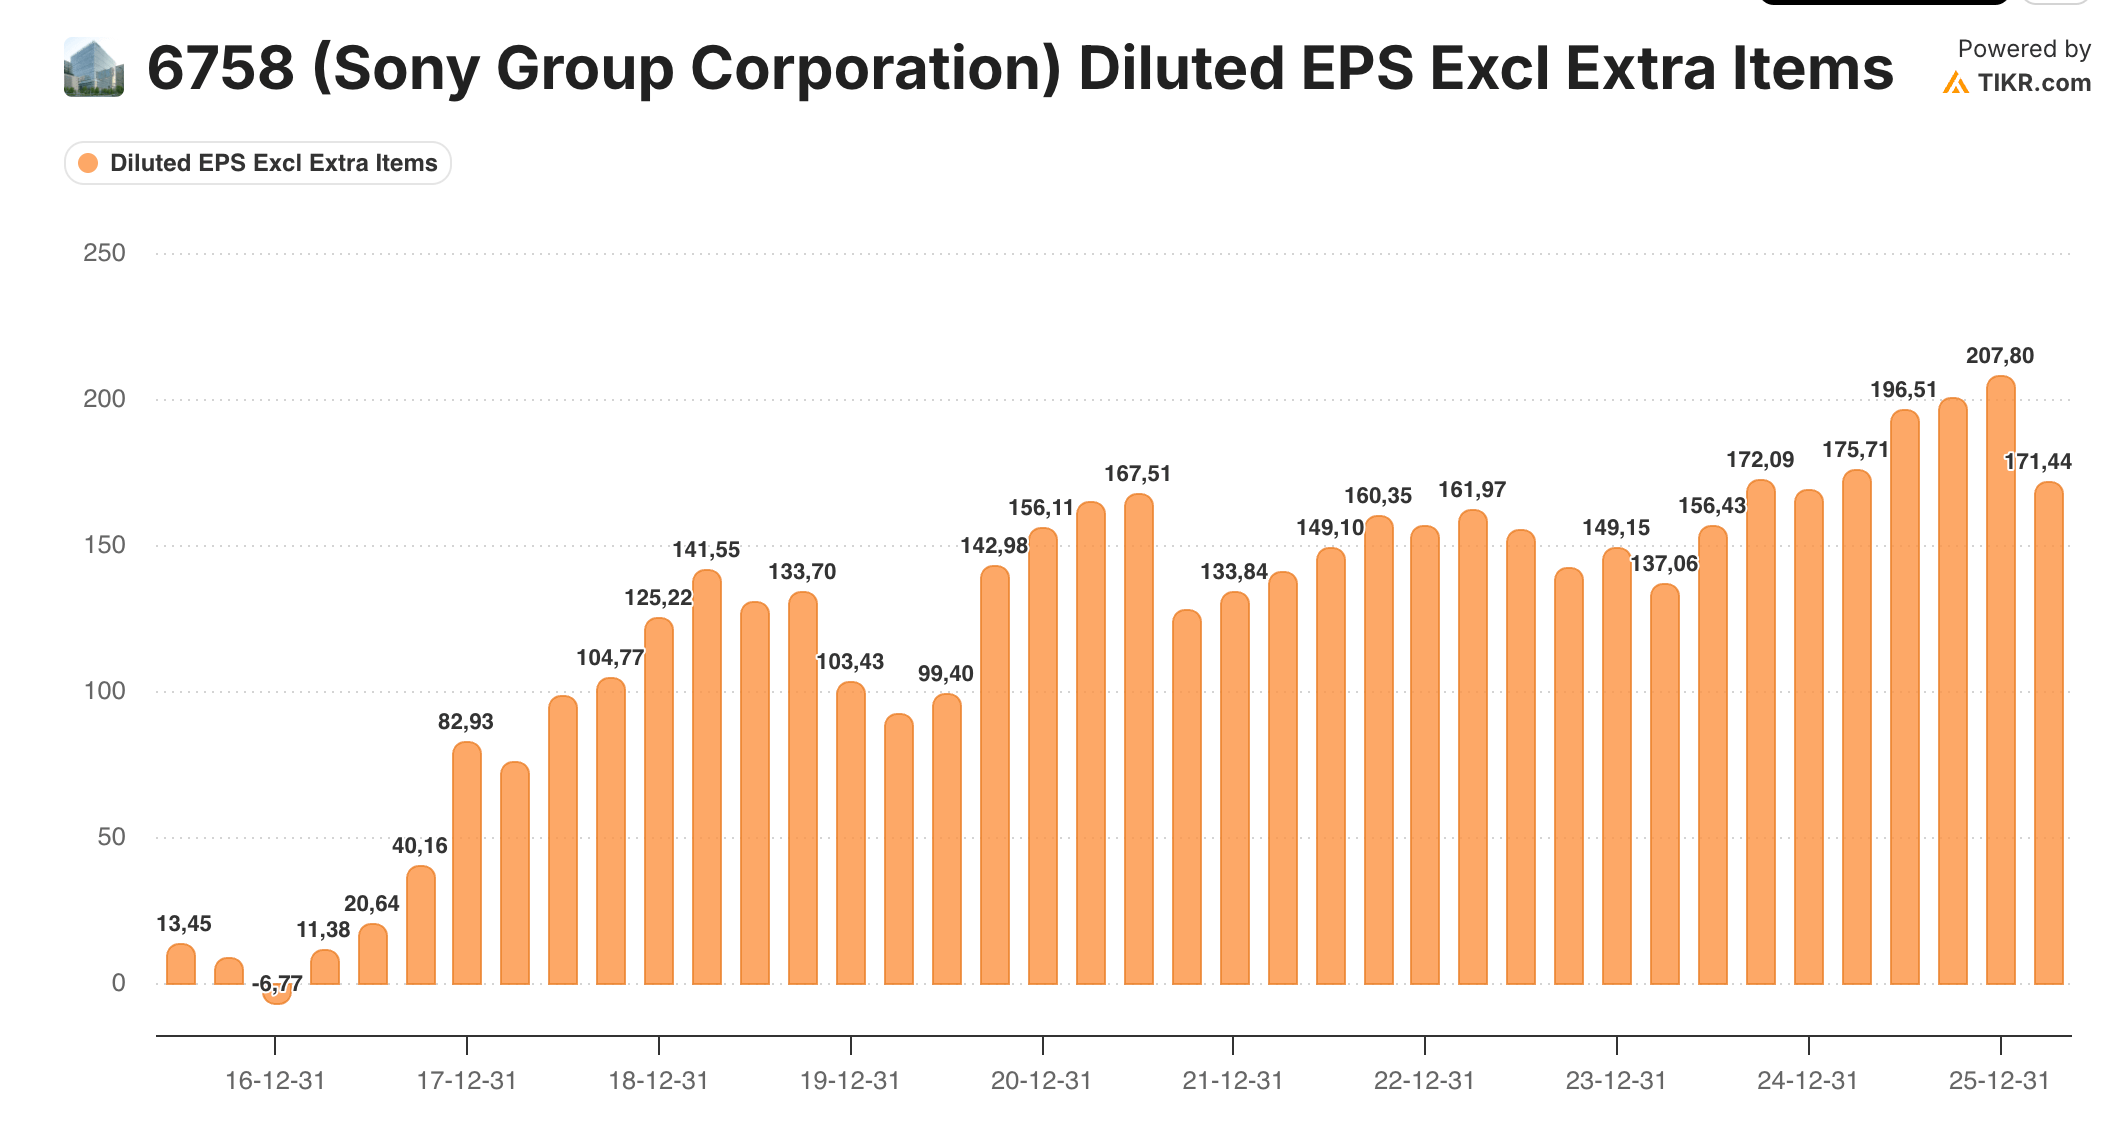
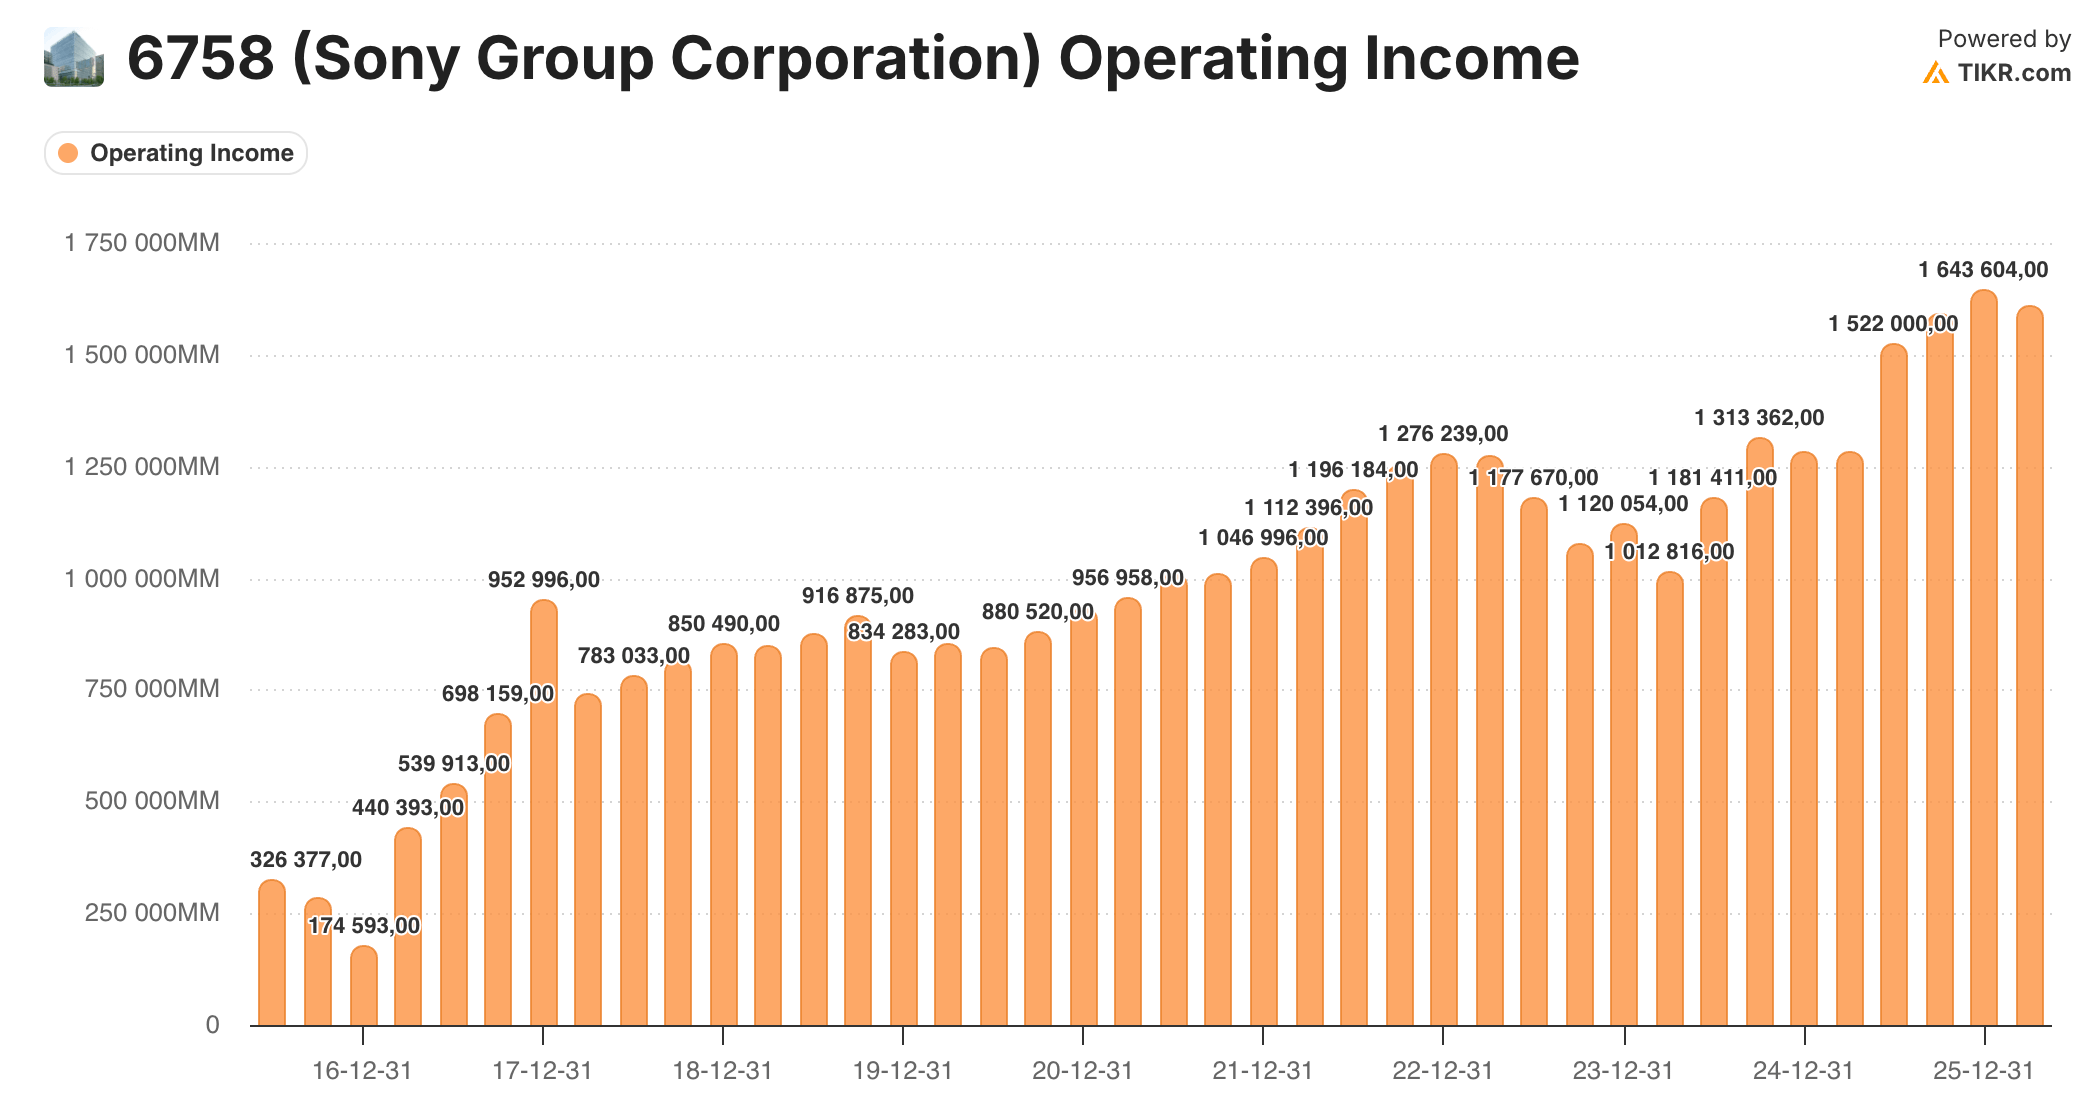
Steady 3x on Operating income. Sony should generate 208 EPS in the current year, so about double the earnings since late 2017, and 3x the operating income over the same period.
8. SAP
SAP is the leading Software Provider of enterprise resource planning (ERP), supply chain, and cloud computing platforms.
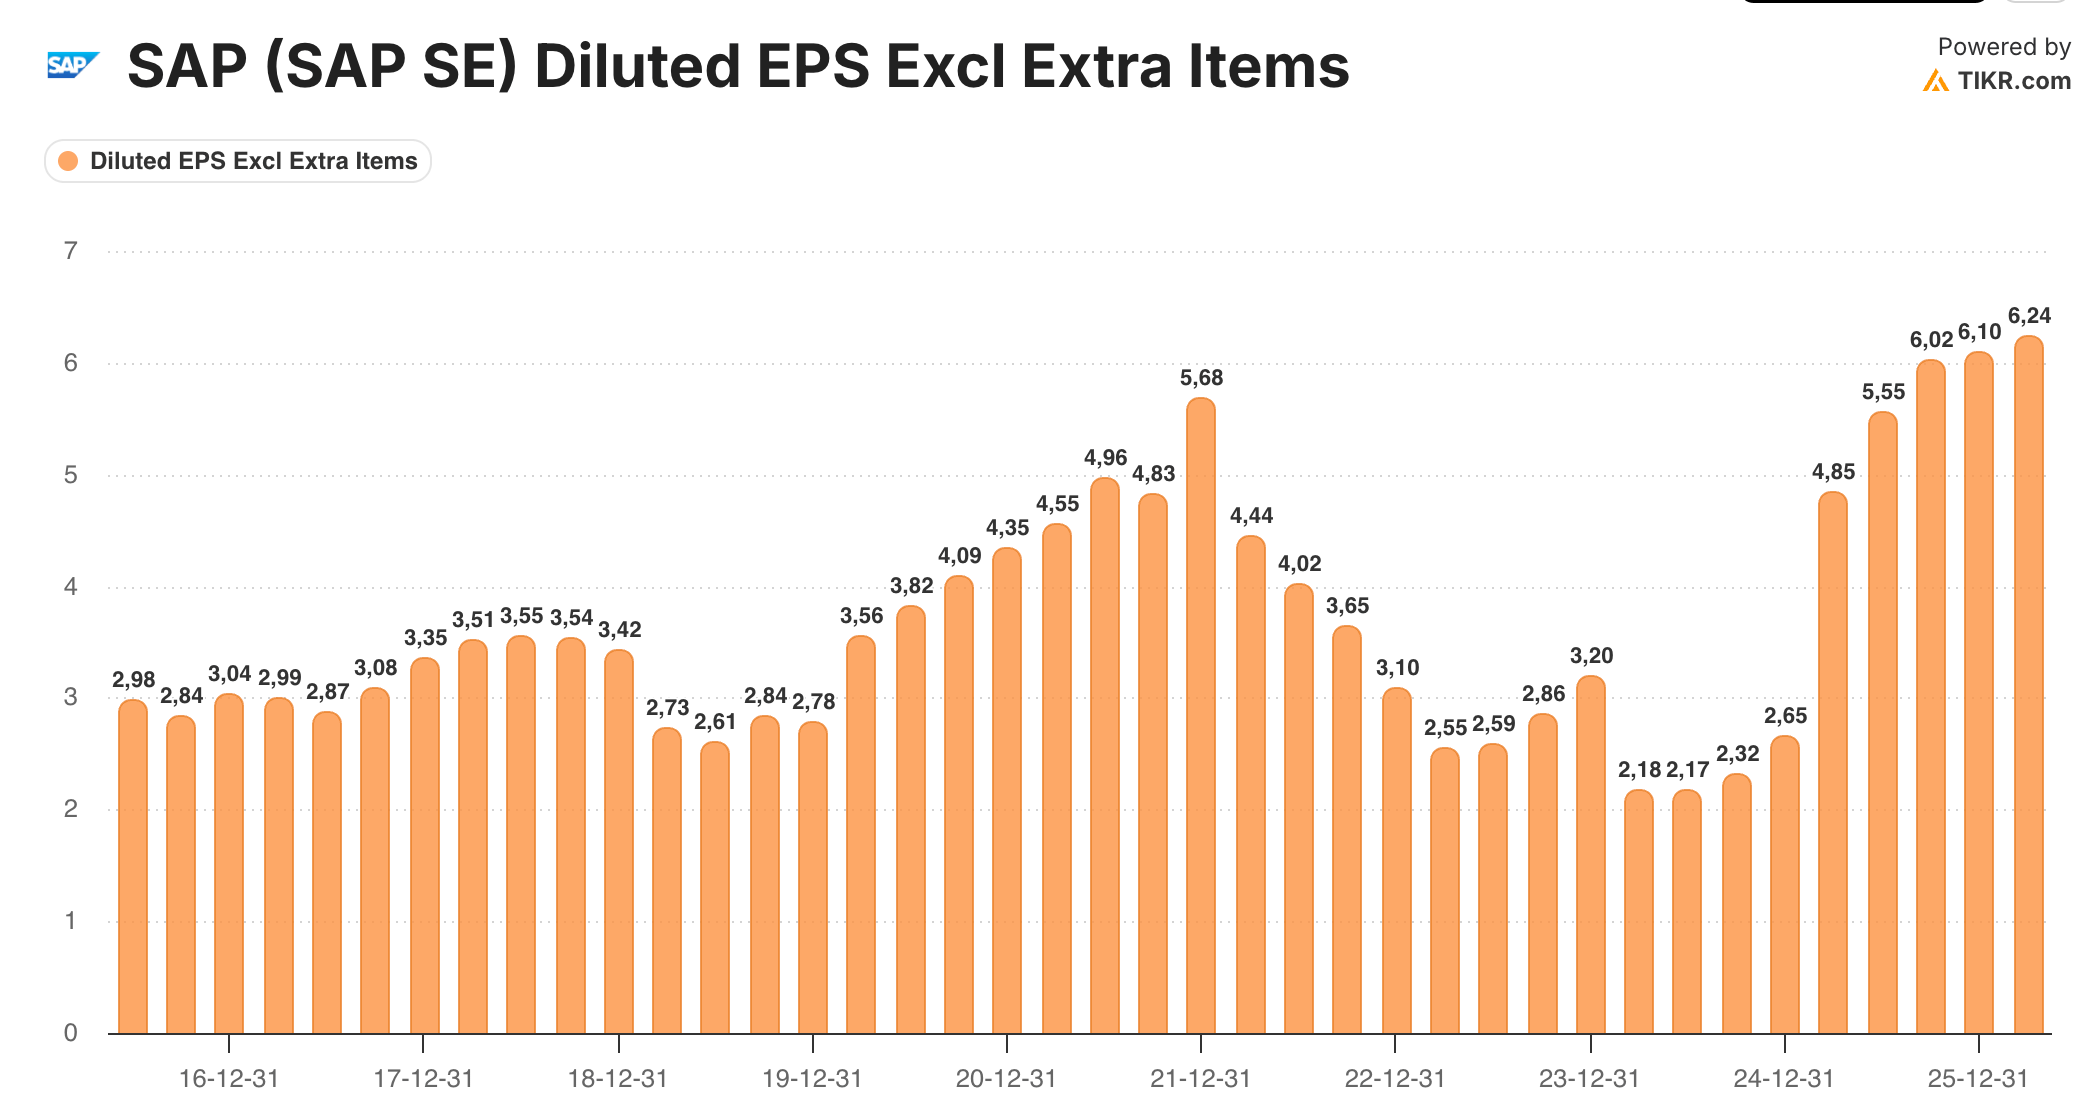
Steady 2x - strong growth in operating income since 2016: EPS has doubled and grown steadily (if you look at operating income included below). Recently, growth has accelerated so there is strong momentum for the next few years.
9. Thermador
Thermador is a leading supplier of valves, pumps, piping, and heating accessories.
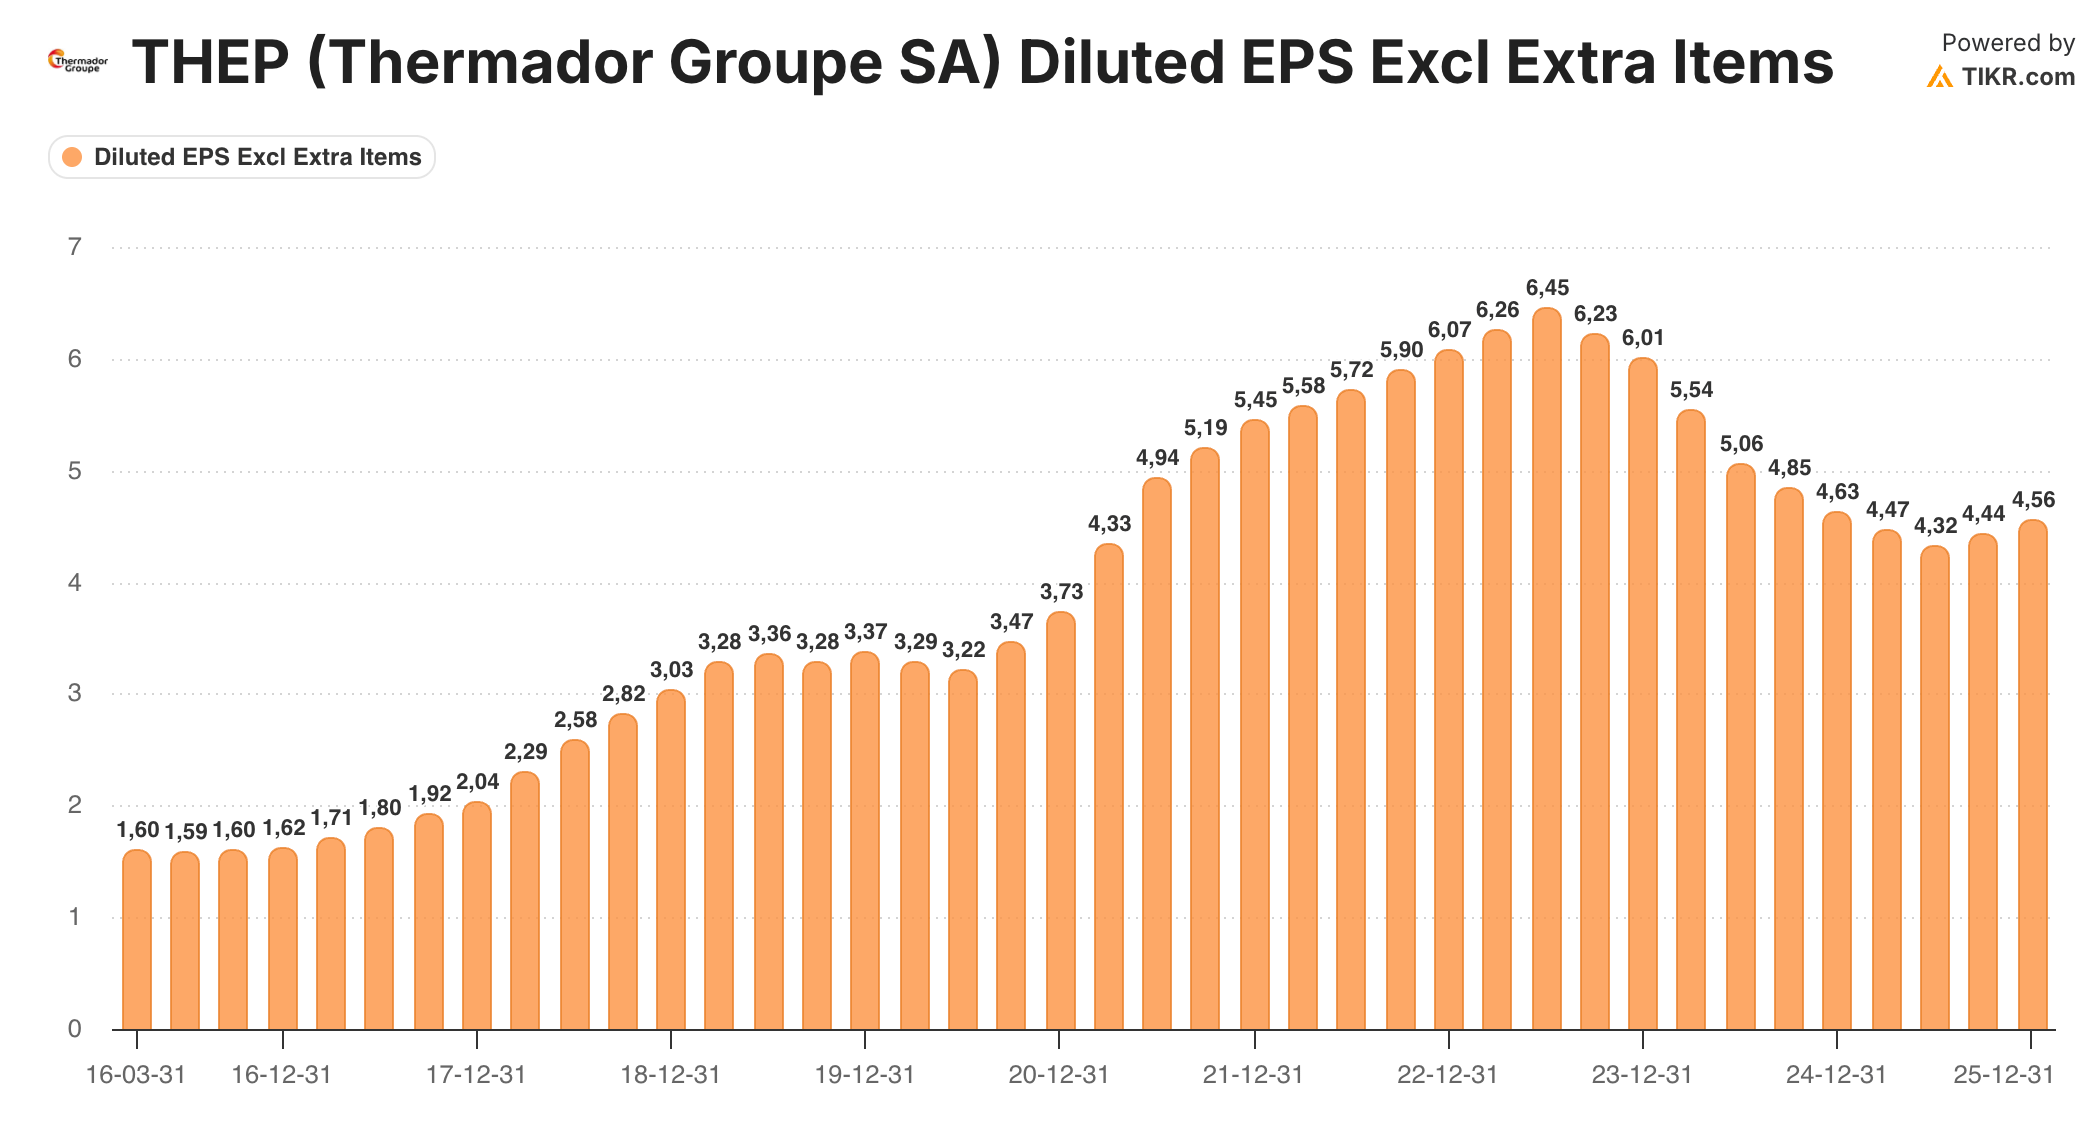
Cyclical 3x: Thermador has tripled the EPS over the last 10 years and EPS growth should resume in 2026. Expected EPS is the 5.30 range. The company is dependant of the France economy so Thermador so Thermador has seen decline in earnings at the start of COVID and recent years. 2026 are showing improvement.
10. Takeuchi
Takeuchi is a leading provider of compact excavator and crawler especially in USA and Western Europe (UK, Germany, France).
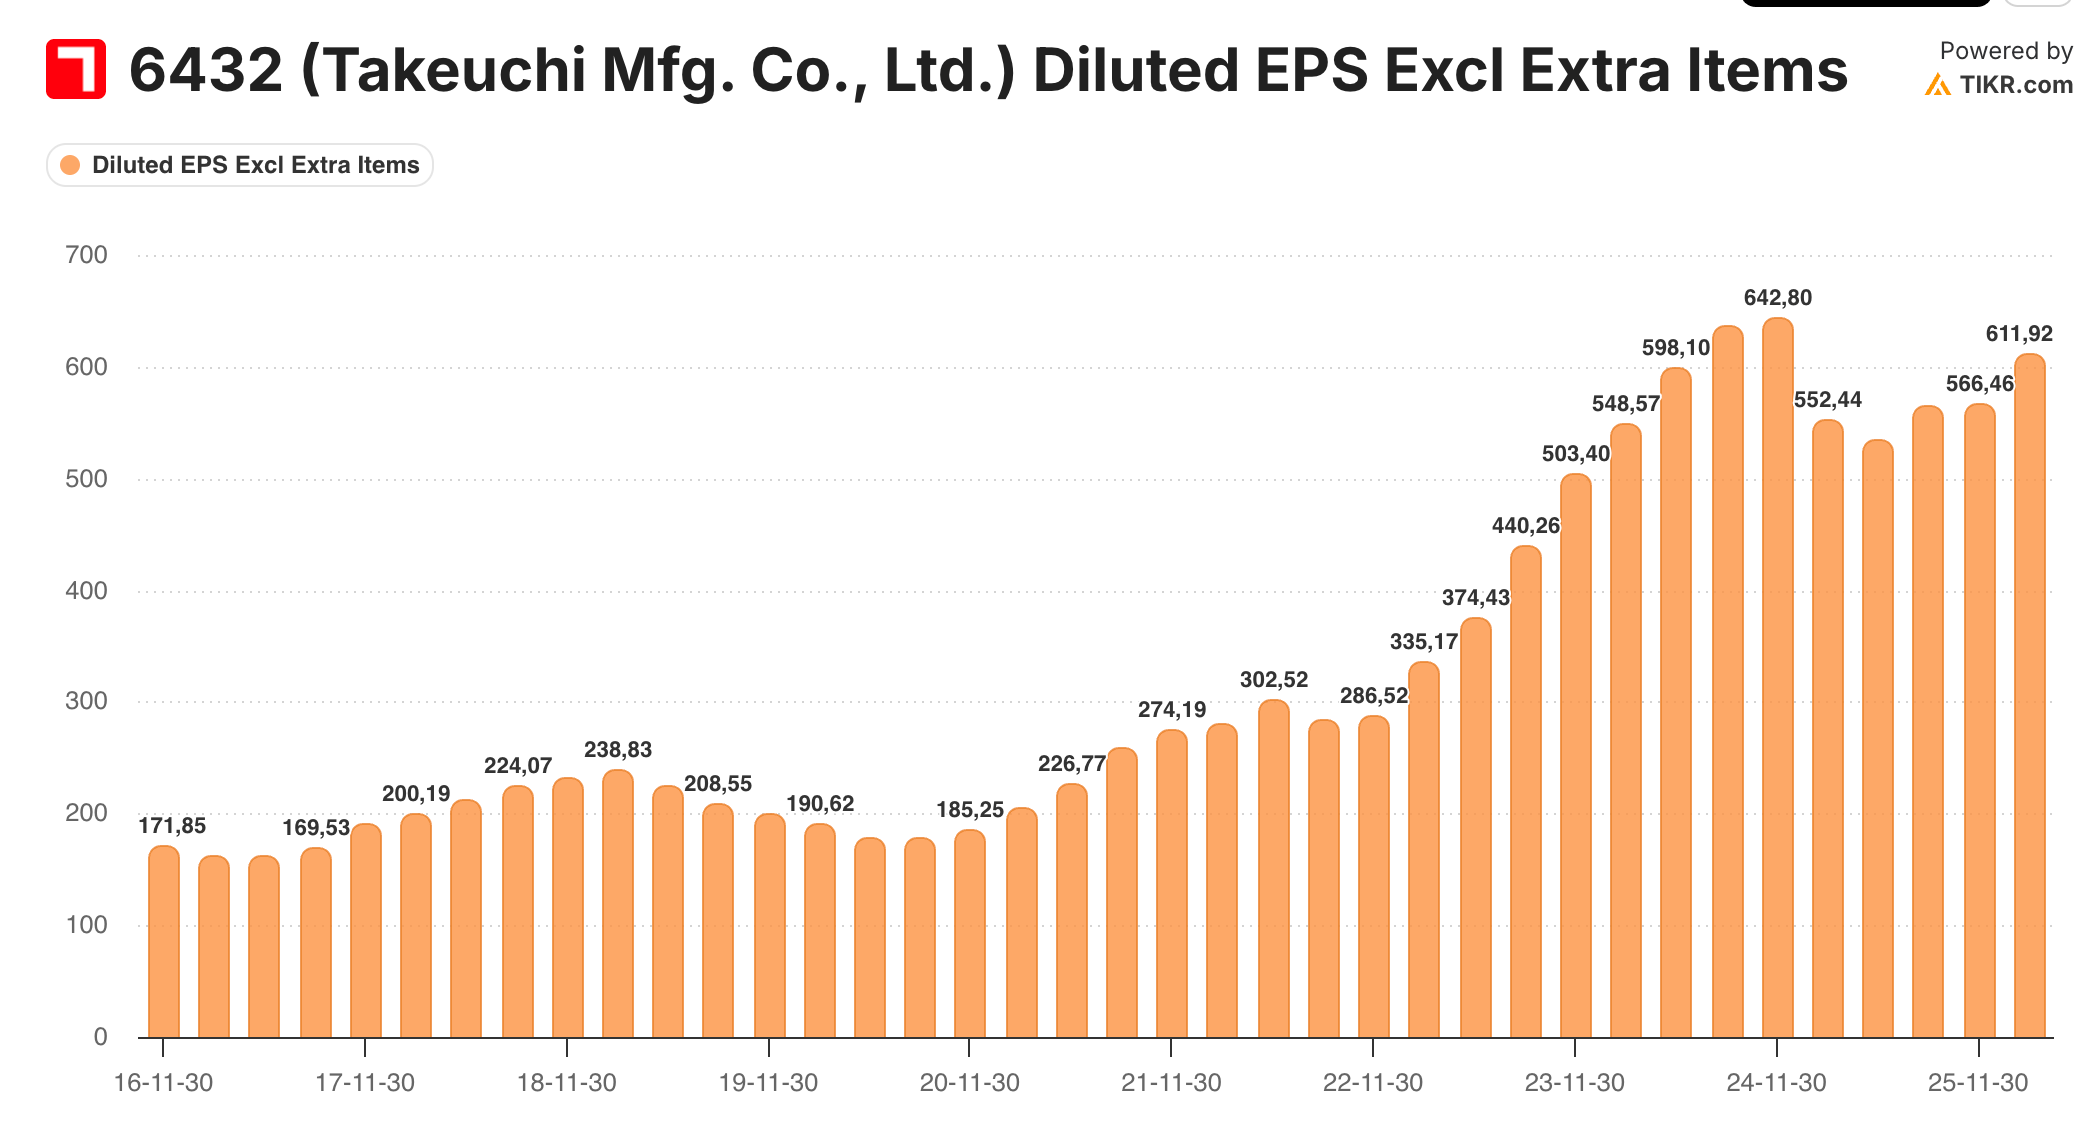
Cyclical 3x: Takeuchi has grown EPS 3x in the last 10 years. Earnings are impacted by tariff with USA which is its largest market. Only half of tariff increase has been compensated by increase price. Expected a small decrease in EPS next year due to continued tariff.
11. Groupe Perrier
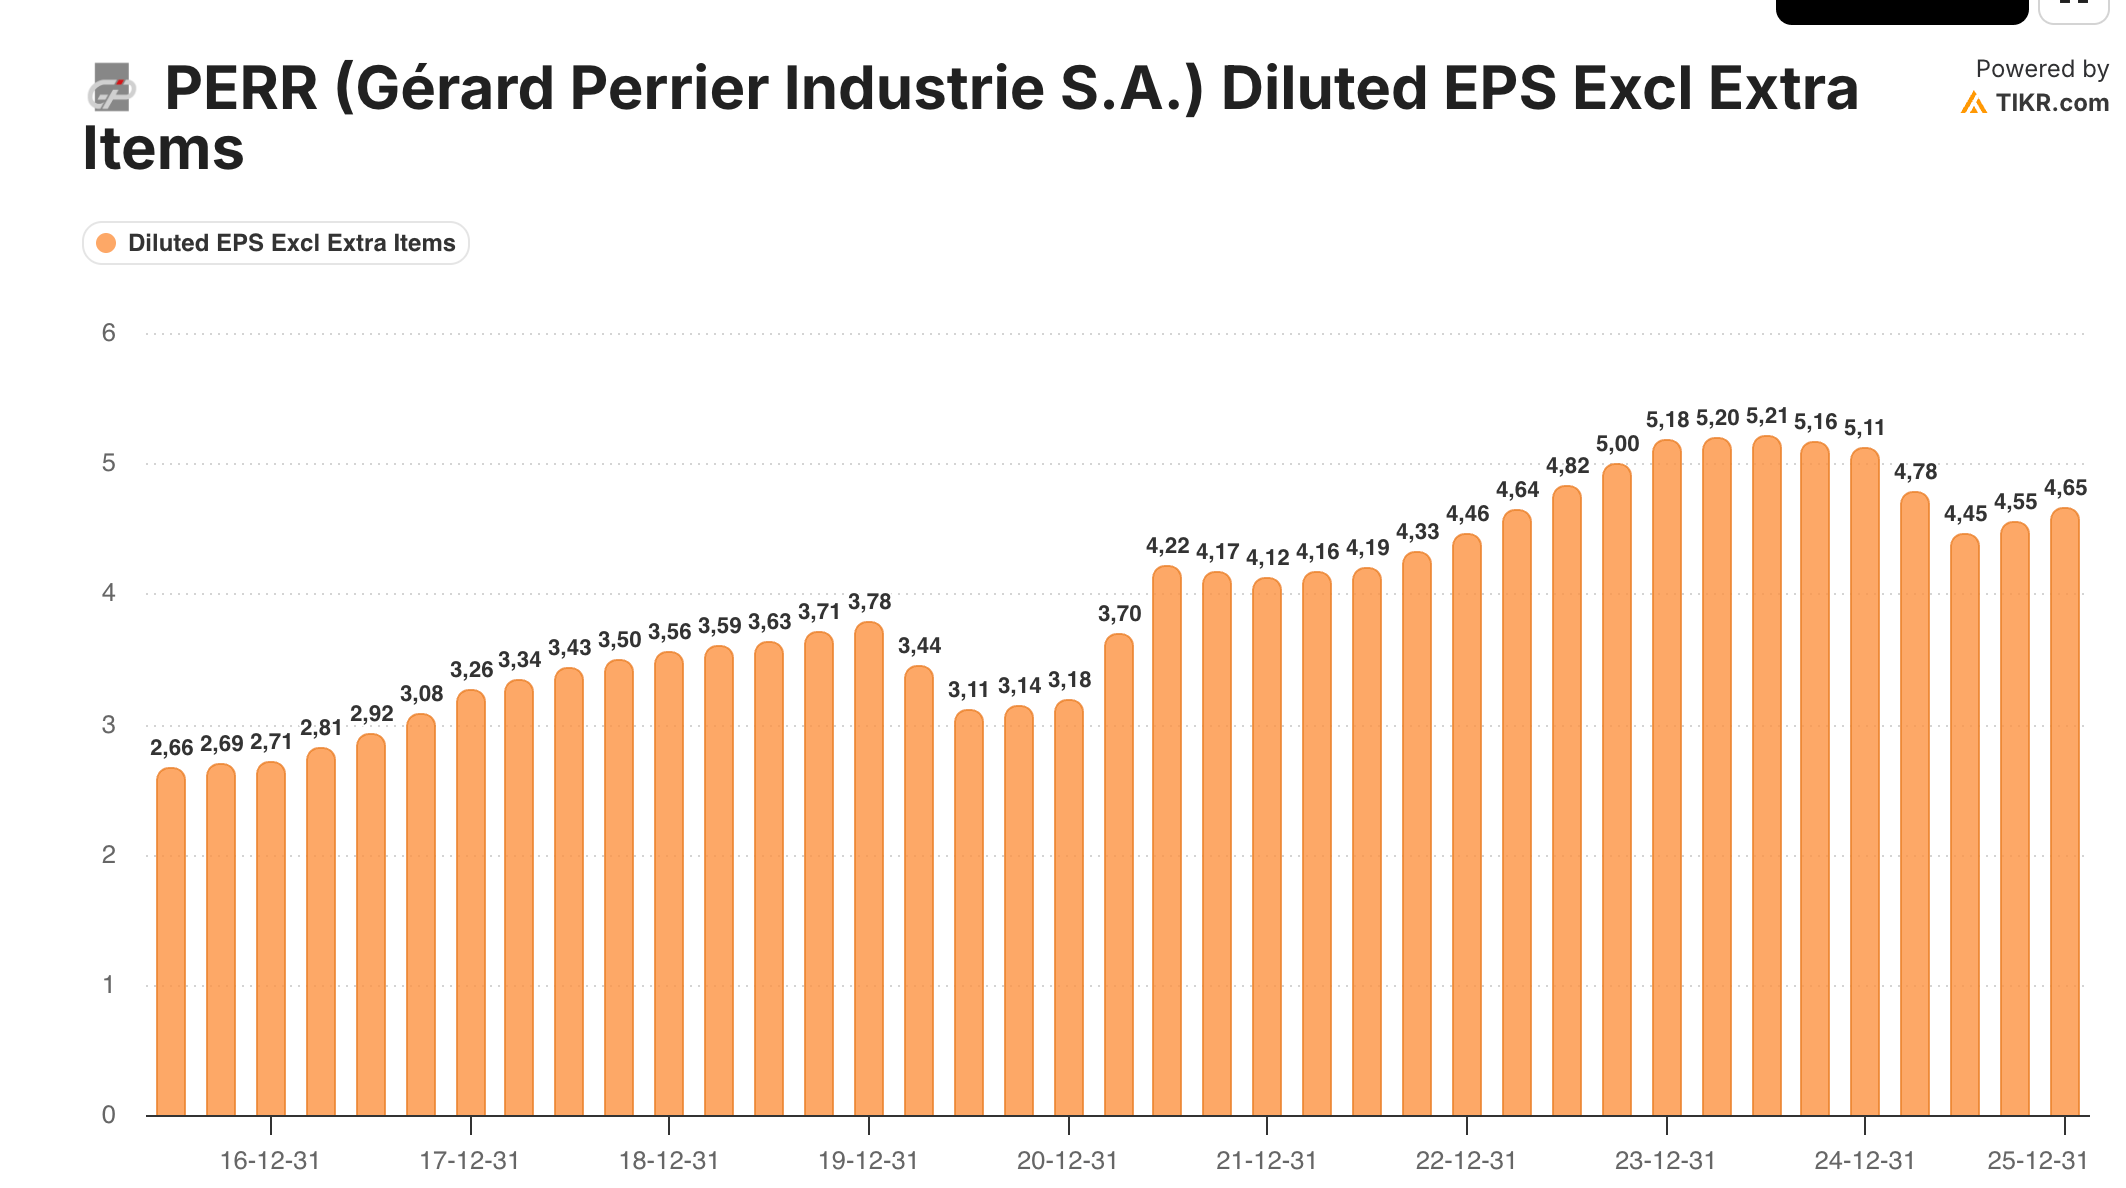
Steady 2x: Steady slow growth with sporadic decline lasting 18 months - as it happen during COVID and now. 2026 should see resumed growth. Expects doubling in EPS every 10 years.
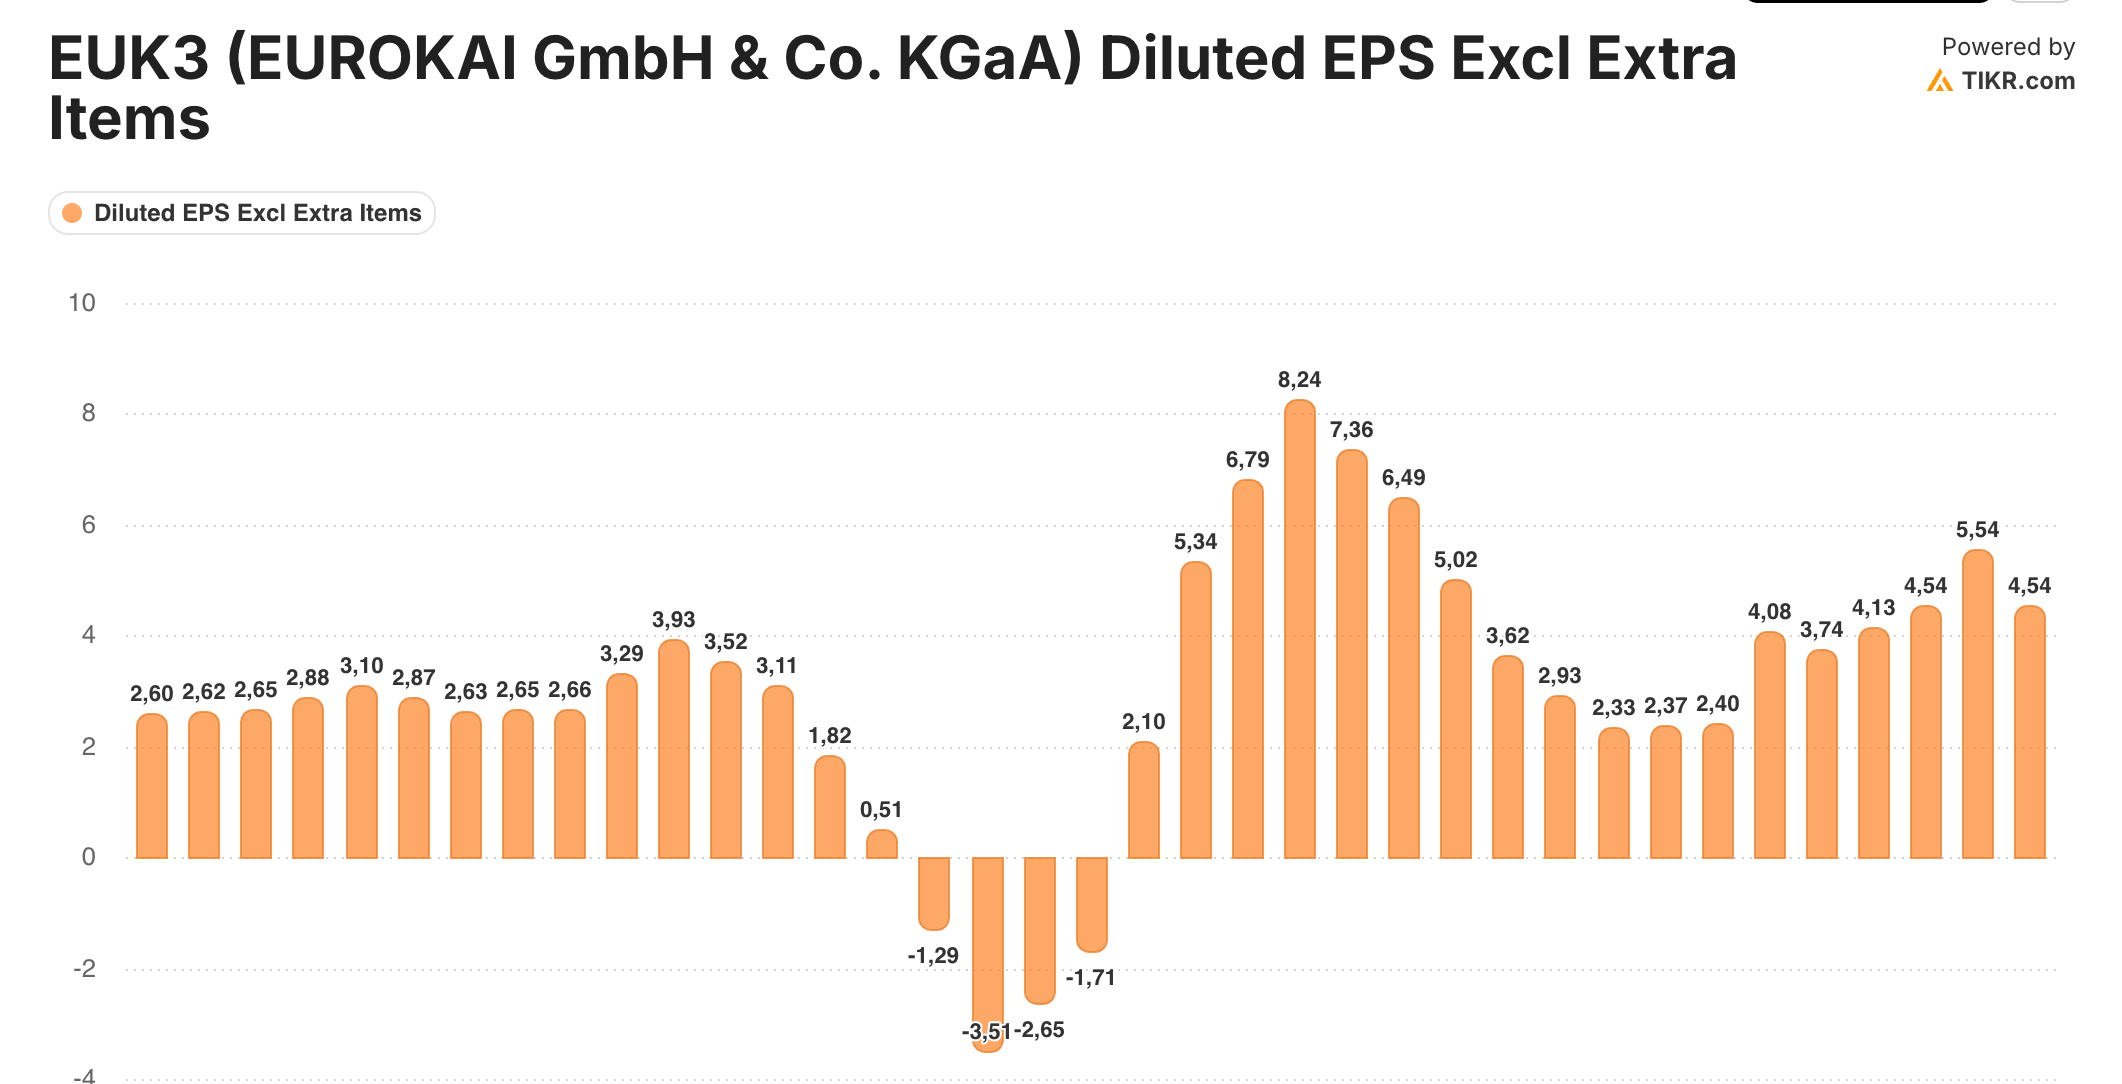
12. Eurokai
The group operates a vital network of container hubs across the North Sea (Germany), Mediterranean, and Atlantic.
Cyclical 2x: Eurokai has doubled its EPS over the last 10 years with some cyclicality.
Overall Ranking
If we combine both rankings, we get the following table:

Teikoku and Kimura Kohki end up being ranked first ex-equo. Followed by Fukui Computer, Takeuchi and Intuit.
In terms of earnings quality, Intuit, Kimura Kohki are really standing apart and as such deserve a certain premium, both in terms of growth and short term earnings momentum. Teikoku being my largest positions among those 12 names, based on this I will increase further my holdings on Intuit and Kimura Kohki.
Trade carefully
Any quality name in this PE range, feel free to mention those in comments
Legal Disclaimer: All content published on Wintergems is intended for informational and entertainment purposes only. It is not intended to serve as a recommendation to buy or sell any security. The views expressed are my own and are subject to change without notice. The information provided here is proprietary. I make no representations or warranties as to the accuracy or completeness of the information provided and will not be liable for any losses, injuries, or damages from the display or use of this information. Readers are solely responsible for their own investment decisions.
Do not touch Intuit now, a reset to outlook & numbers is coming in the September investor day or even earlier in the next results.
Do you know why the share price for Teikoku dropped 20% today? I was only able to find this report https://www.teikokucp.co.jp/english/ir/news/